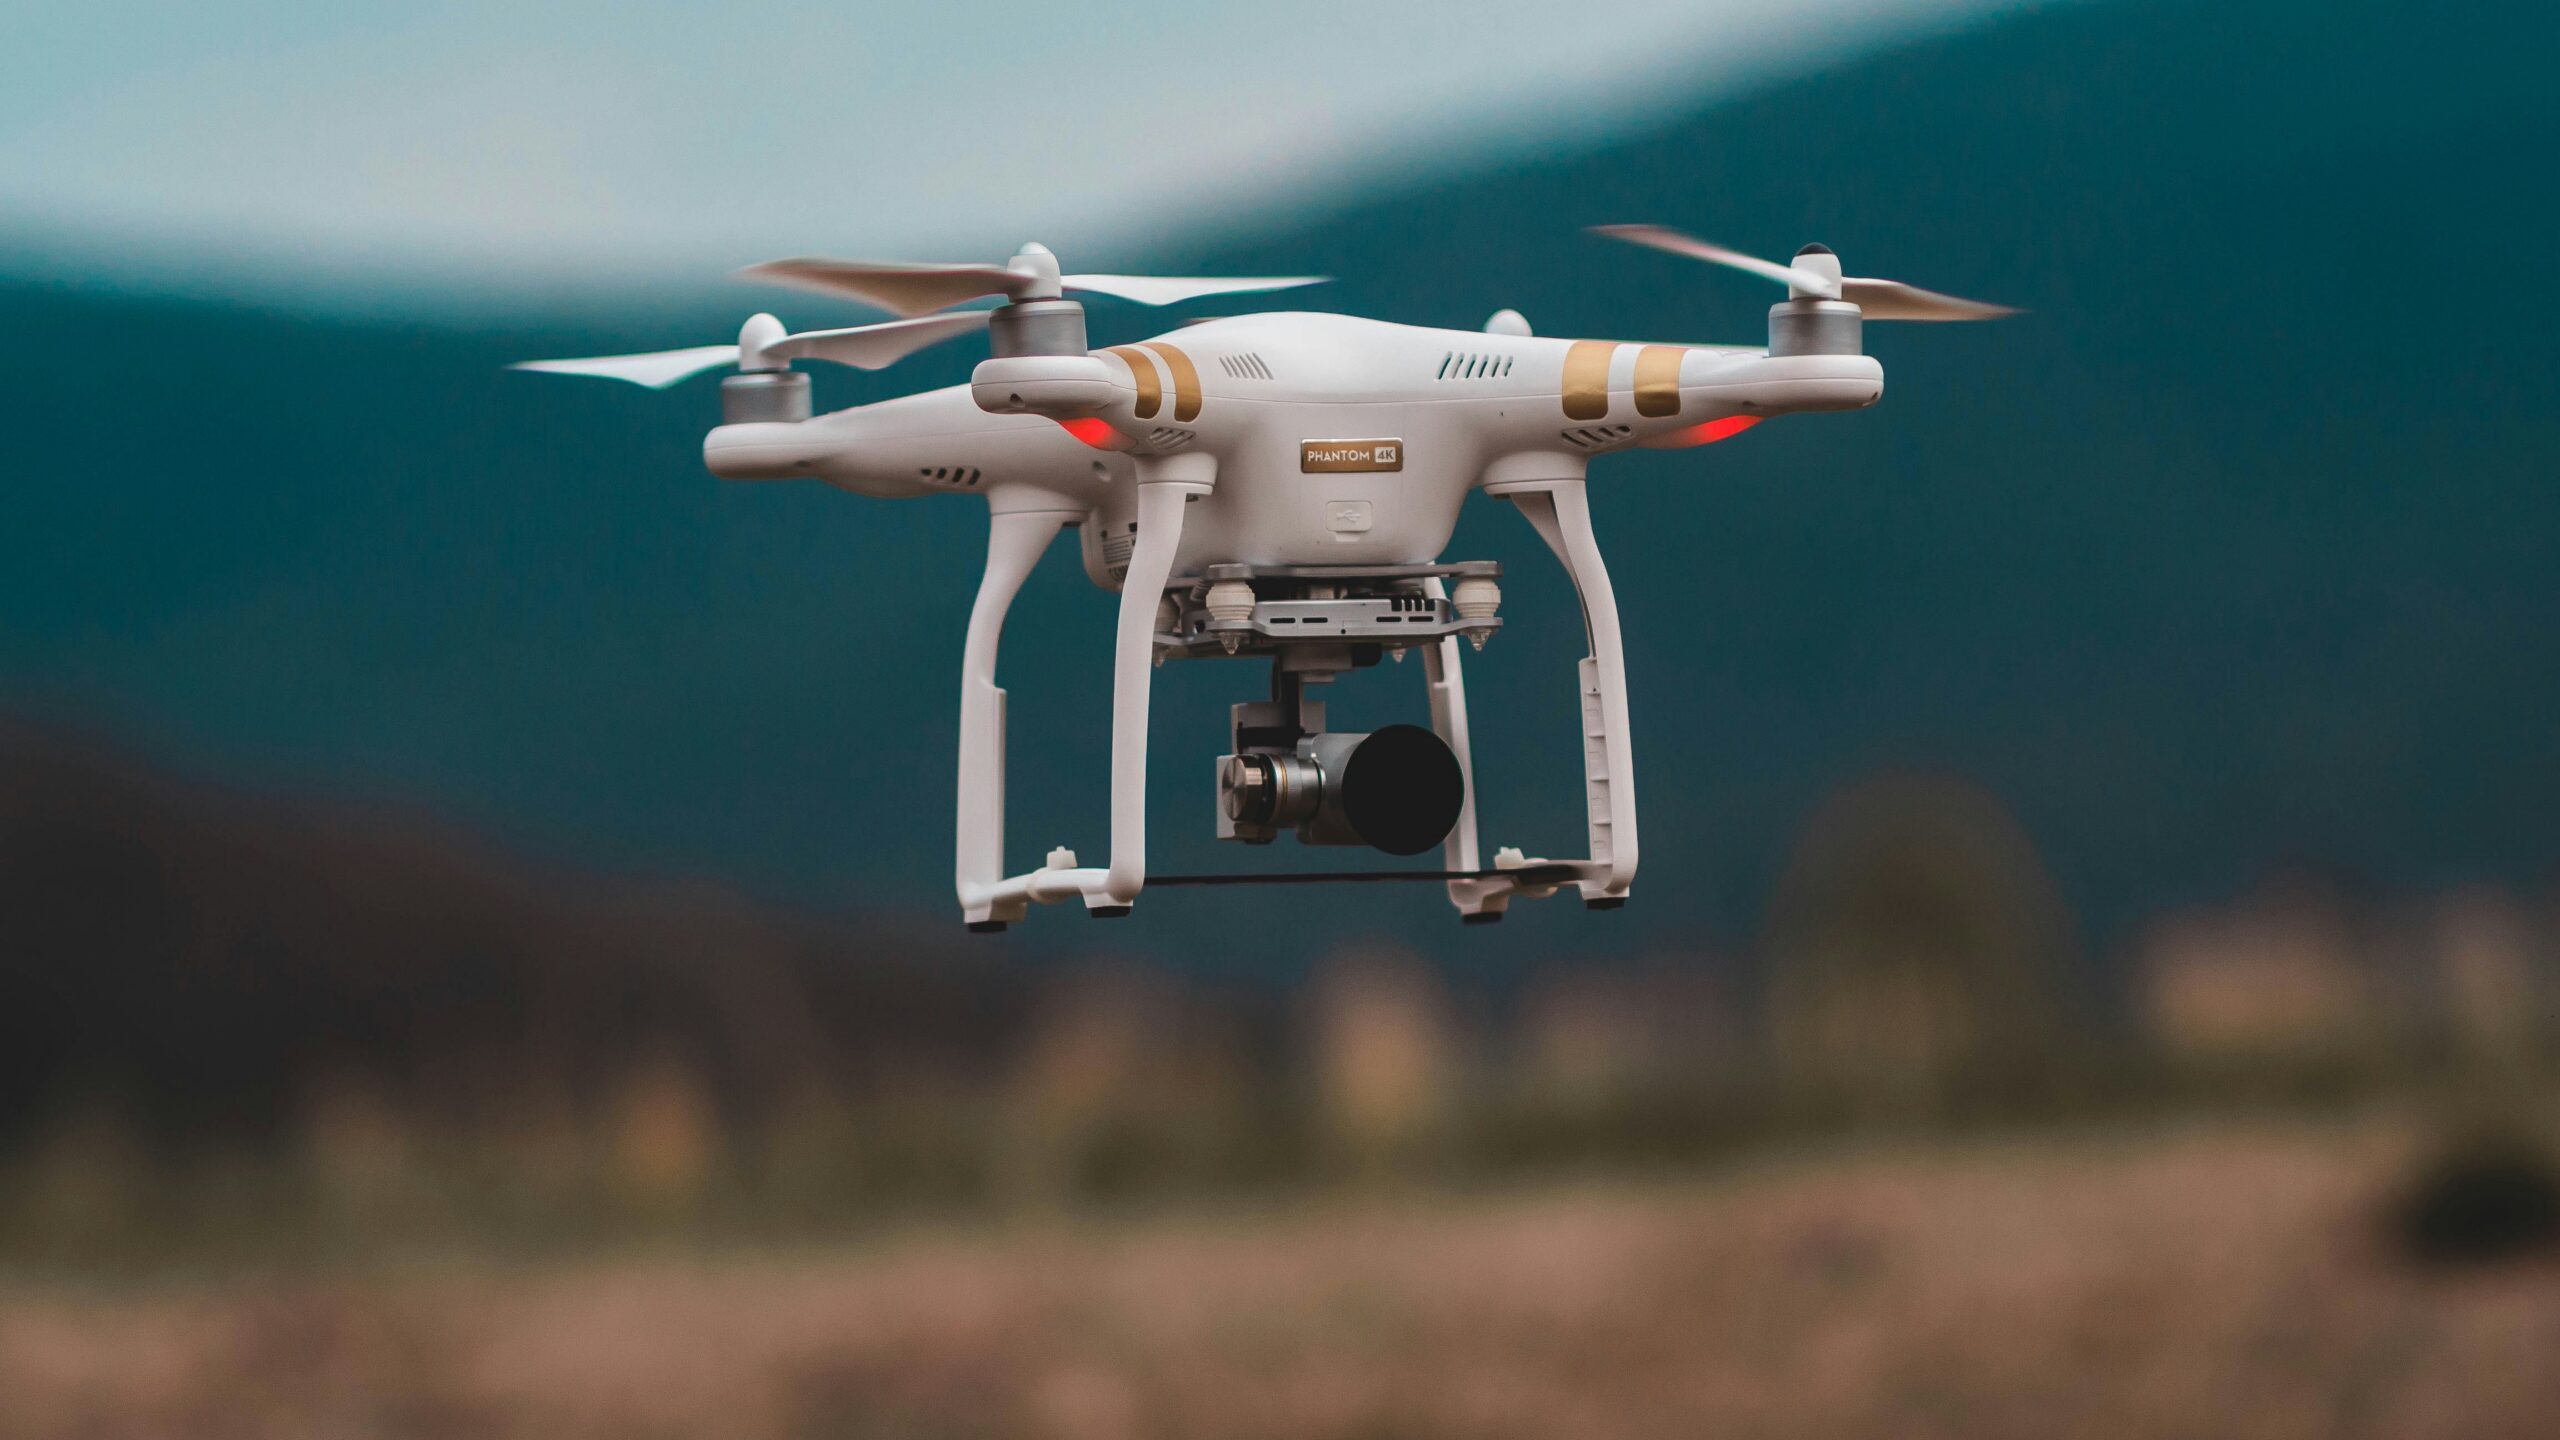
California homeowners are losing insurance policies after carriers flag roof moss, tree shadows, or minor wear spotted in drone and satellite photos, and state regulators say some of those cancellations were flat-out wrong. The California Department of Insurance has fielded complaints from policyholders whose coverage was dropped based on imprecise aerial imagery, and Insurance Commissioner Ricardo Lara is now backing legislation that would force insurers to share every image and data source they relied on before cutting someone loose. A bill moving through the state legislature, SB-1301, would give homeowners the right to see the evidence, challenge the findings, and fix problems before their policies vanish.
Aerial surveillance and the nonrenewal wave hitting California homeowners
The core tension is straightforward: insurers are adopting remote-sensing technology to assess roof conditions at scale, but the tools are producing false positives that cost real people their coverage. A patch of moss, a shadow cast by an overhanging branch, or discoloration from pollen can register as structural damage in an algorithm’s assessment. When a carrier acts on that flawed reading, the homeowner receives a nonrenewal notice, often with little explanation and no chance to respond before the policy lapses.
California’s insurance regulator has documented complaints where flawed aerial imagery led to wrongful cancellations or nonrenewals, according to the California Department of Insurance. Those complaints include cases involving imprecise drone and satellite roof assessments. The pattern raises a pointed question: are carriers in wildfire-prone ZIP codes using aerial imagery to accelerate nonrenewals beyond what actual roof age and claims history would justify? No public dataset yet isolates that variable, but the volume of complaints reaching the state regulator suggests the technology is outpacing the accuracy needed to make fair coverage decisions.
Insurers argue that aerial and satellite tools let them monitor risk more efficiently, especially as climate-driven disasters push up losses. High-resolution flyovers and machine-learning models can flag missing shingles, debris, or overgrown vegetation without sending an inspector to every property. Industry executives have also told national outlets that these systems help keep premiums in check by catching serious maintenance issues early. But for individual homeowners, the same tools can feel like a one-sided surveillance regime, where an opaque algorithm judges their roof from hundreds of feet in the air.
Recent national reporting has described homeowners around the country surprised to learn that overhead photos were behind sudden coverage decisions. In California, where the property insurance market is already strained by wildfire risk and carrier pullbacks, the stakes are even higher. When a policy is dropped over what turns out to be a misread shadow or harmless staining, the homeowner may struggle to find any replacement coverage at all, let alone at a comparable price.
For homeowners, the practical damage is immediate. Losing a policy in a tightening market means scrambling for replacement coverage that may cost far more or carry steep exclusions. In fire-prone areas of California, some residents have been pushed into the state’s insurer of last resort, which offers thinner protection at higher premiums. The gap between what a satellite sees and what a roofer would find on a ladder is becoming a financial crisis for individual households.
SB-1301 and the disclosure rules carriers would face
The legislative response centers on SB-1301, a bill in the California 2025-2026 session titled “Residential property insurance: nonrenewals.” The bill would require insurers to provide all imagery or other documentation and the sources used when issuing a nonrenewal notice. It also includes remediation and explanation requirements, meaning carriers would need to spell out exactly what condition triggered the decision and give homeowners a window to address the issue before coverage ends.
Commissioner Lara has publicly supported the legislation, framing it as a measure to protect homeowners’ privacy and increase transparency in how insurers use aerial imagery. His office’s stance builds on the department’s existing investigations, which found that technology-driven assessments were sometimes inaccurate enough to produce wrongful outcomes. Under SB-1301, carriers would not be barred from using drones or satellites, but they would have to show their work: every image, every third-party data feed, and the reasoning that turned those pixels into a nonrenewal notice.
The bill would also formalize a chance to cure alleged defects. If an insurer claims a roof is in poor condition based on an aerial shot, the homeowner would be entitled to see that image, hire a contractor for an on-the-ground inspection, and perform repairs if needed before losing coverage. In cases where the aerial reading is simply wrong, the homeowner could submit contrary evidence and demand reconsideration. That process could help distinguish between genuinely risky properties and those caught in the dragnet of overzealous automation.
Privacy concerns run alongside the accuracy debate. Many homeowners have no idea their properties are being photographed and analyzed beyond the traditional in-person inspection. While aerial mapping of neighborhoods is not new, the combination of frequent flyovers, detailed roof scoring, and automated decision-making feels different when it can determine whether a family keeps or loses its insurance. By forcing disclosure of data sources, SB-1301 would at least give consumers visibility into who is watching their homes from above and how that information is being used.
Insurers warn that additional mandates could raise administrative costs and slow their ability to manage risk in a volatile climate. They contend that remote assessments are essential in a state as large and hazard-prone as California. But the mounting complaints before state regulators highlight the risk of leaning too heavily on imperfect tools without providing due process. SB-1301 tries to thread that needle: preserving the efficiency of aerial technology while giving homeowners a clearer path to contest errors and keep their coverage from disappearing over a misinterpreted image.