The tax law signed in 2025 handed Americans 65 and older a new deduction worth up to $6,000, but the break was never designed to reach every retiree equally. It narrows as income climbs, vanishes for higher earners, and carries a firm expiration date. For retirees weighing how much to draw from savings each year, the fine print decides whether the deduction is worth thousands or nothing at all.
How the $6,000 Senior Deduction Works
The provision comes from the One Big Beautiful Bill Act and applies to tax years 2025 through 2028. According to the Internal Revenue Service, a taxpayer who turns 65 on or before the last day of the tax year may claim an additional $6,000 deduction, or $12,000 for a married couple when both spouses qualify. The break is available whether a filer itemizes or takes the standard deduction, and it sits on top of the extra standard deduction seniors already receive.
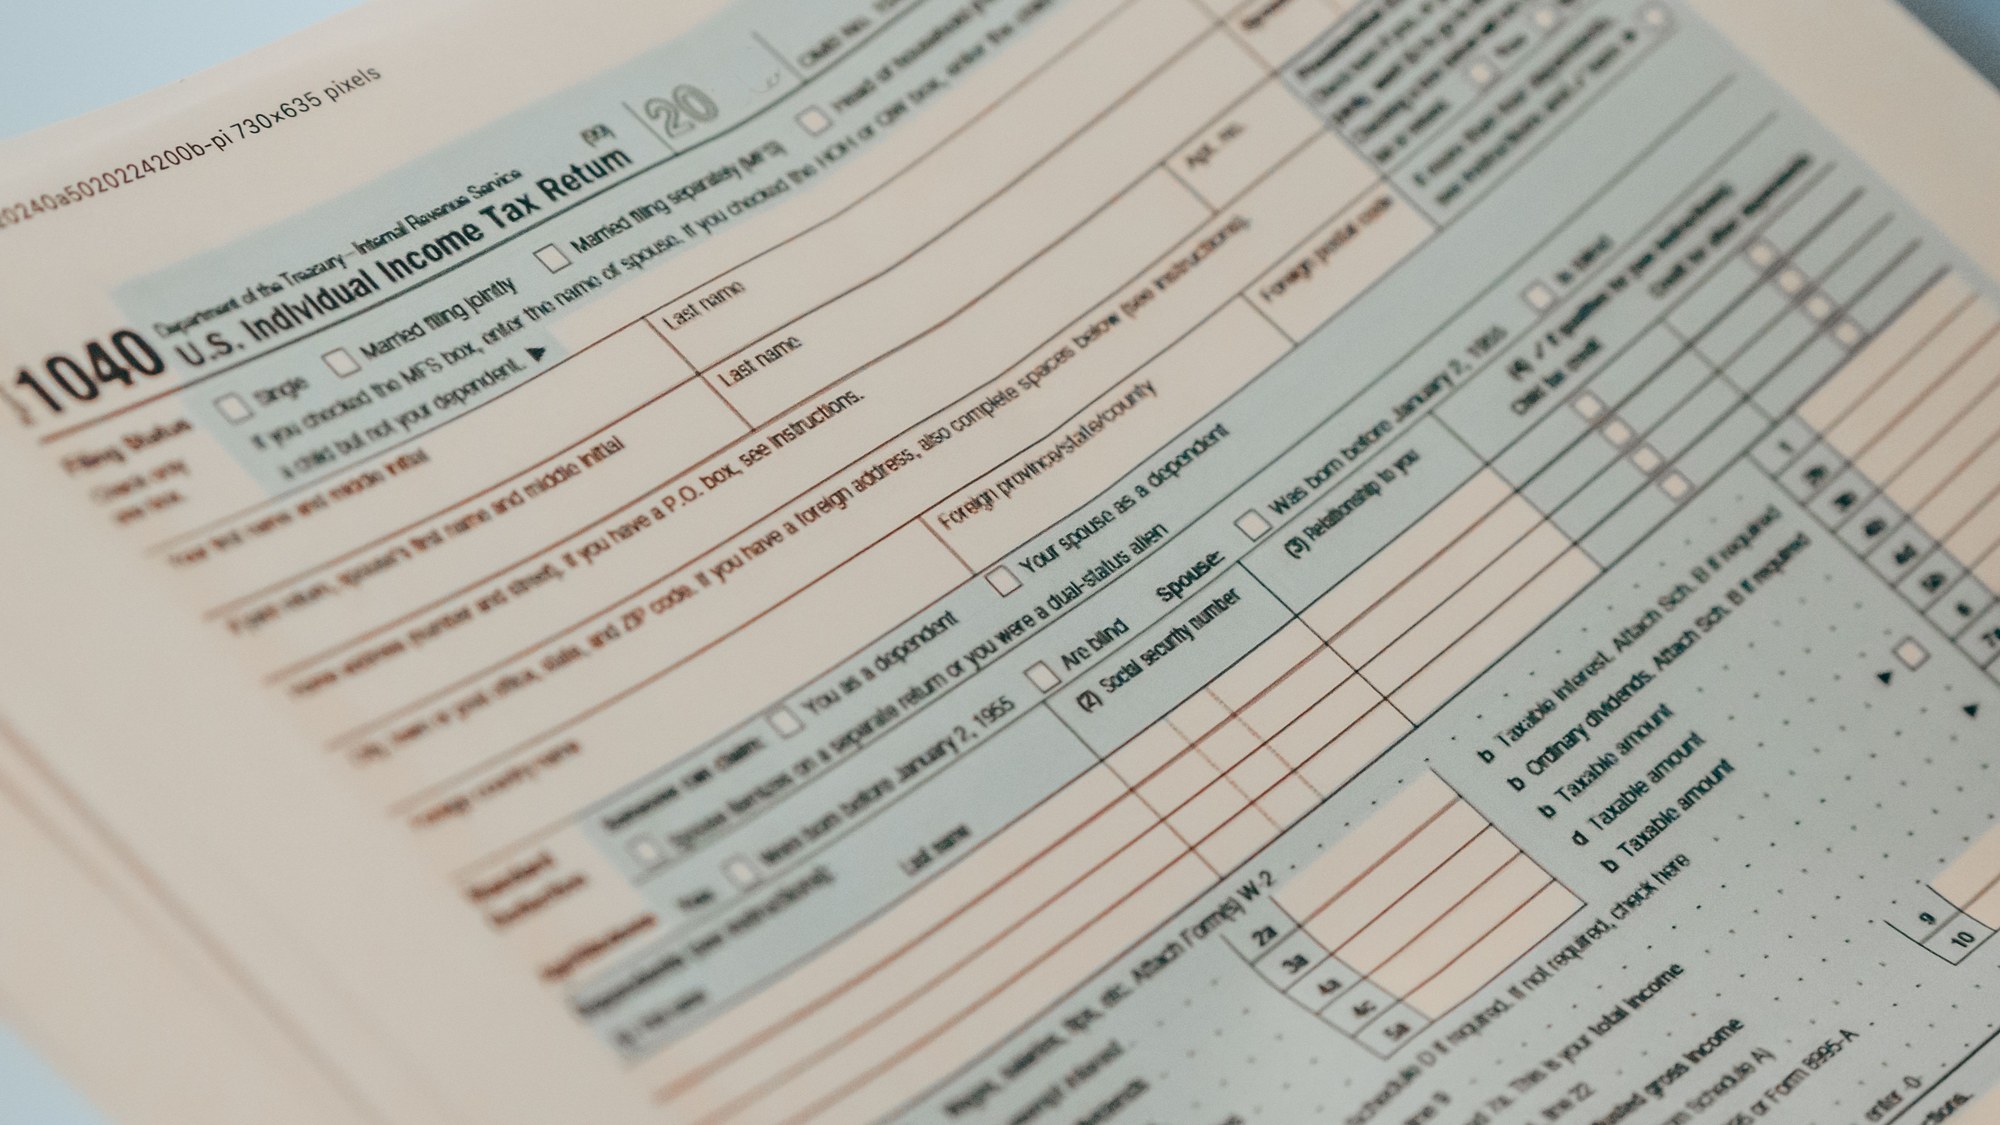
The deduction is claimed on a new Schedule 1-A attached to Form 1040. It does not eliminate tax on Social Security benefits, a point that has drawn confusion since the law passed. It simply lowers taxable income for those who qualify, which for many older households produces the same practical result on part of their benefits.
Free retirement updates: Miss an enrollment or claim deadline and it may be gone. Our free Retirement Shield newsletter keeps readers ahead of the ones that matter. Get the free newsletter.
Where the Income Phase-Out Begins
The full amount reaches only retirees with modified adjusted gross income at or below $75,000 for a single filer and $150,000 for a married couple filing jointly. The IRS explains in its Working Families Tax Cuts guidance that above those thresholds the deduction shrinks rather than ending abruptly. It is reduced by 6 cents for every dollar of income over the threshold, so the $6,000 runs out completely at $175,000 of modified adjusted gross income for a single filer and the $12,000 disappears at $250,000 for a couple.
The arithmetic matters at the margins. A single retiree with $95,000 of modified adjusted gross income sits $20,000 over the $75,000 line, loses $1,200 of the deduction to the 6 percent reduction, and keeps $4,800. A retiree who lets that same income reach $175,000 keeps nothing. Because the reduction tracks total income rather than any single source, a modest change in withdrawals near the threshold moves the deduction dollar for dollar.
Why Retirement Withdrawals Can Trigger the Cliff
Modified adjusted gross income includes withdrawals from traditional retirement accounts, required minimum distributions, and the taxable portion of Social Security. A one-time IRA distribution to cover a new roof or a Roth conversion done in a single year can push a household past $75,000 and begin eroding the deduction. A couple that pulls an extra $40,000 from a traditional 401(k) in one year to buy a car, for example, adds that full amount to modified adjusted gross income and surrenders $2,400 of the $12,000 break in the process. Spreading larger withdrawals across more than one tax year, drawing from a Roth balance that does not count toward the income figure, or timing a distribution before a spouse reaches 65 can keep more of the deduction intact.
It Stacks on the Existing Senior Standard Deduction
The new $6,000 break does not replace the additional standard deduction that filers 65 and older already receive. According to the Internal Revenue Service, the deduction is available whether a taxpayer itemizes or takes the standard deduction, and it is claimed in addition to the regular and age-based standard deductions rather than in place of them. A qualifying single retiree who takes the standard deduction therefore layers the ordinary standard amount, the extra senior standard deduction, and the new $6,000 on top of one another. Each spouse who has reached 65 claims a separate $6,000, so a married couple where both qualify subtracts $12,000 before the couple’s other deductions are counted. Filers must include a Social Security number to claim it, and married taxpayers generally must file jointly to take the deduction at all.
The 2028 Sunset
The deduction is temporary. Unless Congress acts to extend it, the additional $6,000 disappears after the 2028 tax year and older filers return to the prior standard deduction rules. The Schedule 1-A instructions confirm the four-year window, which means the planning value is front-loaded: the years to capture it are 2025 through 2028, and a retiree whose income drifts above the phase-out during that stretch forfeits it for good on those returns.
What Qualifying Retirees Should Confirm
Eligibility turns on age at year-end and on income, not on employment status, so a fully retired 68-year-old with modest withdrawals is squarely within the target group. The deduction applies per qualifying individual, meaning a couple where only one spouse has reached 65 claims $6,000 rather than $12,000 until the second spouse crosses the age line. For households near the threshold, the size of each year’s retirement-account draw is the single lever that decides how much of the deduction survives.
This article was produced with AI assistance and reviewed by The Financial Wire editorial team.
More Financial Reading
- What really happens to your joint savings account when you die?
- How many CDs can you park at 1 bank? FDIC rules you must know