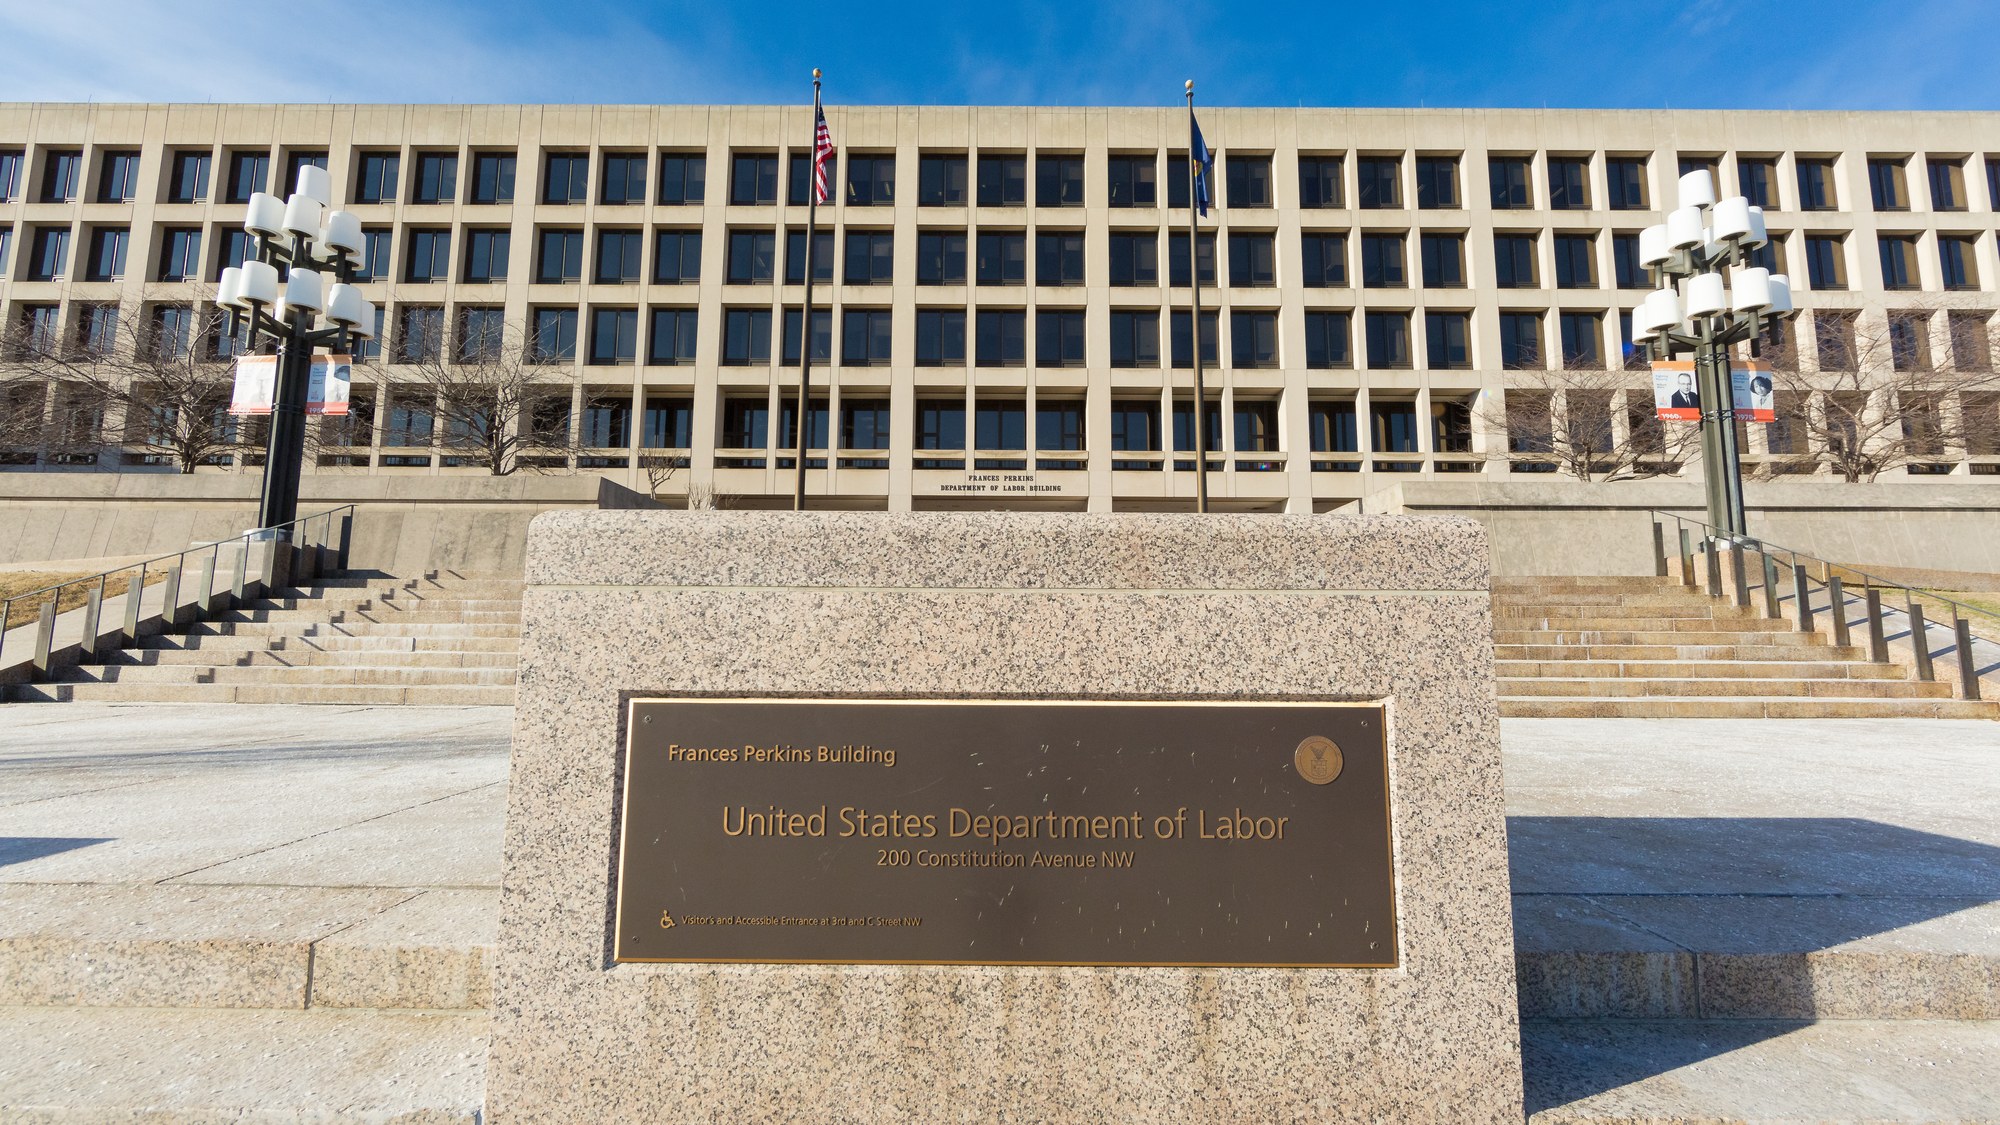
When a single-employer pension plan fails and the Pension Benefit Guaranty Corporation (PBGC) takes over as trustee, a retiree who starts benefits at age 65 in 2026 is guaranteed at most $7,010.79 a month if the pension carries a joint-and-50% survivor benefit. The same retiree with a straight-life annuity, which ends at death, is guaranteed up to $7,789.77. Those figures come from the most recent year on PBGC’s maximum-guarantee table, which was last updated on Oct. 30, 2025.
What the $7,010.79 ceiling covers
PBGC’s maximum monthly guarantee page, read on Sept. 30, states that the maximum guarantees in its tables “apply only to single-employer pension plans whose benefits PBGC pays as trustee.” The figure is a ceiling on what the agency will pay, and it does not describe what a typical retiree receives. A pension smaller than the ceiling is not affected by it at all.
No 2027 table has been posted, so no 2027 maximum exists to quote. The 2026 numbers are the most recent year shown, and any later figure would be a projection that PBGC has not published.
What a survivor benefit costs against a straight-life annuity
At age 65 the two 2026 maximums are $7,789.77 for a straight-life annuity and $7,010.79 for a joint-and-50% survivor annuity. The survivor form pays $778.98 less each month, or 90% of the straight-life amount, and in return the surviving spouse continues to receive half of the retiree’s amount after death. PBGC’s methodology note says that survivor elections produce lower monthly amounts than straight-life options.
Over a year the difference is larger in absolute terms: $7,010.79 a month comes to $84,129.48 annually, against $93,477.24 for the straight-life maximum. The same 90% relationship holds at the other ages in the table, so a survivor election at age 62 lowers the ceiling from $6,153.92 to $5,538.53 a month.
The guarantee therefore follows the way the pension was elected. A retiree who chose a survivor form is measured against the lower column, even though the plan’s own formula may have produced a different monthly amount before the plan failed.
How the ceiling moves with the age benefits begin
The 2026 table gives lower amounts to younger starting ages and higher ones to older ages. PBGC explains that younger people are expected to receive more monthly pension checks over their lifetimes. The straight-life and joint-and-50% survivor maximums for selected ages are:
- Age 62: $6,153.92 straight-life, $5,538.53 with survivor.
- Age 65: $7,789.77 straight-life, $7,010.79 with survivor.
- Age 66: $8,568.75 straight-life, $7,711.88 with survivor.
- Age 67: $9,425.62 straight-life, $8,483.06 with survivor.
- Age 70: $12,931.02 straight-life, $11,637.92 with survivor.
A retiree who begins collecting at 62 is thus capped $1,635.85 a month below the age-65 straight-life ceiling.
The steepness of the schedule stands out at the far end. The straight-life ceiling at 70, $12,931.02, is more than twice the $6,153.92 ceiling at 62, and each added year between 65 and 70 raises the cap by more than the year before: $779 from 65 to 66, $857 from 66 to 67, and more than $1,000 in each later step shown. Every figure in that comparison is taken from the same 2026 table, so none of it mixes plan years.
Limits that apply before the ceiling is reached
The dollar table is only one of several limits. On its guaranteed benefits page, PBGC says the maximum is set each year under provisions of the Employee Retirement Income Security Act, and that the monthly benefit generally cannot exceed what the plan would have provided at normal retirement age. Plans amended within five years before termination may face reduced guarantees, higher limits apply for disabled participants and airline-industry plans carry special limits.
PBGC guarantees “basic benefits” earned before termination, including pension benefits at normal retirement age, most early retirement benefits and annuity benefits for survivors. Health and welfare benefits, vacation pay and severance are not guaranteed.
Multiemployer plans follow separate rules
The $7,010.79 ceiling does not apply to multiemployer plans, which PBGC administers under a separate insurance program with its own guarantee levels. PBGC’s Special Financial Assistance page covers the aid program for those plans, and it does not publish totals, plan counts or participant counts. The single-employer table therefore should not be used to estimate a multiemployer retiree’s protection.
Taxes on a PBGC-paid pension
The guaranteed figures are gross amounts, and pension income generally carries federal tax. IRS Topic 410 says pension and annuity payments are fully taxable when the recipient made no after-tax contributions, with only the portion above the investment in the contract taxable when after-tax contributions were made. The taxable part is generally subject to withholding, adjustable with Form W-4P, so the net amount received falls below the guaranteed gross figure.
On its press page, PBGC describes its programs as protecting approximately 30 million workers and retirees, and the maximum-guarantee table, with its Oct. 30, 2025 update date, remains the record for the 2026 dollar limits.
Planning taxes on pension income in retirement
Retirees who rely on a pension for part of their income often find that the pension, Social Security and account withdrawals all count toward the same tax calculation. The practical problem is deciding which accounts to draw from, and in what order, without pushing more Social Security into taxable income.
The Retirement Tax & Withdrawal Planner is a 12-page planner with four calculators (provisional income, IRMAA tier, RMD schedule and Roth bracket fill) and an account withdrawal order that a reader can use to compare withdrawal sequences.
Download The Retirement Tax & Withdrawal Planner to compare withdrawal orders →
This article was produced with AI assistance and checked against the primary sources linked above.