Executive Order 14438, signed Oct. 22, 2026, tells the Federal Housing Finance Agency to run a pilot that would cancel mortgage insurance for borrowers without being asked, but only “if he determines that it is in the best interests” of Fannie Mae, Freddie Mac, the agency and the public. The same order directs the Agriculture and Veterans Affairs secretaries to cut interest rates on the single-family loans they make directly. It sets no start date for the pilot and no rate for the loans.
The text of the order, titled “Decreasing Housing Costs for the American People,” is full of conditions. The FHFA director decides whether the pilot goes ahead, and the loan-rate cuts must be consistent with applicable law and available appropriations. A final section says the order creates no enforceable rights for any party.
Anyone who pays mortgage insurance today, or who plans to buy with a small down payment, needs to know that this order does not change a bill yet. The pilot would cover only mortgages made after it is established, so existing loans are outside it by the order’s own terms. A borrower who wants mortgage insurance dropped should keep working with the loan servicer, because nothing in the order tells servicers to start.
Retirement deadlines, in your inbox: Miss an enrollment or claim deadline and the money can be gone. Join the Retirement Money Brief and we’ll send you our Property Tax & Utility Relief Finder as a welcome gift.
Get the Brief + the relief finder →
We may earn a commission from links on this page.
The mortgage insurance pilot waits on the FHFA director
Section 2 says the FHFA director “shall, if he determines” the pilot serves those interests, direct it. The pilot would periodically review loans, using automated valuation models and other data, to identify borrowers who may qualify to have mortgage insurance cancelled. Cancellation would be proactive when the borrower meets the equity requirements, when it is consistent with safety and soundness and contractual obligations, and when every other requirement is met.
Servicers would have to notify borrowers promptly, “to the extent permitted by law and operationally feasible,” and cut unnecessary paperwork and appraisal costs. That is a test of a process, not a new rule that wipes out premiums. The order names no deadline, and it does not say how many borrowers would be reviewed.
Refinances and title insurance carry the same kind of “if”
Section 4 works the same way. If the director decides it serves the public and fits safety and soundness, the existing title acceptance pilot would grow into a nationwide program. Fannie Mae or Freddie Mac could then accept an automated title review in place of a lender’s title insurance policy on eligible refinances.
The director would have to consider letting refinances go above the current 80 percent loan-to-value limit when title risk is low, and waiving appraisals and income checks on limited cash-out refinances that lower a borrower’s monthly payment. He would also weigh trimming loan-level price adjustments and other fees on those refinances. Any savings must be passed to borrowers, and lenders must tell borrowers about them.
USDA and VA direct loan rates depend on appropriations
Section 5 is not left to an agency head’s judgment the way the FHFA pilots are. The Agriculture and Veterans Affairs secretaries “shall reduce” interest rates on single-family loans they make directly, citing 42 U.S.C. 1490a(a)(1)(B) for USDA and 38 U.S.C. 3762(c)(1) for VA. The cut has to be consistent with applicable law and “available appropriations.”
That language is why the headline fact is “where money allows.” The order names no new rate and no date. It covers loans the two departments make directly, and Section 6 repeats that everything is subject to the availability of appropriations.
Manufactured housing gets a task force, not a rule
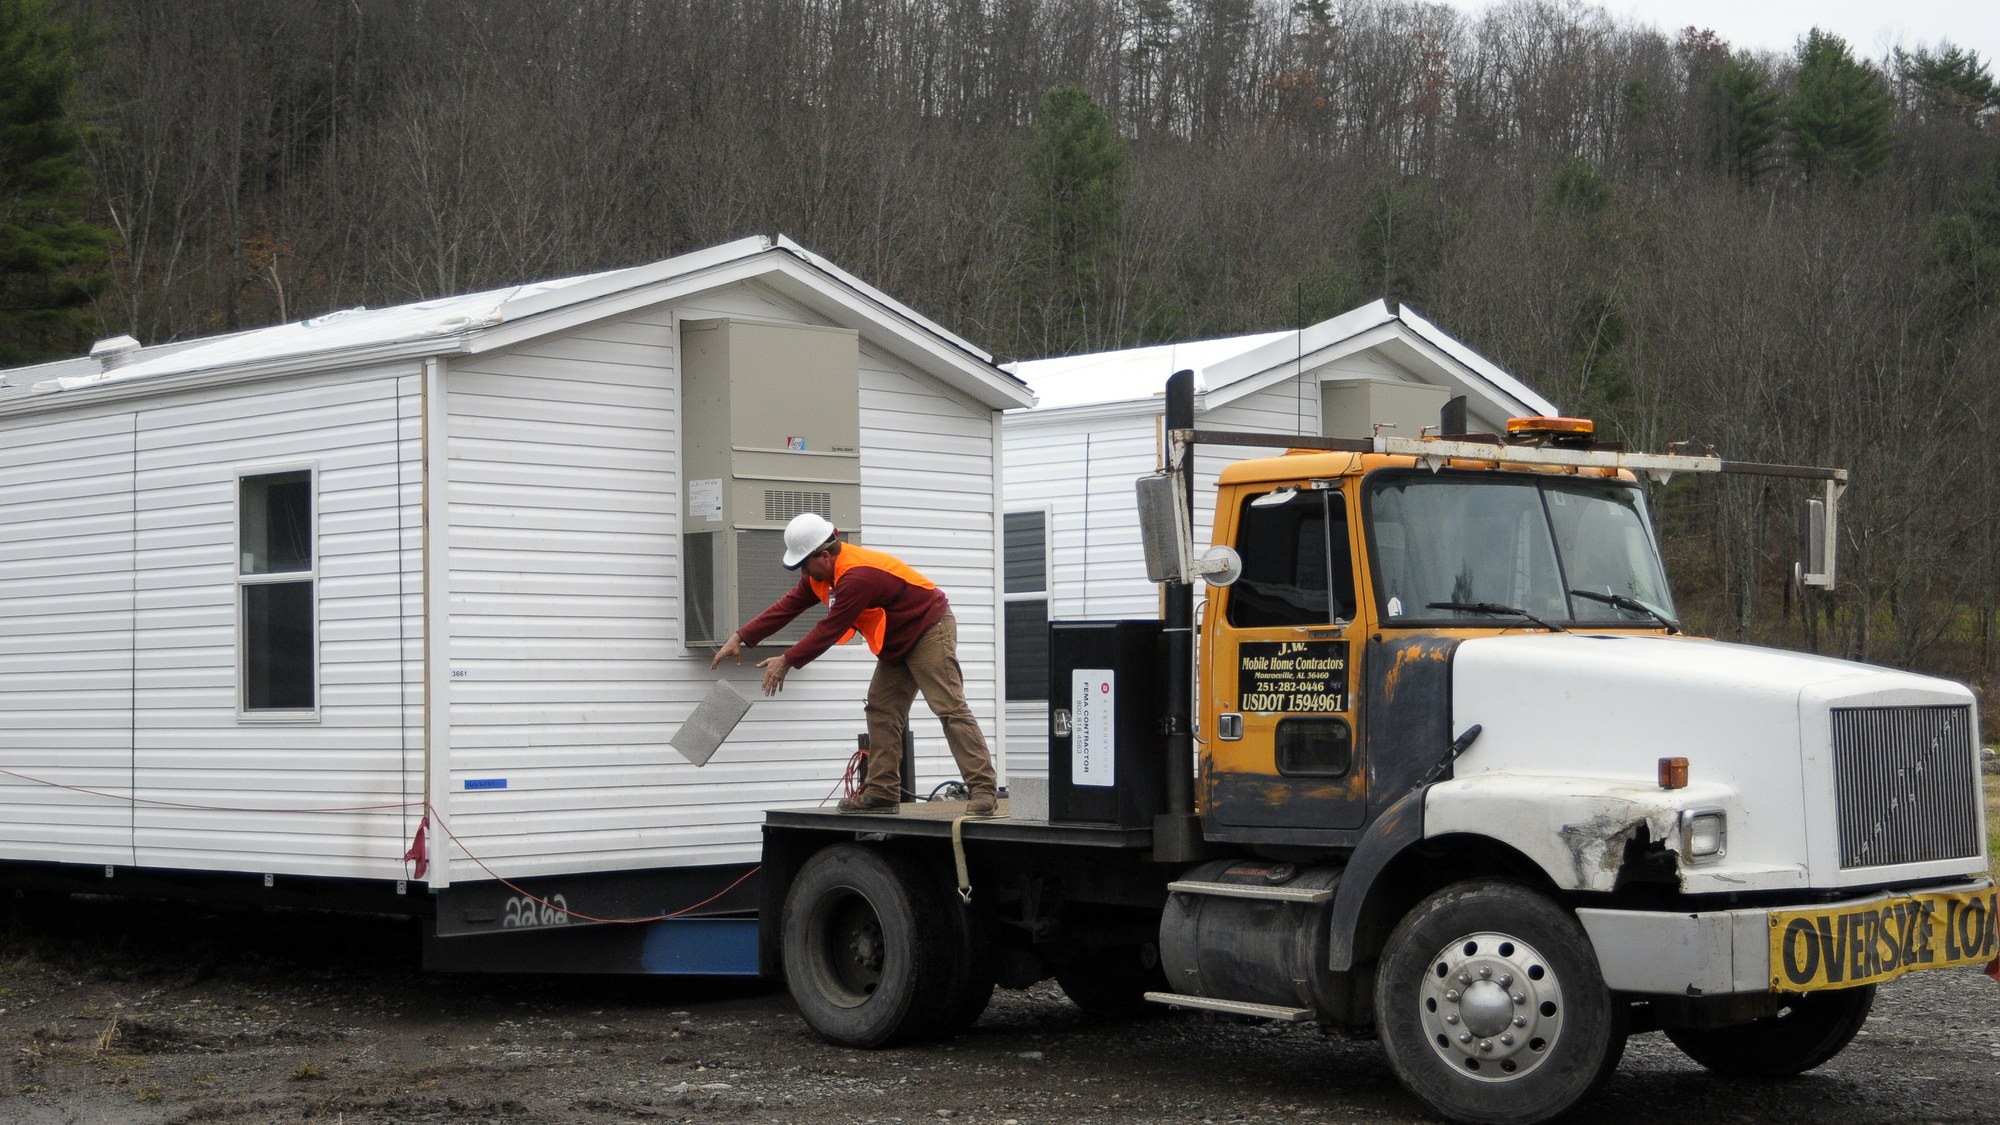
Section 3 creates a Task Force on Manufactured Housing Innovation, co-chaired by the Housing and Urban Development secretary and the FHFA director, with the Agriculture, Commerce and Veterans Affairs secretaries. It has 180 days to give the President recommendations. They cover design specifications and certifications, recognizing approvals across jurisdictions, removing duplicate reviews and using federal financing tools.
The task force is also to look at whether federal grant money could be conditioned on, or used to encourage, standardized state and local permitting. The 180-day deadline is the only one in the whole order, and it applies to the recommendations, not to any change a buyer would feel.
Will the FHFA director start the mortgage insurance pilot?
The order leaves that decision to him.
A pilot that may never start is not a plan for a monthly housing bill. Homeowners can control the costs that sit in their own paperwork, and those costs are the ones that stay no matter what an order says.
“Cut Your House Costs” is an 11-page guide to ten moves for spending less on a house and protecting its value, including the home-cost audit worksheet and home equity options compared, from a HELOC to a reverse mortgage. It also covers mistakes on a property card that raise a home’s value every year.
Run the home-cost audit worksheet from Cut Your House Costs on what the house costs now →
This article was produced with AI assistance and edited for accuracy against the sources linked above.