Catching fraud early is often the difference between a minor annoyance and a financial ordeal, and one of the best early-warning tools is free. Every consumer can review their credit reports from all three major bureaus at no cost, and the reports are now available far more frequently than most people realize. Checking them regularly is a simple habit that spots identity theft before it spreads.
The official free source
The one federally authorized site for free credit reports is AnnualCreditReport.com, which provides reports from the three nationwide credit bureaus. It is the source established under federal law, and it does not require a purchase, a subscription, or a credit-card number. The Federal Trade Commission’s guidance on free credit reports confirms this is the official place to obtain them and cautions against imitator sites that charge fees or push paid products.
What changed in recent years is the frequency. For a long time the law guaranteed one free report from each bureau per year, but the bureaus have made free reports available weekly through the official site. The Consumer Financial Protection Bureau’s explanation of how to get credit reports reflects that consumers can now check far more often than the old annual cadence, which makes ongoing monitoring practical without paying for a service.
Because a person has three reports, from three bureaus, a useful strategy is to space them out, checking one bureau’s report at a time across the year, or to pull all three together periodically for a full picture. Either approach keeps a regular eye on the file.
Free for readers: Scam calls targeting retirees change every week. The free Retirement Shield newsletter flags the ones going around and the one tell that stops each. Sign up free.
What to look for
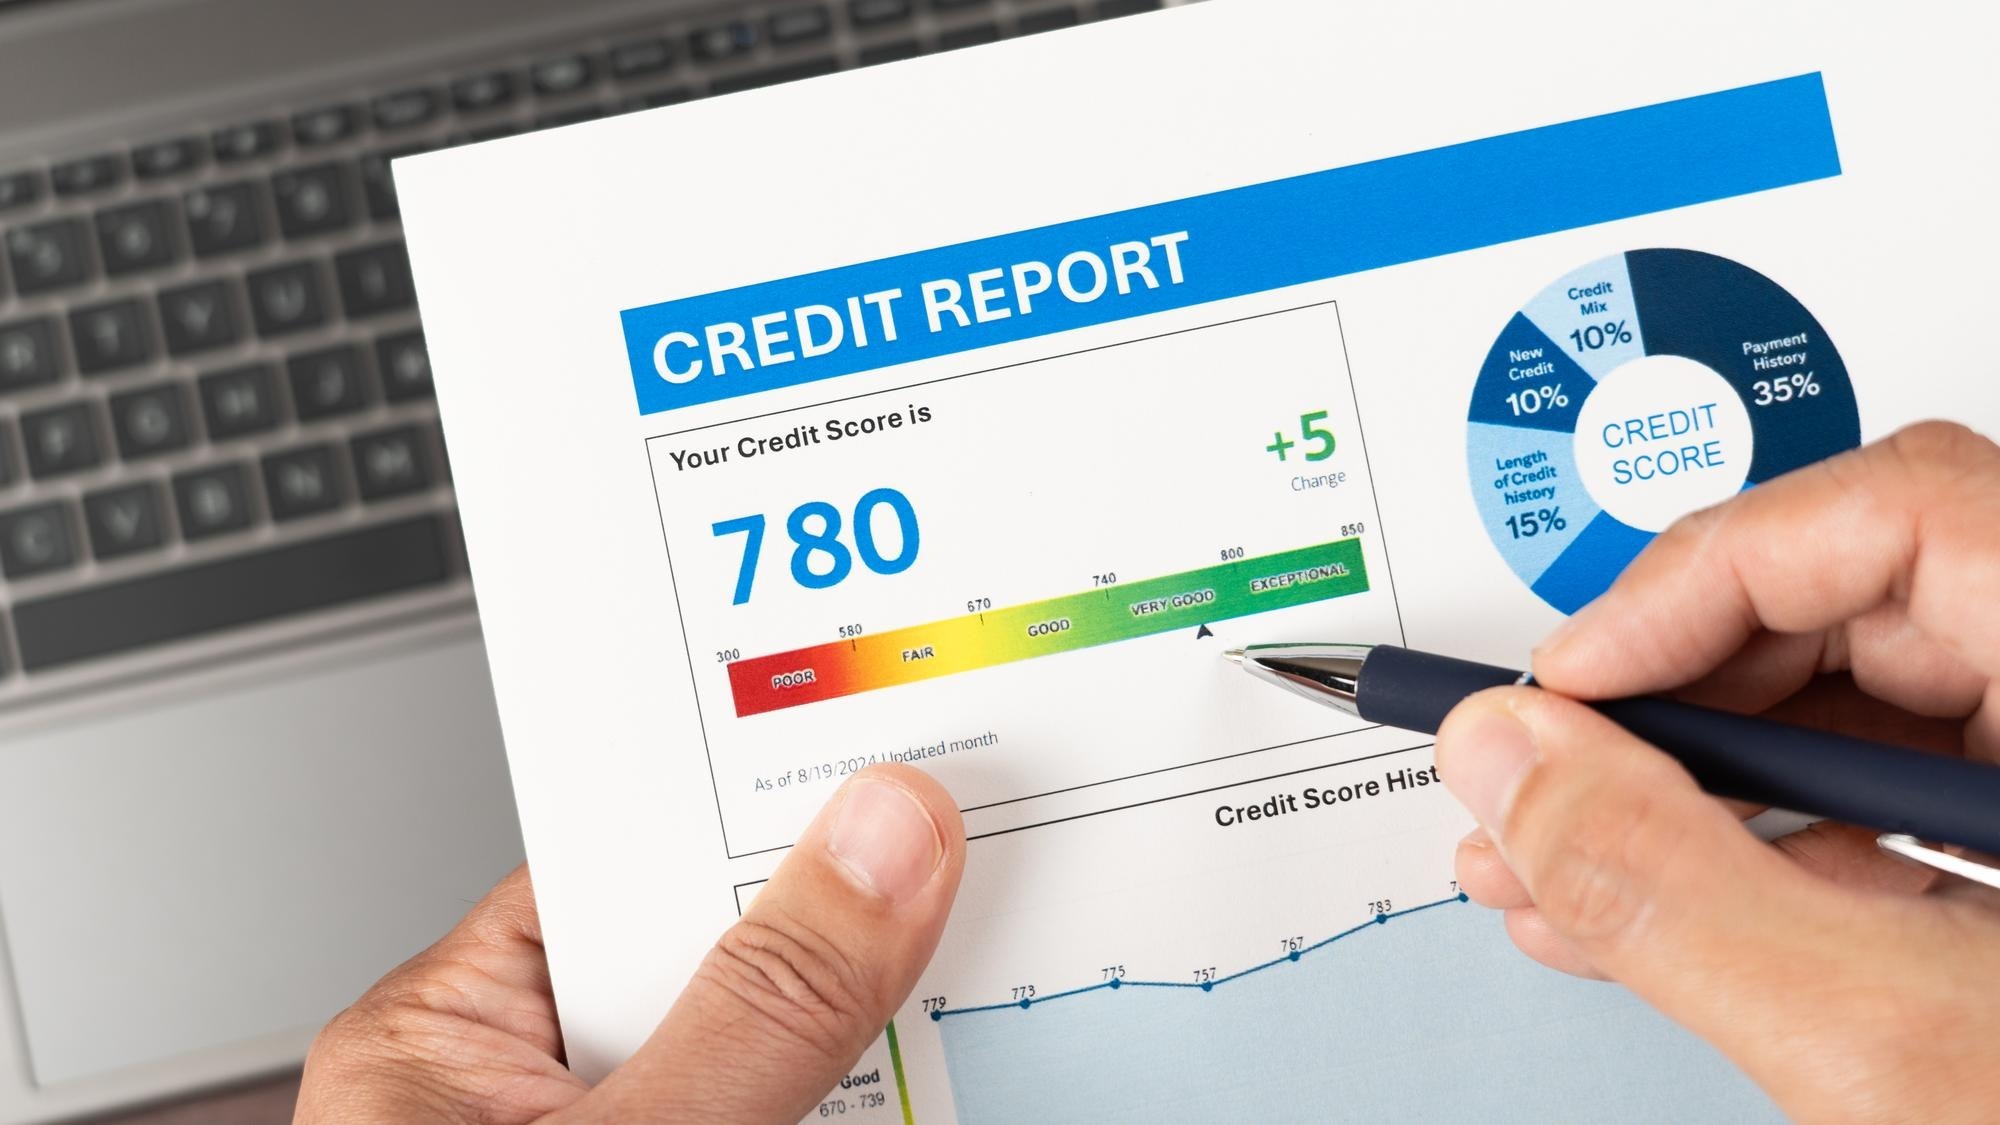
A credit report lists the accounts open in a person’s name, along with balances, payment history, and recent inquiries from lenders. Reviewing it, the most important thing to watch for is anything unfamiliar: an account the person never opened, an address they do not recognize, or an inquiry from a lender they never contacted. Any of these can be the first sign that someone is using stolen information to open credit in their name.
Errors that are not fraud also matter, since inaccuracies can drag down a credit score and affect the rates a person is offered on loans or insurance. A wrongly reported late payment, an account that is not theirs, or a balance that is incorrect can all be disputed with the bureau, which is required to investigate. Catching these mistakes protects both against fraud and against paying more because of a flawed record.
Acting on what the report shows
Finding a problem is only useful if it leads to action. When a report reveals a fraudulent account or a suspicious inquiry, the next steps are to dispute the item with the credit bureau, contact the lender involved, and consider placing a fraud alert or a credit freeze to block further misuse. A credit freeze, which is free, prevents new creditors from accessing the report, stopping most attempts to open accounts in the person’s name.
For errors, the dispute process is straightforward and can be done online, by mail, or by phone. Documenting the problem and following up ensures the bureau completes its investigation and corrects the record. Regular review means these issues surface early, when they are easiest to resolve, rather than months later after damage has accumulated.
Building the habit
The value of free weekly reports is realized only by using them. Setting a recurring reminder to check a report, whether rotating through the three bureaus or reviewing all three at intervals, turns credit monitoring into a routine rather than an afterthought. Because the official site is free and requires no payment, there is no cost barrier to making it a regular practice.
For older adults, who are frequent targets of identity theft, this ongoing check is one of the most effective and least expensive defenses available. Reviewing the reports from the official government-authorized site, watching for unfamiliar accounts and inquiries, and acting quickly on anything suspicious gives a retiree an early-warning system against fraud, and a way to keep their credit record accurate, at no cost at all.
Pairing reports with a credit freeze
Monitoring reports catches fraud after it appears, but pairing that habit with a credit freeze prevents much of it from happening in the first place. A freeze restricts access to a credit report, which blocks new creditors from opening accounts in a person’s name, stopping most attempts at new-account fraud before they start. The freeze is free, does not affect a person’s credit score, and can be lifted temporarily whenever the individual legitimately wants to apply for credit.
Together, the two tools form a strong defense: the freeze prevents new fraudulent accounts, while regular report reviews catch any activity that slips through or involves existing accounts. Many people who have been targeted by identity theft use both, and there is no reason to wait for a problem to put them in place.
Making review a routine
The value of free weekly reports is realized only by actually using them. Setting a recurring reminder, whether to rotate through the three bureaus across the year or to review all three at intervals, turns credit monitoring into a habit rather than an afterthought. Because the reports come from the official government-authorized source at AnnualCreditReport.com at no cost, there is no financial barrier to checking often. For older adults, who are frequent targets of identity theft, this ongoing review is one of the most effective and least expensive defenses available, spotting unfamiliar accounts and inquiries early, when they are easiest to resolve, and keeping the credit record accurate so a flawed entry does not quietly raise the cost of borrowing or insurance. Making the review a recurring habit, and pairing it with a free credit freeze, gives a retiree a strong, no-cost early-warning system against the identity theft that so often targets older adults.
Free for readers: Want plain-English help keeping more of your money in retirement? The free Retirement Shield newsletter covers scams, benefits, and money you’re owed, a couple times a week. Subscribe free.
This article was researched and drafted with AI assistance and reviewed against the linked primary sources.