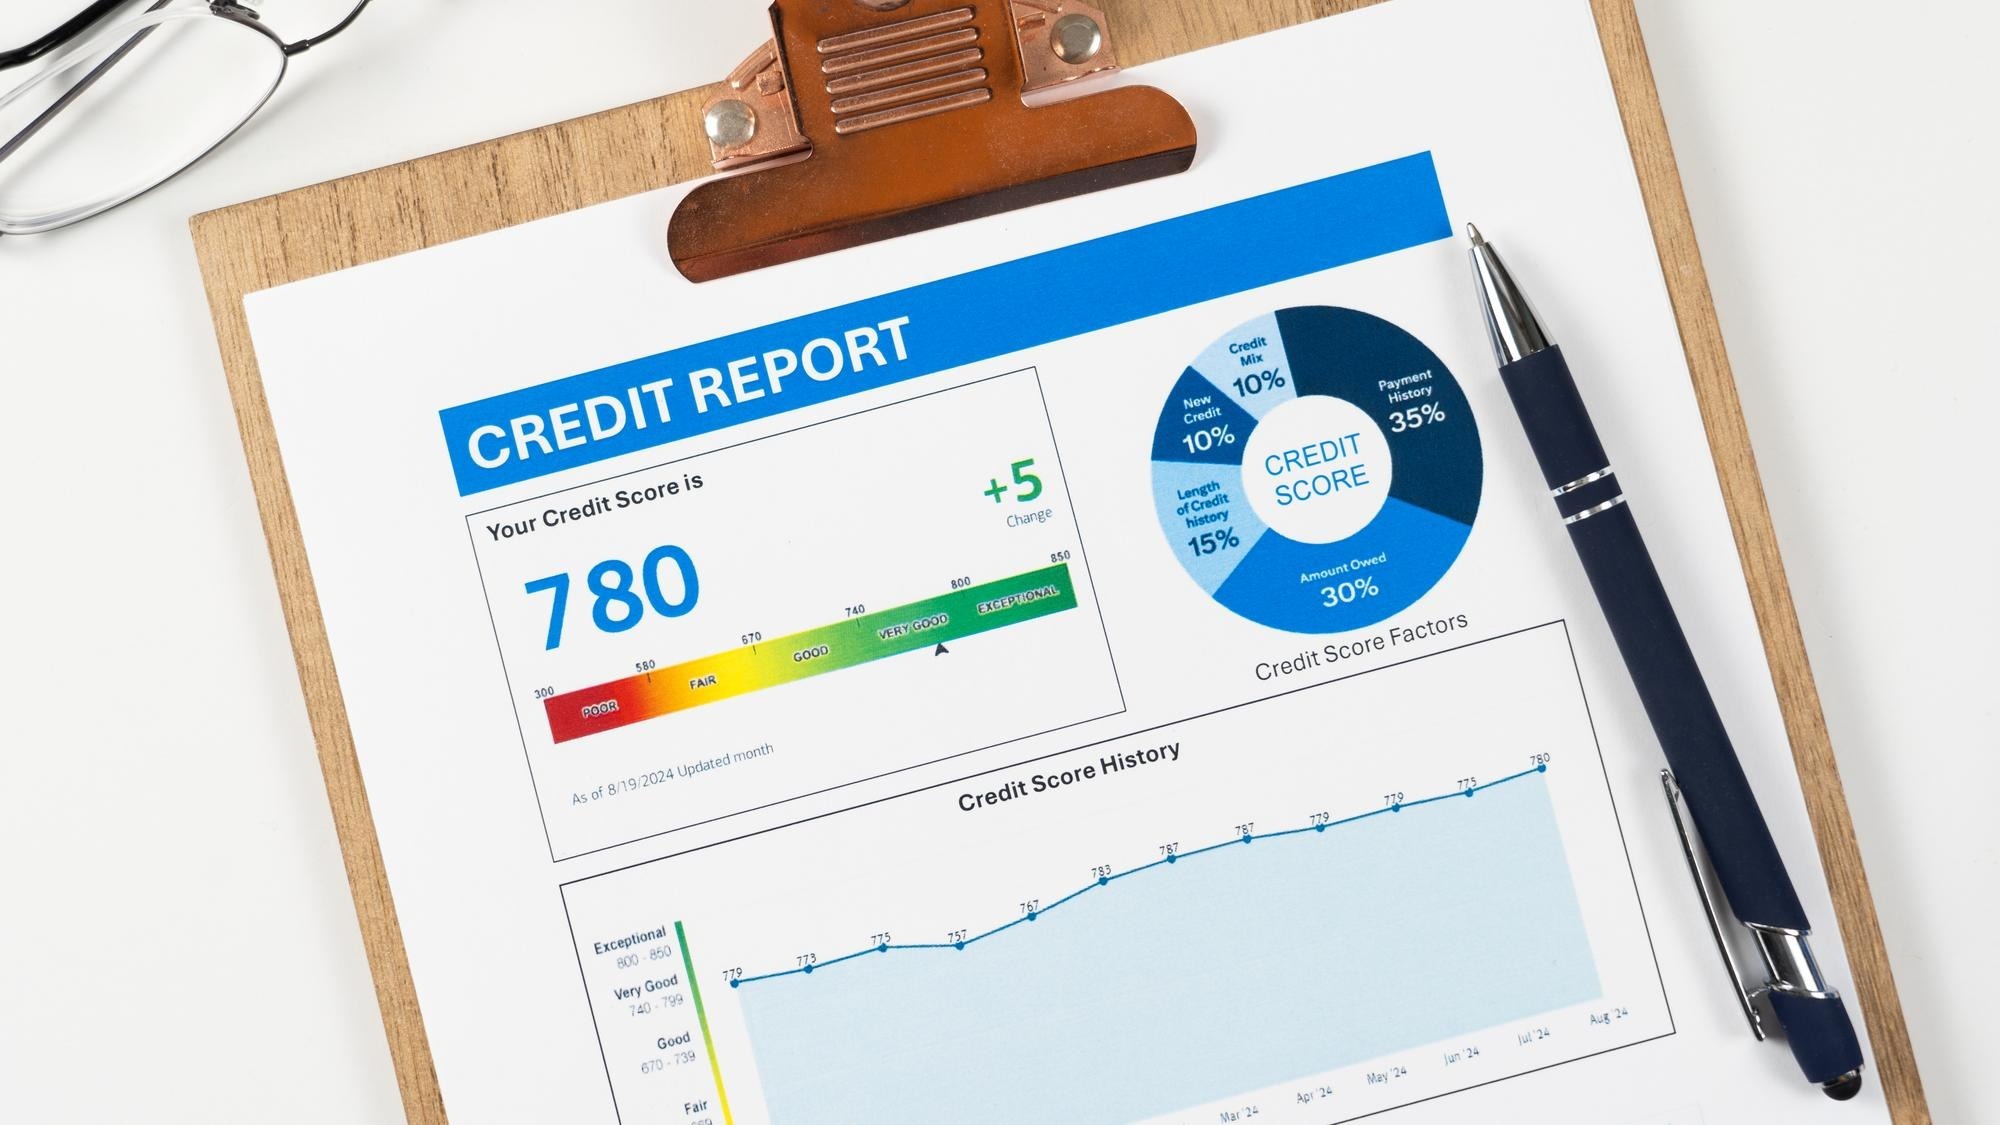
Identity theft rarely announces itself. A thief who opens a credit card or a loan in someone else’s name leaves no ring at the doorbell, and the victim often learns of the damage only weeks later, when a collection notice arrives or a mortgage application is denied. There is a free, standing tool built precisely to shorten that blind window, and older Americans are among those who benefit most from using it on a regular schedule.
What changed, and why weekly access matters
For most of the past two decades, federal law entitled every consumer to one free credit report a year from each of the three nationwide bureaus, Equifax, Experian, and TransUnion. That annual cadence left long stretches during which fraud could grow unseen. In 2020 the bureaus began offering free reports every week as a temporary measure, and after two extensions they made weekly access permanent in 2023.
The practical effect is a monitoring rhythm that no longer costs anything. A person can check one bureau this week, another next week, and the third after that, then start the cycle again, effectively watching the credit file on a near-continuous basis at no charge. For a retiree living on a fixed income, catching a fraudulent account in days rather than months can be the difference between a phone call and a financial crisis.
Access runs through a single site. The only federally authorized source for these free reports is AnnualCreditReport.com, the portal the three bureaus jointly operate. Other sites that advertise “free” reports often attach a paid subscription or exist to harvest personal data, which makes using the official address a security step in its own right.
Free retirement updates: Scam calls targeting retirees change every week. Our free Retirement Shield newsletter flags the ones going around and the one tell that stops each. Sign up free.
What a report reveals that a bank statement cannot
A credit report is a different instrument from a bank statement, and that difference is the point. A checking account shows money that has already moved. A credit report shows accounts opened in a person’s name, including ones the person never authorized, along with the companies that have recently requested that credit file.
Reading the report, a retiree should look for accounts that do not belong to them, credit inquiries from lenders they never approached, addresses they have never lived at, and balances or amounts that do not match memory. Any of those can be the first visible sign that stolen personal information is being used to borrow. Because new fraudulent accounts surface on the report before the bills come due, the report is an early-warning system rather than a receipt of damage already done.
The Federal Trade Commission’s guidance on free reports walks through how to read each section and what to do about entries that look wrong, from disputing errors with the bureau to placing added protections when fraud is confirmed.
Turning a free right into a routine
The value of weekly access is realized only when it becomes a habit. Staggering the three bureaus across the calendar, rather than pulling all three on the same day, spreads the coverage so that something suspicious rarely goes unspotted for long. A simple recurring reminder, one bureau every few weeks, converts a one-time curiosity into ongoing surveillance.
Requesting a report is deliberately low-friction and does no harm to a credit score, because a consumer checking their own file is not the kind of inquiry lenders weigh. Reports can be pulled online for immediate viewing, or requested by phone or mail for those who prefer not to use a computer, and the official site is the correct starting point for every method.
What monitoring can and cannot do
It is worth being clear about the tool’s limits. Regularly reading a credit report is a detection measure: it reveals fraud that has already been attempted so it can be stopped and disputed quickly. It does not, on its own, prevent a thief from trying to open an account in the first place. That preventive job belongs to other steps, and the two approaches work best in tandem, with monitoring catching what any single barrier misses.
For older savers, the appeal is the ratio of effort to protection. A few minutes every couple of weeks, at no cost and with no downside to a credit score, keeps a running watch over the most important record of a person’s borrowing identity. Fraud thrives on delay, and a weekly report is the cheapest way to take the delay away.
The report is not the score, and other limits
A free credit report and a credit score are not the same thing, and the distinction trips up many first-time users. The report is the detailed record of accounts, balances, payment history, and inquiries; the three-digit score is a separate calculation derived from that record, and the federally authorized free report does not necessarily include it. For spotting fraud, the report is the document that matters, because a bogus account or an unfamiliar inquiry surfaces there long before it would ever move a score.
Retrieving the report also asks the requester to confirm their identity, sometimes by answering questions only the real person would be able to answer, which is a safeguard rather than an obstacle. And when a report turns up an entry that looks wrong, the reader’s next move is to dispute it with the bureau that issued the report, which is then obligated to investigate the claim. Reading regularly is only the detection half of the job; disputing what surfaces is how the monitoring turns into a fix, and the two together are what keep a stray fraudulent line from hardening into lasting damage.
This article was researched and drafted with AI assistance and reviewed against the linked primary sources.
More Financial Reading
- Adding someone to your bank account: tax traps and smart moves
- The ideal retirement withdrawal rate so your savings actually last


