A Treasury watchdog review found that roughly 67,000 tax returns filed for tax years 2023 and 2024 claimed the Earned Income Tax Credit while listing a Social Security number issued for a non-work purpose. Those returns claimed nearly $219 million in credits combined, and the IRS paid out close to $213 million of that before the review was completed. The finding sounds like a clean case of ineligible claims slipping through, but the watchdog itself was careful to say that is not quite what the numbers show, because a non-work Social Security number does not automatically mean the person holding it was ineligible for the credit. The review sits inside a broader look at how well the IRS can verify Earned Income Tax Credit eligibility before a refund goes out, a question that matters well beyond the roughly 67,000 returns identified, since the same data gaps that made this group hard to screen apply to other EITC claims that involve a Social Security number issued under unusual circumstances.
What a Nonwork Social Security Number Is
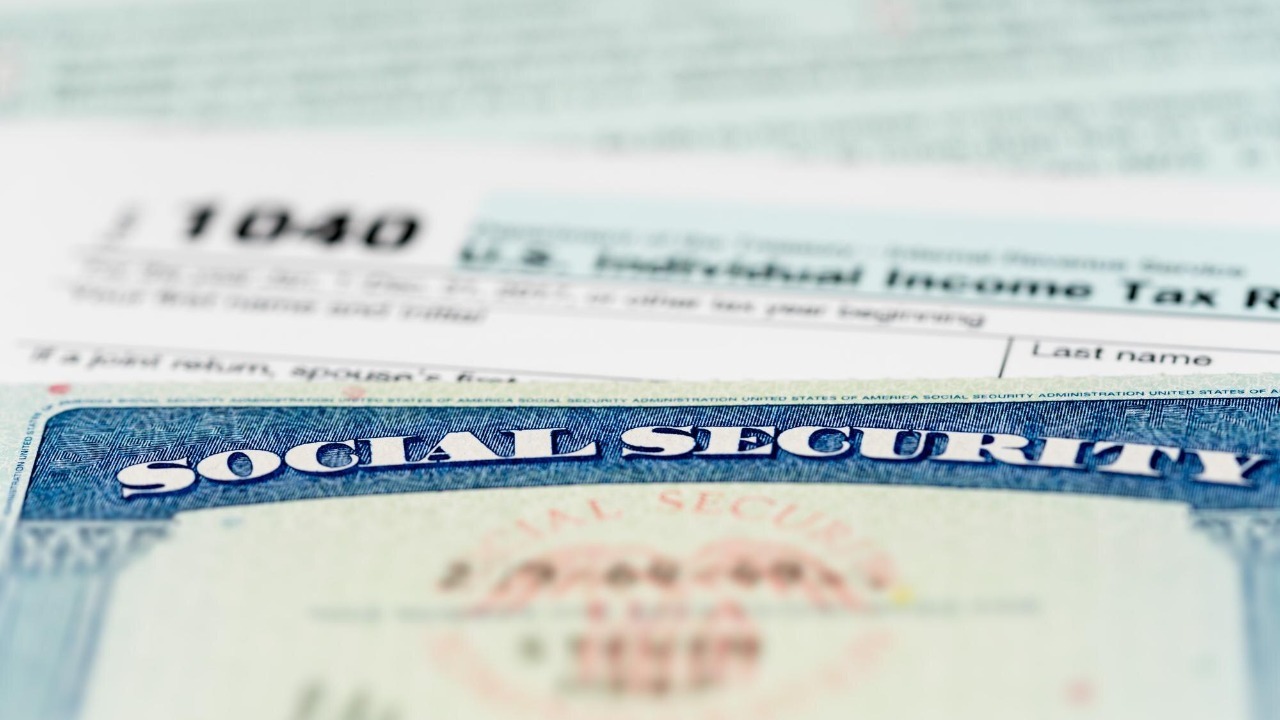
The Social Security Administration issues three types of Social Security cards. One allows unrestricted work, one is valid for work only with Department of Homeland Security authorization, and the third is marked “NOT VALID FOR EMPLOYMENT,” issued to people who are lawfully in the country without work authorization but need a number for a valid non-work reason, including situations where federal law requires a Social Security number to receive a specific benefit or service. That last category is what TIGTA reviewed: returns where the filer, a spouse, or a claimed qualifying child held one of these nonwork numbers while the return still claimed the EITC. The Social Security Administration has printed the “NOT VALID FOR EMPLOYMENT” language on these cards since 1982, a change made as more people needed a Social Security number for reasons unrelated to working, including reporting requirements tied to federal benefit programs.
Why a Nonwork SSN Doesn’t Automatically Disqualify a Filer
Under current IRS rules, a Social Security number is not valid for EITC purposes only if it was issued solely so the holder could receive a federally funded benefit and it does not authorize the person to work, a standard laid out in the agency’s own EITC eligibility guidance. TIGTA noted that a nonwork number issued for a state or locally funded program, rather than a federal one, may still meet that requirement, meaning it does not automatically fail the test. A person’s status can also change after the card is issued, such as gaining work authorization or becoming a citizen, without the change necessarily being reflected in the records the IRS can see. Because of those gaps, TIGTA explicitly said it did not determine that the full $213 million paid was improper, only that the returns involved a nonwork number and therefore warranted closer scrutiny than they generally received.
Free retirement updates: Keep more of your Social Security and savings with plain-English updates on the changes, deadlines, and costly mistakes retirees miss. Subscribe free.
A Data Gap Between the IRS and Social Security
TIGTA identified the core obstacle as a gap between what the Social Security Administration knows and what it routinely shares with the IRS. The SSA records the specific reason a nonwork number was issued to a given person, but that detail is not included in the standard data file the agency sends the IRS, so the IRS can typically see that a number is marked nonwork without knowing why. Without that context, the IRS cannot reliably separate a number issued solely for a federal benefit, which would fail the EITC test, from one issued for a state program or another valid non-work reason, which might not. The report also flagged that the information available to the IRS can be outdated, since a filer’s work authorization or citizenship status can change years after a nonwork card was issued, and automated denials based on old records risk rejecting credits from people who now legally qualify. TIGTA pointed to the IRS’s existing math error authority, a tool that lets the agency correct certain claims automatically during return processing, as a possible way to deny ineligible nonwork-SSN claims before a refund is issued, but cautioned that using it safely depends on the IRS first having reliable, current data, which is the piece still missing from its data-sharing arrangement with the Social Security Administration.
The Manual Review That Caught Some of It
Absent a reliable way to screen these claims automatically, the IRS leans on a risk-based manual review process called the Automated Questionable Credit program. For the returns TIGTA examined, more than 12,600 met the program’s risk criteria for processing years 2023 and 2024, the IRS reviewed about 40 percent of them, and roughly 5,100 letters went out to filers as a result. Of the higher-risk returns that were actually reviewed, nearly 90 percent were found ineligible for the credit, protecting close to $11 million in revenue. TIGTA was explicit that the 90 percent figure applies only to that risk-selected group and should not be read as an error rate for every return tied to a nonwork Social Security number, since the reviewed returns were flagged precisely because they looked the most likely to be wrong. The watchdog made no formal recommendations in this particular report, framing it instead as documentation of a structural limit on what the IRS can verify before a refund goes out the door.
What Goes Unclaimed Each Year
Separately, verification gaps that let some tax credits go out the door incorrectly say nothing about the benefits older households correctly qualify for but never apply for. SNAP for people 60 and older, weatherization assistance, and senior property-tax freezes all require their own paperwork, and none of them arrive without an application.
The Benefits Checklist is a 69-page guide to eleven such programs, with a 50-state phone directory for finding the right office in each state.
Open the guide to these programs at The Benefits Checklist.
This article was researched and drafted with the assistance of AI tools, using data published by the Treasury Inspector General for Tax Administration and the Social Security Administration, and was reviewed for accuracy before publication.