Three tribal nations that spent months under extended IRS deadlines are about to see those extensions run out. Winter storms in Montana and flooding in Arizona each triggered separate disaster declarations, and the agency lined up all three postponement periods to close on the same date. After Monday, the normal tax calendar resumes for affected taxpayers in the Crow Tribe, the Fort Peck Assiniboine and Sioux Tribes, and the San Carlos Apache Tribe.
Three Disasters, One Shared Deadline
The IRS lists postponed deadlines of September 28, 2026 for the Crow Tribe of Montana under disaster designation MT-2026-04, the Fort Peck Assiniboine and Sioux Tribes under MT-2026-03, and the San Carlos Apache Tribe under AZ-2026-01, according to the agency’s tax relief in disaster situations page. The two Montana declarations trace to a severe winter storm and straight-line winds; the Arizona declaration traces to severe storms and flooding, per the same index. Three unrelated weather events in two states ended up sharing one filing deadline because each disaster’s postponement period happened to run the same length before landing on September 28.
The IRS issues these disaster designations tribe by tribe and reservation by reservation rather than under a single blanket declaration for a region, which is why the agency maintains a running index of dozens of separate postponement periods rather than one national disaster tax calendar. For anyone living on or near one of the three affected reservations, the designation number tied to their own tribe, not a general news report about disaster relief, is what actually determines which deadlines moved and which did not.
For the paperwork: A postponed deadline that ends September 28 does not track itself, and a return or payment filed under disaster relief still needs to be logged against IRS notices and confirmation letters once the extension closes. The IRS Refund Recovery Kit includes a deadlines and call log built for keeping exactly that kind of record straight.
What Actually Triggered The Crow Tribe’s Relief
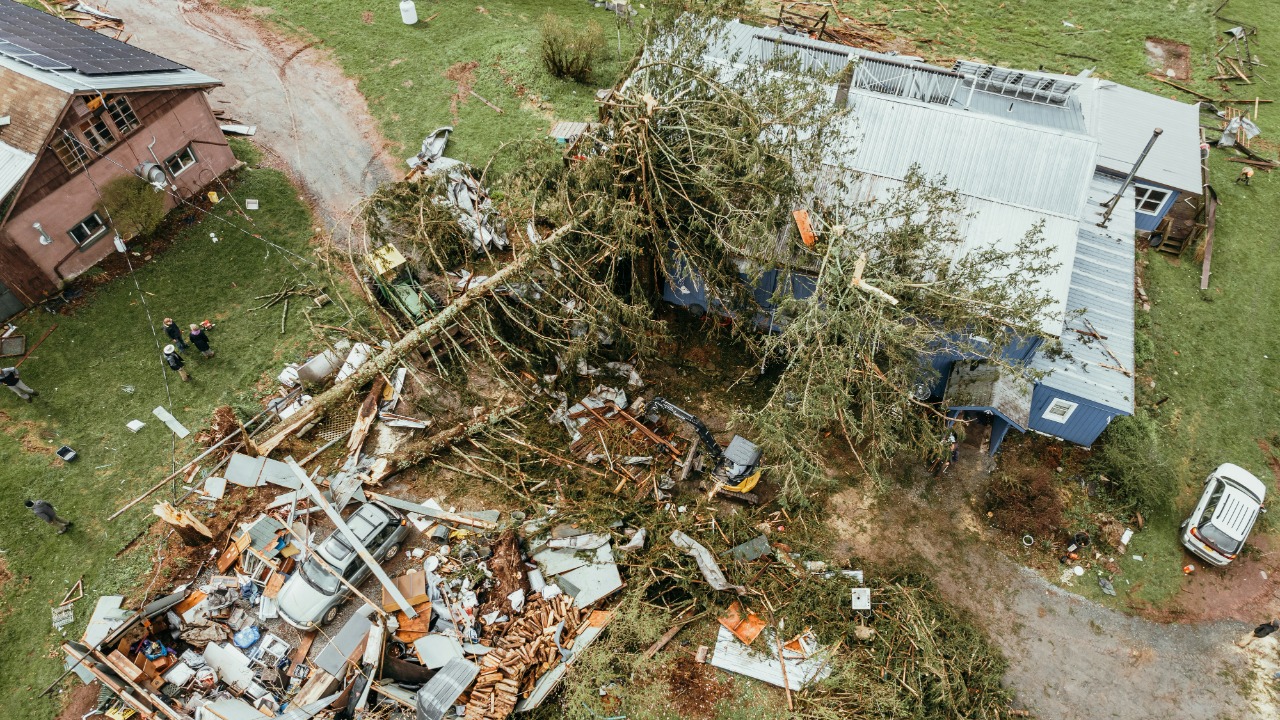
For the Crow Tribe of Montana specifically, the disaster was a severe winter storm and straight-line winds that struck the Crow Reservation in southcentral Montana beginning December 17, 2025, and the IRS set the postponement period to run from that date through September 28, 2026, according to the IRS’s Crow Tribe announcement. That is a nine-month window, longer than the standard disaster extension, covering nearly every individual and business tax deadline that would otherwise have fallen due in that stretch.
What Was Actually Postponed, Beyond The Filing Date
The Crow Tribe relief covers individual income tax returns and payments, corporate, estate, trust, partnership and S corporation returns, quarterly payroll and certain excise tax returns, estimated income tax payments, and gift and generation-skipping transfer tax returns normally due after December 17, 2025, per the same IRS announcement. Information returns, including the W-2 and 1099 series and Forms 3921, 3922 and 8027, are explicitly excluded from the postponement, so those still had to go out on their regular schedule regardless of the disaster relief. Penalties on payroll and excise tax deposits due in the window are abated only if the deposits were made by January 2, 2026, a separate, earlier cutoff nested inside the broader postponement period.
Two Montana Declarations, One Storm System
The Fort Peck Assiniboine and Sioux Tribes received their own, separate disaster designation, MT-2026-03, tied to the same category of event, a severe winter storm and straight-line winds, that triggered the Crow Tribe’s relief, according to the IRS disaster relief index. The two Montana reservations are hundreds of miles apart, and the IRS treats each tribal designation as its own disaster case with its own announcement, even when the underlying weather event and the resulting September 28 deadline line up. The San Carlos Apache Tribe’s relief, by contrast, stems from severe storms and flooding rather than winter weather, under the separate designation AZ-2026-01, and it landed on the identical closing date despite the different storm type and different state.
The Retirement-Account Relief Tucked Into The Announcement
Beyond filing deadlines, the IRS announcement states that qualified disaster distributions from retirement plans are permitted for affected taxpayers, alongside casualty loss deductions, waived fees for copies of prior-year tax returns, and an exclusion of disaster relief payments from gross income. For an older taxpayer on the Crow Reservation who tapped a 401(k) or IRA to cover storm-related costs, that distribution relief can mean avoiding the early-withdrawal penalty that would normally apply, provided the withdrawal falls within the disaster-relief rules tied to this specific declaration.
The casualty loss deduction works separately from the distribution relief: it allows a taxpayer to claim a loss on property damaged or destroyed by the storm on a federal return, while the retirement-distribution relief addresses how any money pulled from savings to cover repairs is taxed. Together, the two provisions cover both sides of a storm-related financial hit, the damage itself and the cost of paying to fix it, without requiring a taxpayer to choose between claiming a loss and tapping retirement savings.
What Actually Resumes On Tuesday
None of the three announcements state that the relief period could be extended again, and the IRS index lists September 28, 2026 as the closing date for all three postponements without qualification. That means any return or payment covered by MT-2026-04, MT-2026-03 or AZ-2026-01 that has not been filed by that date reverts to standard IRS deadlines and penalty rules starting the next business day — a firm date rather than an estimate, drawn directly from the agency’s own disaster-relief listing.
Filing After A Disaster Postponement Closes
Three tribal disaster postponements covering Montana winter storm damage and Arizona flooding all close September 28, 2026, which means returns, estimated payments and payroll deposits covered by MT-2026-04, MT-2026-03 or AZ-2026-01 need to be filed and tracked before the standard penalty rules resume. Confirming what the IRS actually received, and when, is the practical task the postponement notice itself does not walk through.
The IRS Refund Recovery Kit includes a notice decoder for reading IRS correspondence and a deadlines and call log for tracking exactly which returns and payments have been confirmed.
See the notice decoder in The IRS Refund Recovery Kit.
This article was produced with AI assistance and checked against the primary sources linked above.