The Internal Revenue Service’s temporary relief from deposit penalties on the 1 percent remittance transfer tax ran out when the fourth quarter began on Oct. 1. Notice 2025-55 covered only the first three calendar quarters of 2026, so the businesses that send customers’ money abroad now face the ordinary rules for depositing the tax on time.
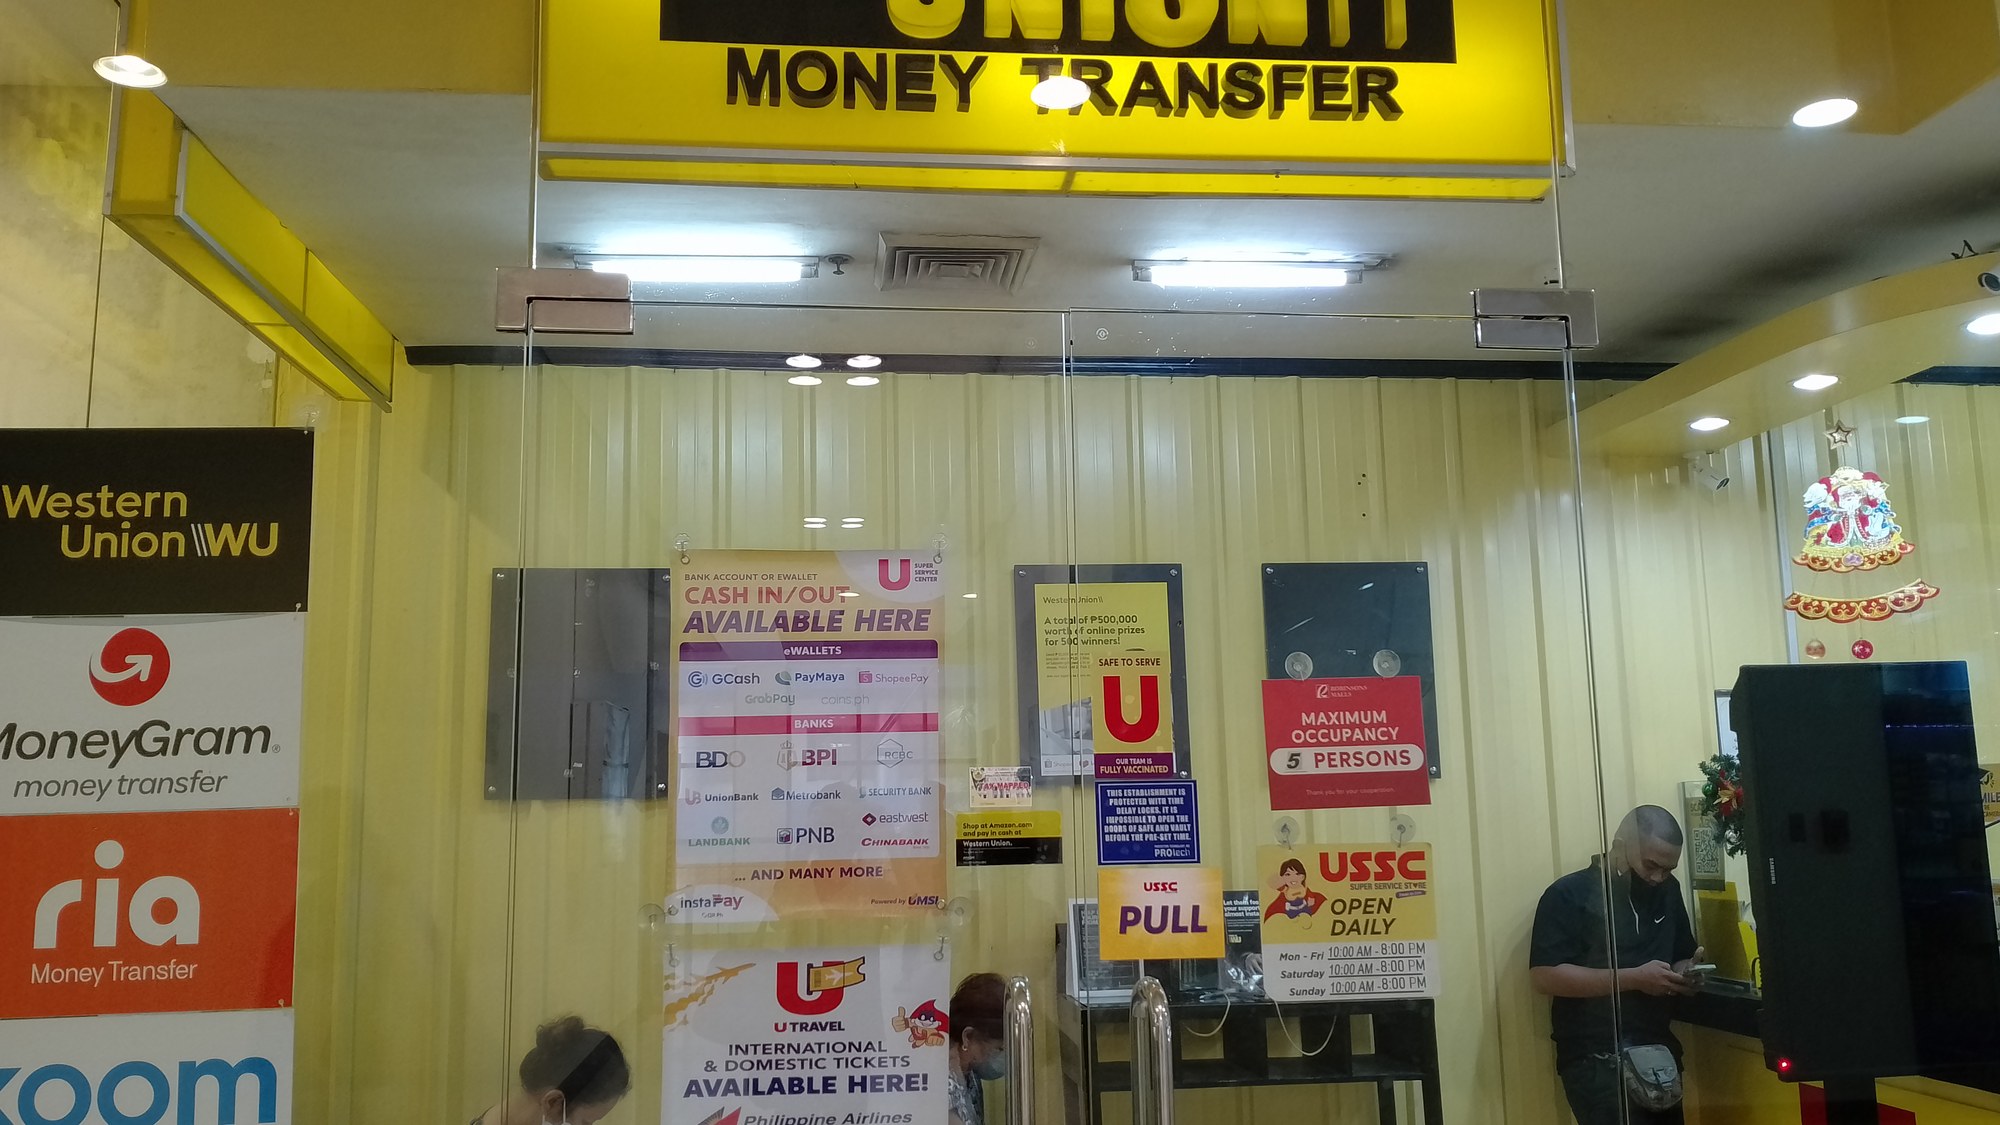
The tax itself is not new as of today. It has applied to certain transfers since Jan. 1, 2026, and customers who pay in cash at a storefront have been charged it all year. What changed on Oct. 1 is the cushion that protected providers from penalties for mistakes in how they deposited it.
What Notice 2025-55 forgave, and for how long
The relief came in Notice 2025-55, issued in advance of the tax. It granted relief from failure-to-deposit penalties under section 6656 of the Internal Revenue Code for “the first, second, and third calendar quarters of 2026.” Nothing in the notice reaches the fourth quarter.
The relief was conditional. A provider was treated as having shown reasonable cause if it made timely deposits of the tax, even when the deposit amounts were computed incorrectly, and if any underpayment for the quarter was paid in full by the due date of that quarter’s Form 720. The notice also said a provider’s ability to use the deposit safe harbor in section 40.6302(c)-1(b)(2) of the regulations would not be affected by a failure during those three quarters.
That is a narrow kind of grace. It did not waive the tax, and it did not excuse a missed deposit. It forgave arithmetic and process errors for providers that otherwise deposited on time. With the third quarter closed, that special treatment is gone for the deposit periods that begin in the fourth quarter. The IRS release index through Sept. 30 showed no announcement extending it.
How the 1 percent reaches a customer at the counter
The Instructions for Form 720, revised in June 2026, add the tax as IRS No. 155 on the quarterly excise return. They say it applies to certain remittances when the sender makes the transaction with cash, a money order, a cashier’s check or a similar physical instrument, and that remittance transfer providers are required to collect it from those senders.
At 1 percent, every $1,000 sent in cash carries $10 in tax, on top of whatever fee the provider already charges. The IRS pages read for this article do not say how any particular provider shows the tax on a receipt, and providers set their own fees, so the amount a customer sees at the window can differ by company.
The tax does not reach every transfer. According to the proposed regulations published in the Federal Register, it does not apply when the funds being transferred are withdrawn from an account held in or by a financial institution, or funded with a debit card or credit card issued in the United States. In practice, the cash, money order and cashier’s check routes are the ones the IRS describes as taxed.
Proposed rules still in play nine months in
The detailed regulations have not been finalized. The IRS published a notice of proposed rulemaking on April 13, 2026, with comments and hearing requests due by June 12. It is a proposed rule, not a final one.
The proposal states that “the remittance transfer tax is paid by the sender,” and that the provider “collects and remits the remittance transfer tax quarterly.” It also lets taxpayers rely on the proposed regulations for transfers made after Dec. 31, 2025, until final regulations arrive. The final text could change details, and the proposal says final rules would govern transfers in calendar quarters that begin on or after their publication.
That leaves providers, and the customers who pay them, working from a statute that is in force and a rulebook that is still a draft. The proposal lists Julia Barlow of the IRS Office of the Associate Chief Counsel (Energy, Credits, and Excise Tax) as the contact for questions about the regulations, at (202) 317-6855.
Who carries the cost after the lapse
For senders, the lapse changes nothing at the counter. The rate stayed at 1 percent through September and remains 1 percent in October. The sender owes the tax under the proposed rules, and the provider is responsible for collecting and remitting it.
The exposure shifted to the provider side. Under the notice, the shield applied to deposit penalties, so a provider that deposits late or short in the fourth quarter no longer has the notice’s deemed reasonable-cause treatment to point to. Whether a given provider changes its fees, its receipts or its staffing in response is not addressed in the IRS documents, and no sourced reporting for this article shows such changes.
Money orders and cashier’s checks matter here because they are also ordinary tools for people without a card or a bank account, or who prefer not to move large sums electronically. The IRS describes the taxed category by the instrument used, not by the destination or the sender’s age, so a retiree sending cash to a relative abroad falls within it on the same terms as anyone else.
Where the questions go
The Notice 2025-55 text lists the same Office of the Associate Chief Counsel (Energy, Credits, and Excise Tax) at (202) 317-6855 for questions about the relief. The tax is reported on Form 720 as IRS No. 155, and the controlling statement of what ended on Oct. 1 remains the notice’s own wording: relief for “the first, second, and third calendar quarters of 2026,” and no later period.
Cash transfers, fees and the money that stays in the account
The Bank Account & Debt Protection Kit is for households that keep a checking account and need a plan for the moments when that account is frozen or a collector’s letter arrives. Those problems come up whether or not any money is sent abroad.
The Bank Account & Debt Protection Kit is a 10-page kit that includes the 2-month bank protection rule, the debt-validation steps, the frozen-account response and a protected-funds and dispute log.
Get The Bank Account & Debt Protection Kit →
This article was produced with AI assistance and checked against the primary sources linked above.