Federal agencies are funded through December 11, 2026, and the National Flood Insurance Program is authorized through the same date. Both come from a single law, H.R. 6500, the Continuing Appropriations and Extensions Act, 2027, which was signed on September 2. No funding lapse occurred on October 1, the first day of the fiscal year, and no shutdown is under way.
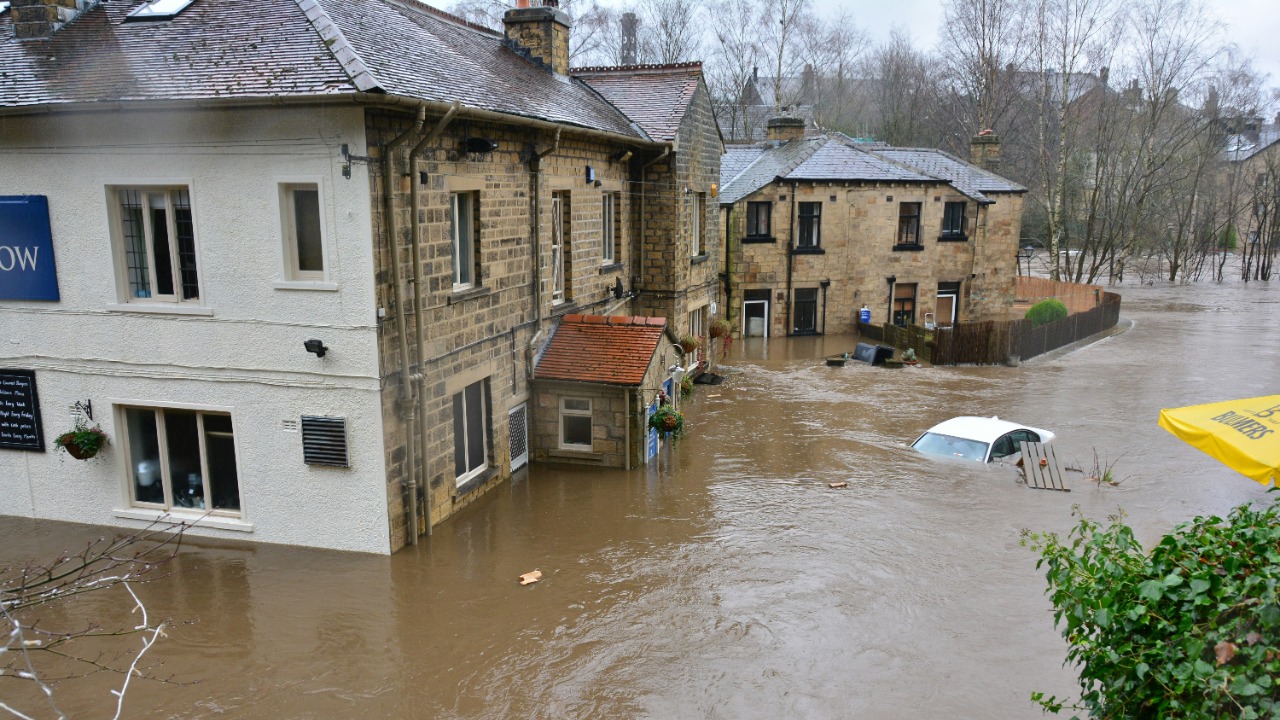
For homeowners, the December 11 date matters less for what it funds than for what it ties together. Flood insurance sold through the federal program is the coverage many mortgage lenders require in mapped flood zones, and its authority now expires on the same day as the spending bill that carries it.
What the stopgap funds and extends
The White House announced that the President signed H.R. 6500 on Wednesday, September 2, 2026. Its notice describes a short-term continuing resolution that provides fiscal year 2027 appropriations to federal agencies through December 11, 2026. The notice carries no quoted remarks from any official.
The detail on what else rides along comes from a section-by-section summary compiled by Senate Appropriations Committee staff and the staff of the authorizing committees. That document says the resolution expires on the earlier of December 11, 2026, or enactment of full-year fiscal year 2027 appropriations. Section 139 extends the National Flood Insurance Program for the duration of the resolution, so flood insurance authority runs to December 11 as well. Section 147 continues the Essential Air Service Program, which subsidizes commercial flights to small communities, for the same period.
The bill’s status on Congress.gov lists it as signed into law on September 2, 2026, and the Congressional Research Service refers to the enacted text as Public Law 119-103. Nothing in the official record points to a furlough, a missed payment or an interruption in benefits.
Why a flood insurance deadline reaches mortgage borrowers
The money question is conditional. Nothing described here is a forecast, and Congress has until December 11 to act again. If the program’s authority were allowed to expire without a new extension, the practical effects would fall mostly on people buying a home, refinancing or renewing coverage.
The National Association of Realtors, in an FAQ on program expiration last updated February 4, 2026, states that the program “cannot issue new or renewal flood insurance policies until the program is reauthorized.” The same FAQ says existing policies remain in effect until their expiration date, including a 30-day grace period. A policy that comes up for renewal during a lapse is therefore the exposed one, not a policy already in force.
Closings are the second pressure point. The association says insurers may assign a seller’s federal policy to a buyer by substituting names, which keeps coverage on the property in place. It also says most federal lending regulators suspend the flood insurance purchase requirement during a lapse, leaving it to lenders to decide whether to make loans in special flood hazard areas. In that situation, a lender’s own policy, not the federal requirement, would decide whether a closing proceeds and on what terms.
The NAR FAQ names no individual spokesperson, and the Senate summary names no committee member, so the attributions above rest on the institutions that wrote them.
Two clocks that end on December 11
Because the flood program and the spending resolution share an end date, any new extension will probably travel with whatever Congress passes to fund agencies next. A full-year appropriations act enacted before December 11 would end the resolution earlier, and with it the extension that Section 139 ties to the resolution’s life.
Homeowners with a flood policy that renews in the weeks around December 11 are the readers with the most to track. The renewal date printed on the policy, and the lender’s requirements stated in the loan documents, are the two facts that determine how any gap would apply to a specific household. Buyers scheduled to close in the same window have the further variable of whether the seller’s policy can be assigned.
The same law’s treatment of Essential Air Service shows how the package works: programs with their own expiration dates are folded into the stopgap so they do not lapse separately. Each of those programs now carries the December 11 date, and each will need to be extended again or funded in a full-year bill.
The primary record is brief and consistent. The White House notice of September 2 sets the funding date, and the Senate Appropriations section-by-section places the flood insurance extension at Section 139 for the duration of the same resolution.
Flood Insurance Authority and the Bills That Follow a Lapse
Homeowners on fixed incomes carry a stack of recurring housing costs, from property taxes to heating and cooling to repairs, and relief programs for each have separate applications and renewal dates that are easy to lose track of. The kit below is written for older homeowners and renters who want those dates and applications kept in one place.
The Senior Property Tax & Home-Cost Relief Kit is an 11-page kit that covers the five kinds of property-tax relief and the circuit-breaker credit that includes renters, and it includes an application log and renewal calendar.
Open the kit to organize property-tax relief applications and renewal dates →
This article was produced with AI assistance and checked against the primary sources linked above.