Borrowers with certain risky Credit Acceptance Corporation car loans written between Nov. 1, 2015, and Nov. 30, 2025, are covered by a $694 million multistate settlement that takes effect Monday, Nov. 2. Most of the money is debt cancellation, with $60 million set aside as cash restitution for the riskiest loans. The deal was announced Sept. 17 by a bipartisan group of state attorneys general.
California Attorney General Rob Bonta said the company “closed its eyes to deceptive origination practices,” making high-cost loans that were likely to end in repossession. His office’s announcement describes a settlement that is subject to court approval, with debt relief due on or before Nov. 2.
How the $694 million is divided
The nationwide total breaks into three pieces, according to the Connecticut attorney general’s office. Credit Acceptance must provide $388 million in debt relief for borrowers whose vehicles were repossessed and $246 million for borrowers who still have their cars. The remaining $60 million is cash restitution.
Only part of that is money paid to people. Debt cancellation lowers or erases what a borrower still owes, which matters most to someone who got a repossession notice and a bill for the leftover balance. The cash goes to consumers who received particularly risky loans, though the attorneys general have not spelled out the exact test for “particularly risky.”
A separate $15 million goes to the states themselves. Arkansas, for example, receives $660,000 in civil penalties, according to the Arkansas release posted by the attorneys general’s association.
What the loan window means for a borrower
The window is set by when the loan was written, not by when it was paid off or repossessed. A car financed in 2017 and repossessed in 2020 sits inside it. So does a loan opened in the last days of November 2025 that is still being paid.
Not every loan inside the window qualifies. The relief is aimed at loans the states describe as risky, the kind the attorneys general say were likely to fail. Borrowers who find the origination date on their contract in that range have cleared the first test, but the company decides which accounts get debt relief and a claims administrator decides who gets restitution.
Anyone holding a retail installment contract from a dealer who assigned the financing to Credit Acceptance should look at the date near the top of the document. The lender named on the monthly statement is the one to look for.
Retirement deadlines, in your inbox: Miss an enrollment or claim deadline and the money can be gone. Join the Retirement Money Brief and we’ll send you our Open Settlements & Refund Tracker as a welcome gift.
Get the Brief + the settlements tracker →
We may earn a commission from links on this page.
Consumers with a loan in that range who are unsure whether it was bought by Credit Acceptance can check the lender named on the most recent statement or on the title paperwork. A statement that lists Credit Acceptance as the servicer is the match that counts.
Is a claim form required?
No claim form has been announced. The California release says eligible consumers have already been identified and “do not need to take any action.” Connecticut’s office says Credit Acceptance will notify customers eligible for debt relief, while a claims administrator will notify those eligible for restitution.
That makes the mailbox and the online account the places to watch. A borrower whose loan fits the window and who has heard nothing by the end of the year can call the Arkansas attorney general’s settlement line at (501) 682-2007, which the Arkansas release lists for questions, or contact their own state attorney general’s consumer office through the National Association of Attorneys General.
What changes for new loans and for borrowers after November 2025
Loans written from December 2025 onward are not part of the main debt relief, but certain ones qualify for what the settlement calls an “off ramp.” Beginning Nov. 2, Credit Acceptance must give 95% debt relief to qualifying consumers and is barred from filing collections lawsuits against them for five years.
The agreement also puts rules on future lending. According to the Arkansas release, certain consumers get a seven-year price cap of 109% of retail book value. Credit Acceptance must give pre-loan disclosures about default risk and vehicle value, and dealers are restricted from packing vehicle service contracts and GAP products into loans, with easier cancellation after purchase.
Those add-on products are where many borrowers lose money without noticing. A service contract or GAP charge rolled into the loan is financed along with the car, so interest accrues on it for years. Attorney General William Tong said the company “profited off risky loans destined to fail, padded with worthless services and so-called protections.”
What the states say their residents will see
Bonta’s office estimates California consumers will receive about $1.46 million in restitution and $5.4 million in debt relief, for $6.86 million in all. Connecticut says eligible residents there can expect up to $2 million in financial relief, plus a $177,650 payment to the state.
New York is settling its own separate lawsuit against Credit Acceptance in federal court in Manhattan at the same time. Attorneys general from 39 states and the District of Columbia joined the multistate agreement, with Maryland, Arkansas, California, Illinois, Minnesota and New Jersey on the executive committee.
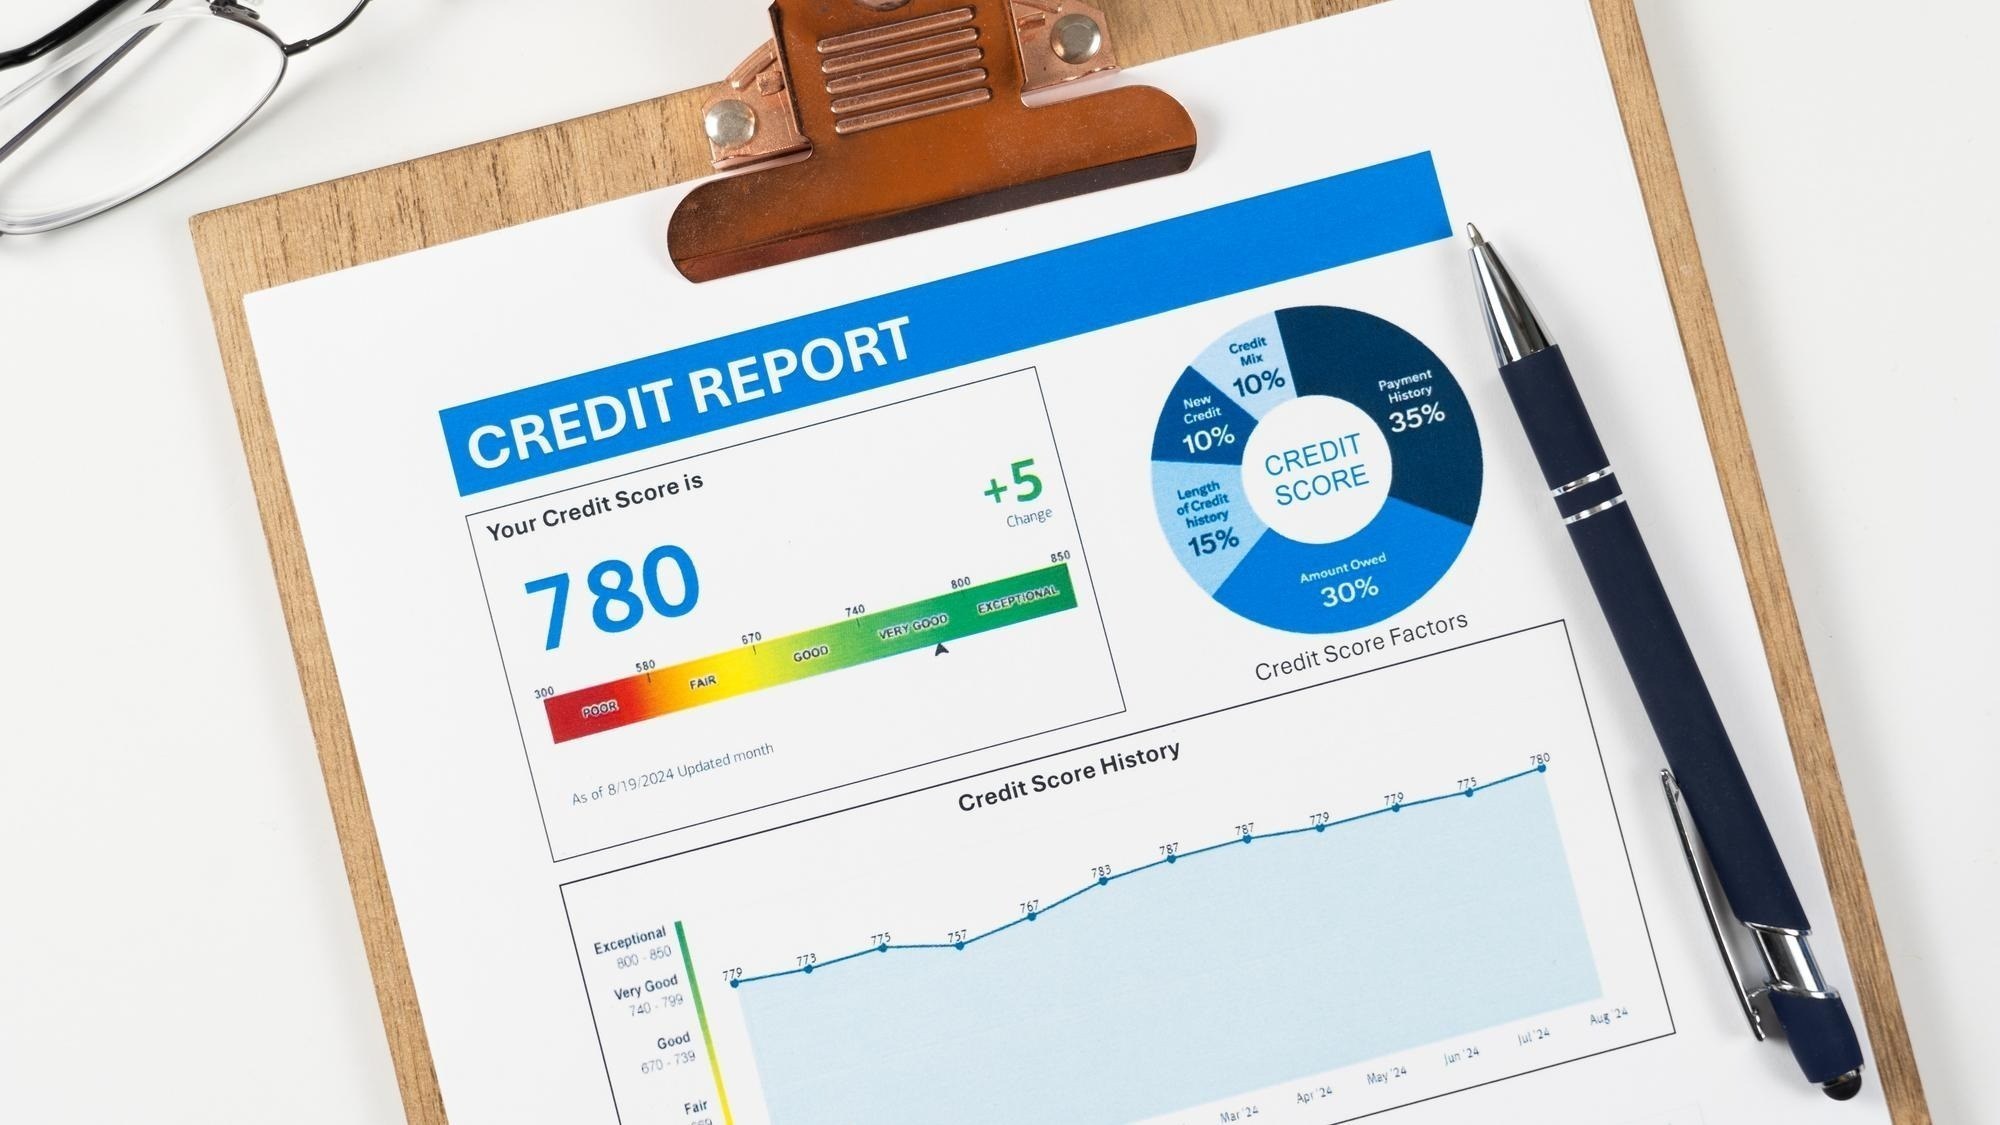
Relief on a credit report is a separate matter. The attorneys general’s releases do not say how the debt cancellations will be reported to the credit bureaus, so a borrower whose balance is erased should ask the company in writing how the account will show afterward and keep every notice.
Keeping the paper trail
Borrowers do best by saving the original contract, the most recent statement and any repossession notice in one folder before the notices start to arrive. Those papers show the origination date, the lender and the amount still owed, which are the three things a dispute over relief would turn on.
Anyone who receives a notice that lists a lower balance, or none, should compare it with the last statement and write down the date it arrived. A balance that has not changed after Nov. 2 on a loan that fits the window is worth a call to the company and, if the answer is unclear, to the state attorney general’s office.
Was the loan written inside the window, and will anything arrive?
A notice can come from a lender or an administrator the borrower has never heard of, and a missed letter or a changed address is how settlement money goes unclaimed. Debt relief and restitution come in separate mailings, and either one can be mistaken for junk.
“The Money Owed to You Bundle” includes “Open Settlements: How to File: the four-date rule, the two claim tiers, proof without receipts, and chasing a payment,” which walks through what to keep and who to contact when a payment does not show up. It is a large-print download of eight guides, and every search and claim it describes is free at the official source.
Chase a settlement payment that never arrives with the Money Owed guides →
This article was produced with AI assistance and edited for accuracy against the sources linked above.