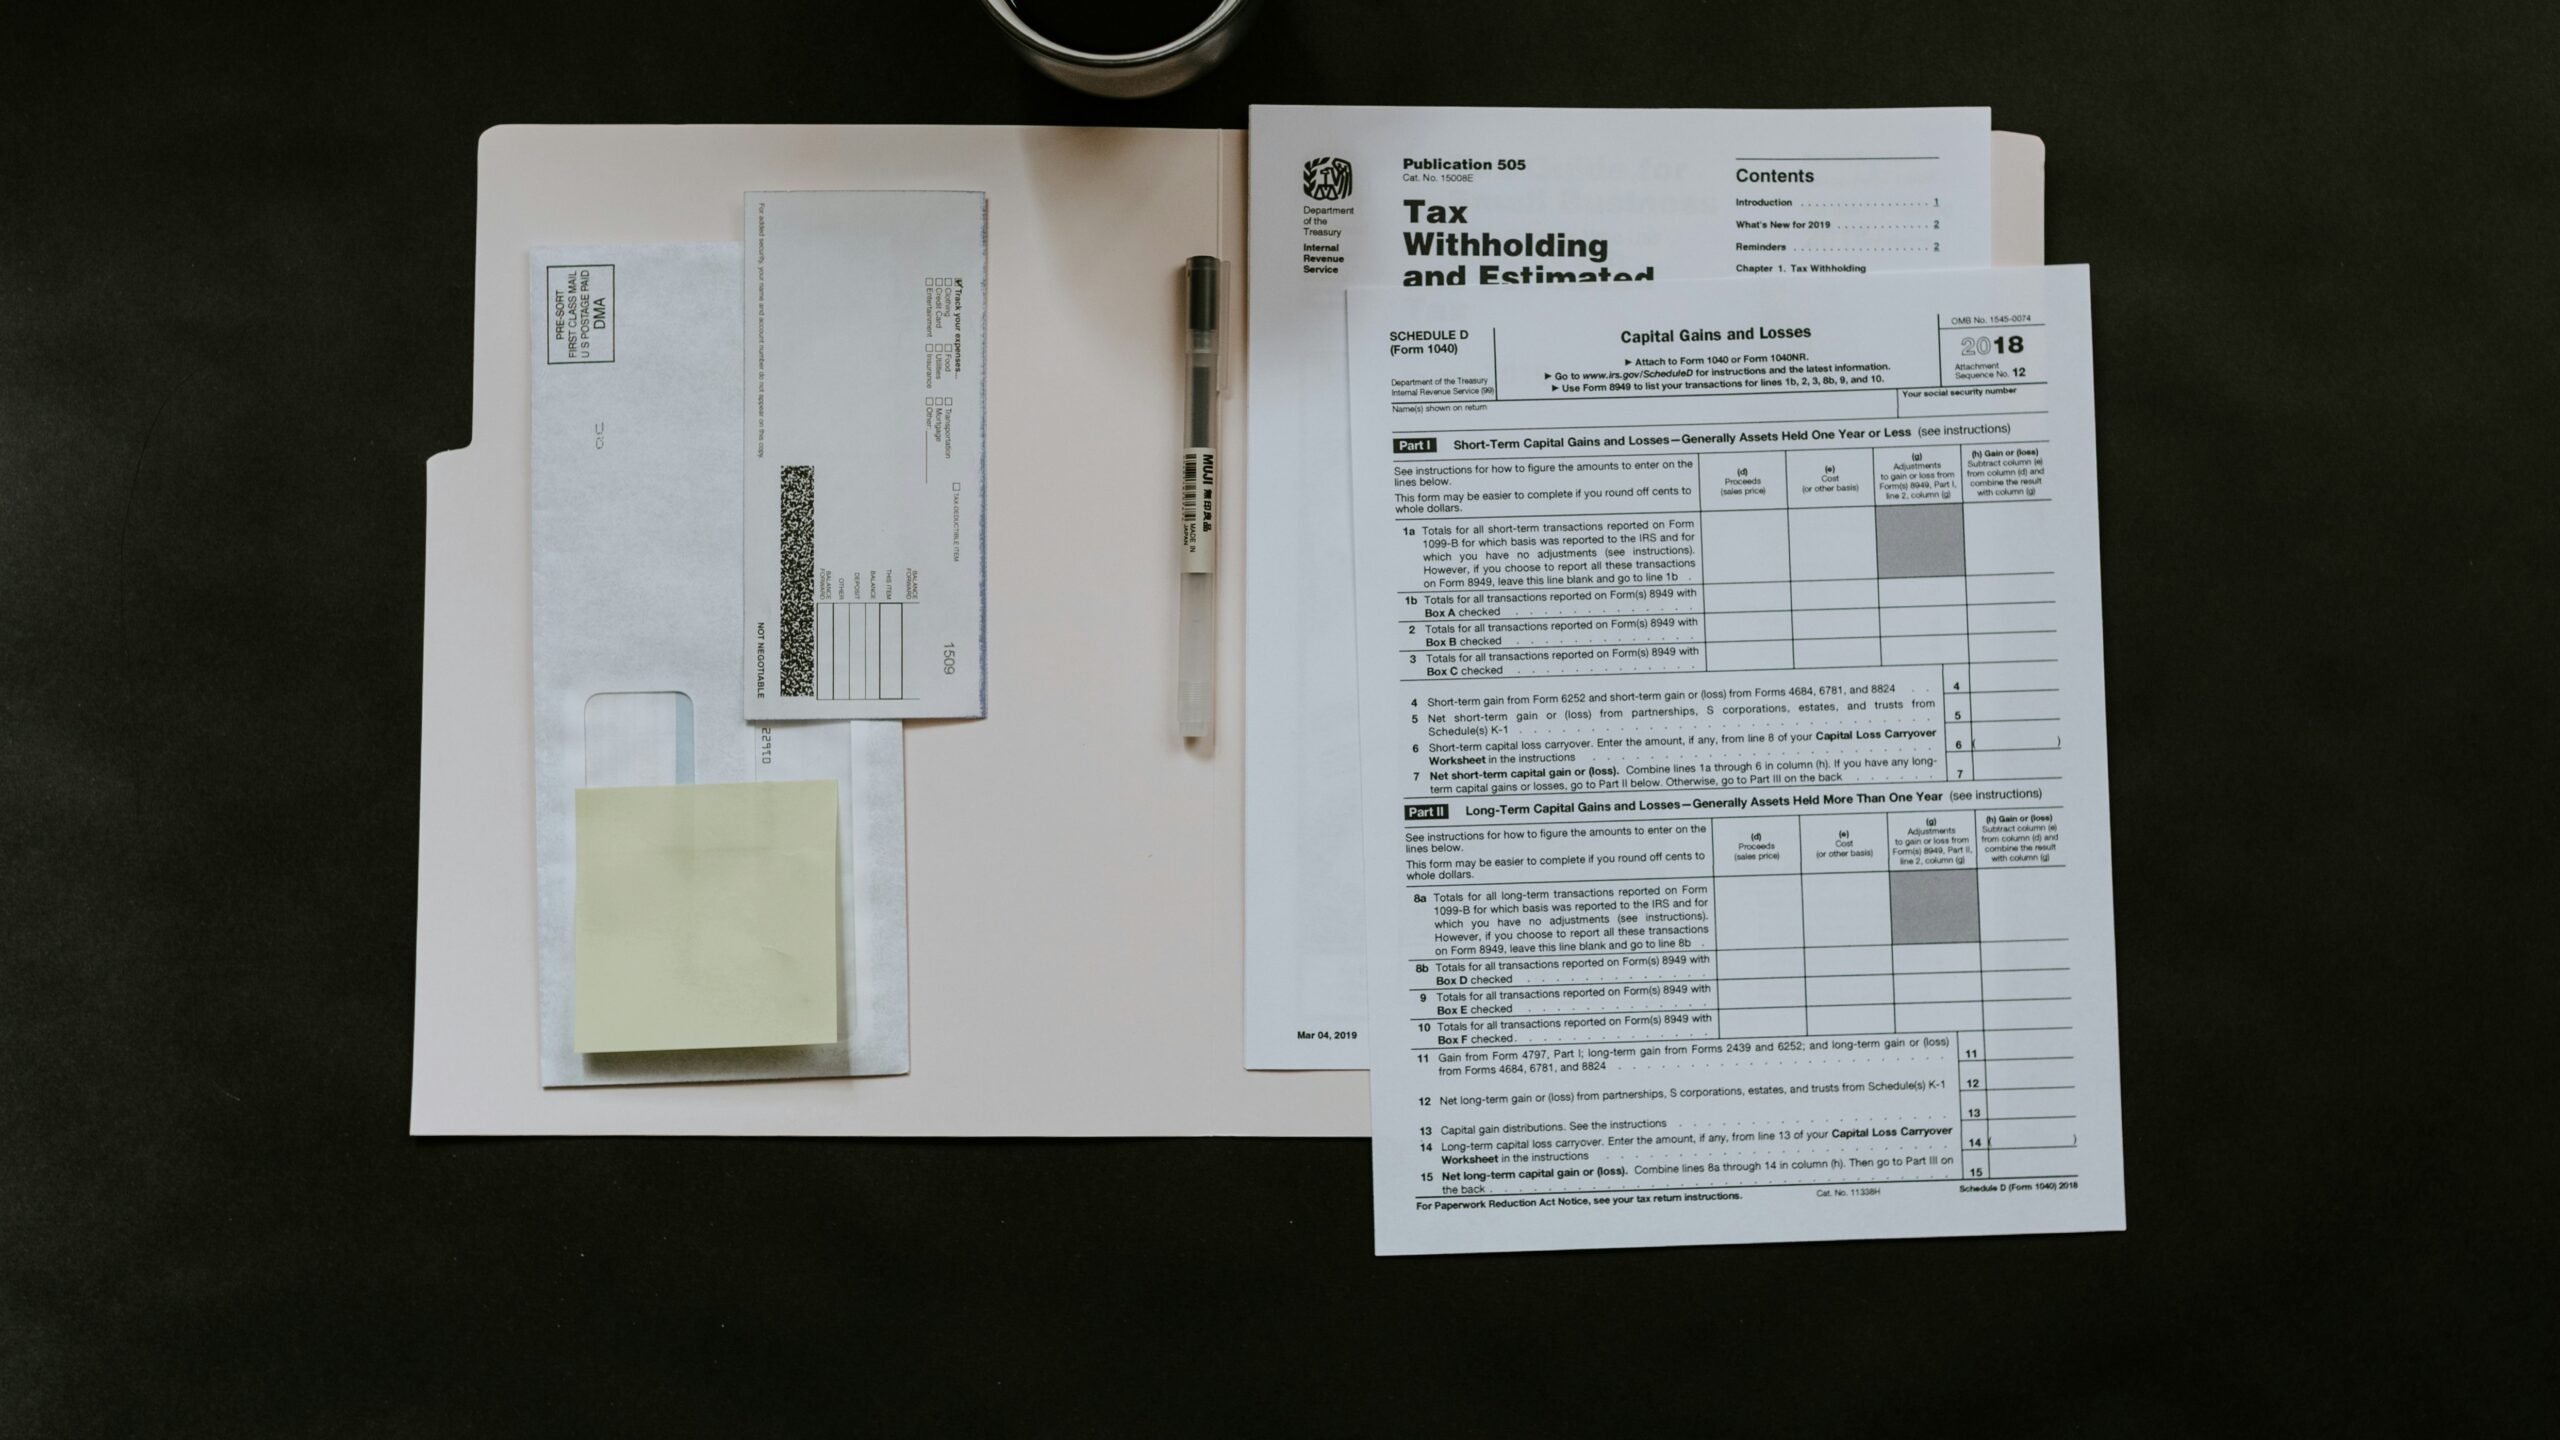
Consumers chasing bank sign-up bonuses of $1,000 or more this year face a tax bill that can shave hundreds of dollars off the advertised payout. The IRS treats those bonuses as taxable interest income, and banks are required to report them on Form 1099-INT once the amount hits $10. For a filer in the 22 percent federal bracket who also owes state income tax, a $1,500 bonus can shrink to roughly $1,100 or less after taxes, a gap that rarely appears in the promotional fine print.
Why the Tax Hit on Bank Bonuses Matters Right Now
Banks have been raising bonus amounts to attract new deposits, but the federal tax code has not budged. Under Section 61 of the Internal Revenue Code, gross income includes “all income from whatever source derived,” and interest is explicitly listed among the categories. That statutory language means a $500 checking bonus and a $3,000 savings bonus land on a tax return the same way ordinary bank interest does. There is no carve-out, no grace period, and no minimum-income exception.
The practical friction goes beyond the dollar amount owed. When a bonus posts in a given calendar year, the bank must generate a 1099-INT and send it to both the account holder and the IRS. That form arrives the following January, often months after the consumer has spent or reinvested the bonus. Filers who opened accounts at multiple banks to stack bonuses can end up with several additional tax documents, each requiring separate entry on Schedule B. For middle-income households already juggling W-2s, 1098s, and brokerage statements, the added complexity can delay filing or push them toward paid tax preparation.
The hypothesis that bonuses between $500 and $1,500 will see lower net uptake among middle-income filers once tax and filing costs are factored in rests on simple arithmetic. A filer earning $60,000 who collects a $1,000 bonus owes federal tax on every dollar of it, plus any applicable state tax. If that filer pays $15 for an upgraded tax-software tier to handle the extra 1099, the effective return drops further. No public IRS dataset isolates bonus-driven 1099-INT filings from ordinary interest reporting, so the drag on uptake is difficult to measure directly. Still, the gap between the advertised headline and the after-tax reality is wide enough to change the cost-benefit calculation for many households.
IRS Rules and Federal Regulations Behind the 1099 Trigger
The reporting obligation is spelled out in multiple layers of federal authority. According to IRS guidance on taxable interest, most interest is taxable income in the year it becomes available, and taxpayers must report it even if they never receive a Form 1099-INT or 1099-OID. That last detail catches filers who assume that no form means no tax liability. The IRS expects the income on the return regardless.
Banks, for their part, follow a clear threshold. Payers must file Form 1099-INT when reportable interest paid meets or exceeds $10, according to the official instructions for Form 1099-INT. Once that line is crossed, the institution is obligated to send a copy to the taxpayer and electronically report the same amount to the IRS. That electronic trail makes it easy for the agency to match what banks say they paid with what taxpayers say they received, and it raises the risk of a notice if the income is omitted.
For consumers, the $10 trigger can feel arbitrary when bonuses run into the hundreds or thousands of dollars, but it is central to how the system operates. A $200 checking bonus, a $50 savings bonus, and $5 in regular interest from the same bank are combined for reporting purposes; if the total is at least $10, the entire amount is reported. That aggregation means even modest bonuses can tip an account holder into 1099 territory, especially when interest rates are higher.
How Consumers Can Weigh the After-Tax Value
None of this makes bank bonuses a bad deal on their face, but it does change how they should be evaluated. A household in a 12 percent federal bracket with no state income tax will keep far more of a $500 bonus than a household in a 24 percent bracket facing an additional 5 percent state levy. Savvy consumers can estimate their combined marginal rate, multiply it by the advertised bonus, and subtract that figure from the headline number to see the likely after-tax value.
There are also behavioral considerations. Some filers are comfortable tracking multiple 1099-INT forms and entering them manually, while others see any added paperwork as a cost in itself. For those who rely on free tax software that limits the number or type of forms allowed, a single large bonus could force an upgrade to a paid version, further eroding the net benefit.
Ultimately, bank sign-up bonuses function like any other form of taxable interest: the IRS will treat them as income, banks will report them when required, and taxpayers must reconcile the difference between marketing promises and after-tax reality. For consumers willing to do the math and manage the paperwork, the offers can still be lucrative. For others, especially those in higher tax brackets or in states with steep income taxes, the shine of a four-figure bonus may fade once the tax bill arrives.


