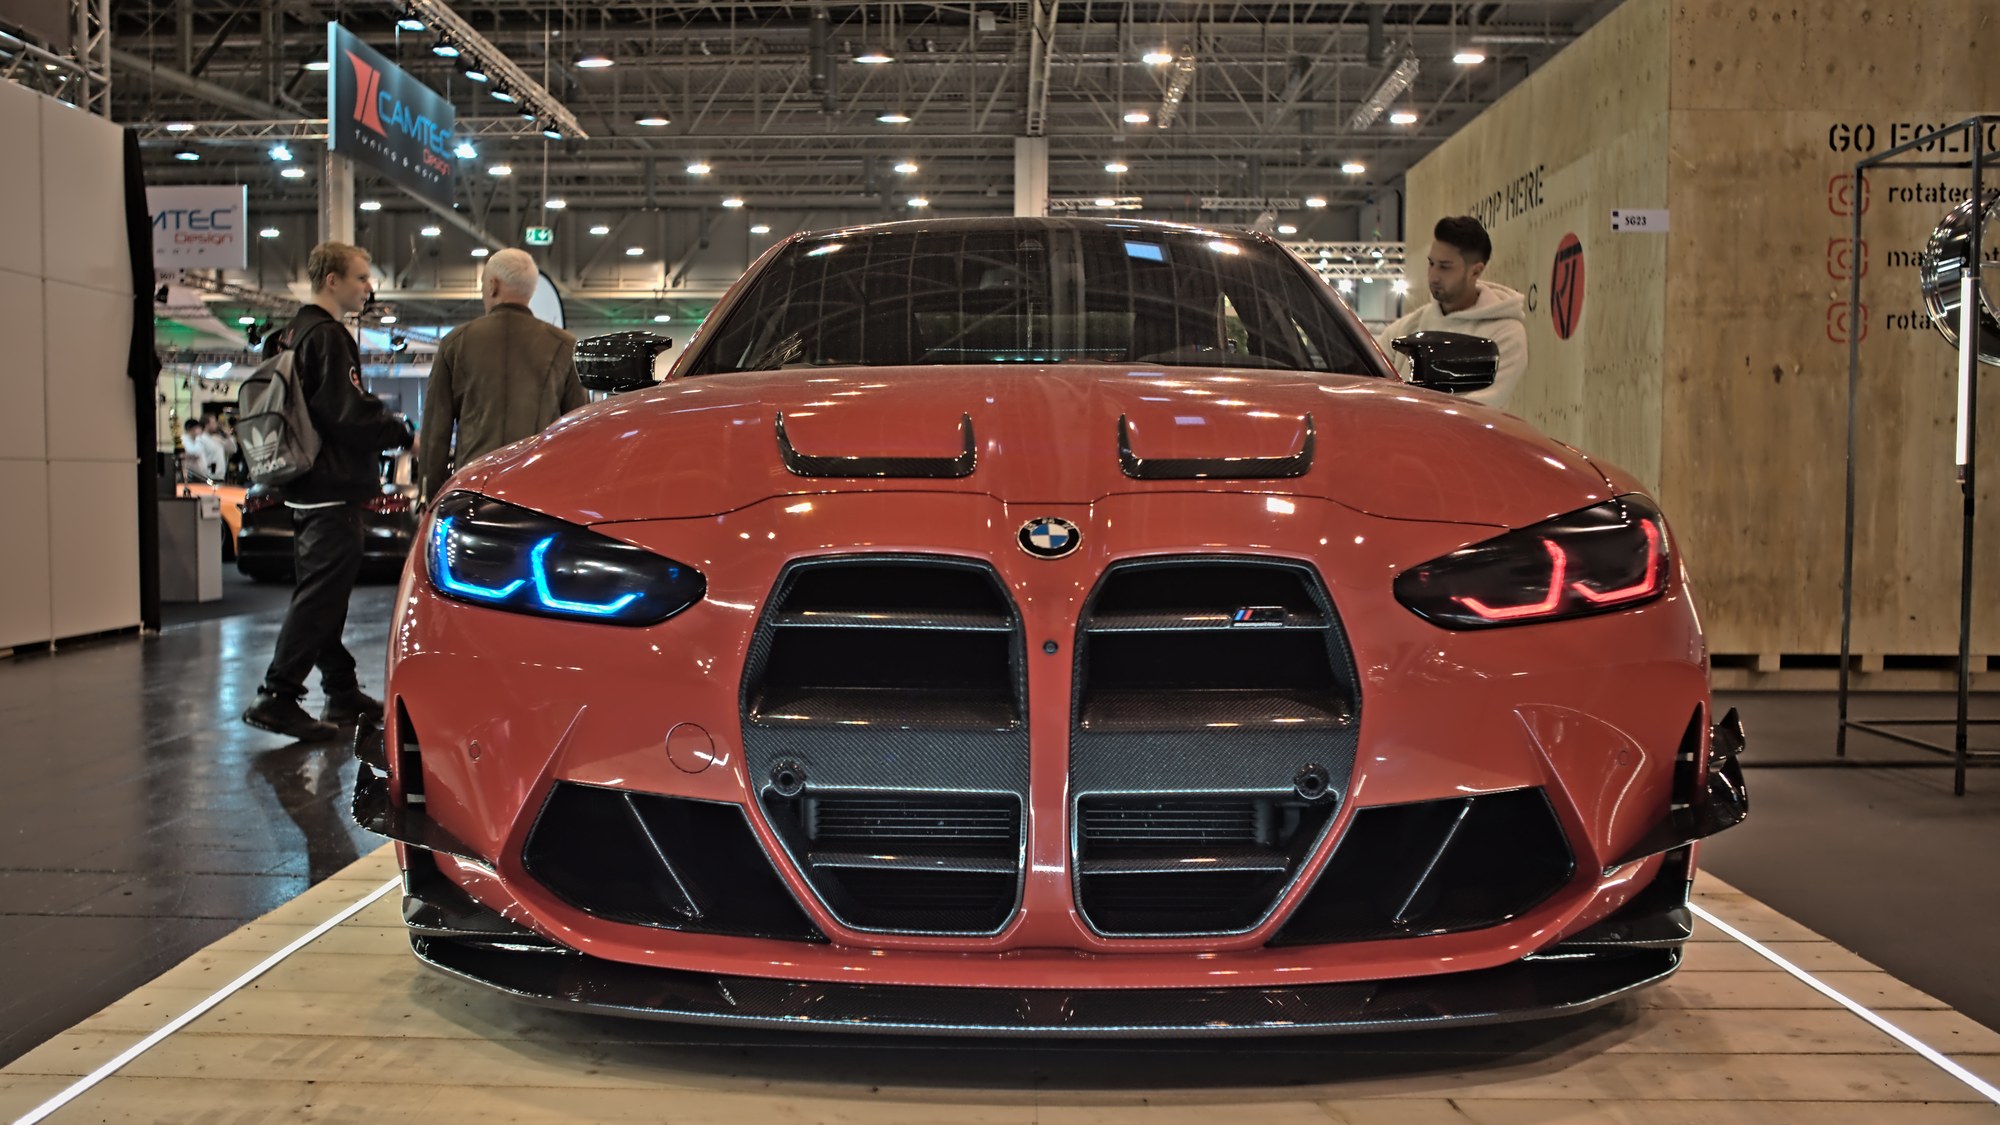
The BMW M4 costs more to insure than any other vehicle in Compare.com’s newest ranking of the priciest cars to cover, at $319 a month, or $3,828 a year. The site’s Sept. 24 analysis, built from more than 50 million real insurance quotes gathered across more than 100 partner insurers, put the M4 narrowly ahead of the Nissan GT-R and Toyota GR86 at $3,816 a year and the Tesla Model 3 at $3,600. The gap between the priciest and cheapest vehicles on the list runs into the hundreds of dollars a year, even before any driver’s own record or location is factored in.
One rising bill, not the only one: Compare.com’s ranking prices out the auto-insurance side of a household budget, but property taxes and utility bills climb on their own schedule, and The Senior Property Tax & Home-Cost Relief Kit spells out who actually qualifies for relief on those. See the five kinds of property-tax relief →
The BMW M4 Tops Compare.com’s List At $3,828
The Compare.com ranking puts the BMW M4 at the top of its most-expensive-to-insure list for 2026, at $319 a month, or $3,828 a year, based on more than 50 million real quotes pulled from over 100 partner insurance companies rather than a survey or self-reported estimate. Compare.com describes itself as an online insurance comparison marketplace, and the figures reflect what its own quote engine actually returned for the vehicle, not a manufacturer’s suggested cost or a single insurer’s rate card. The M4 is BMW’s high-performance coupe, built on a turbocharged six-cylinder platform that insurers price for both its repair cost and its speed. Compare.com’s own description of its methodology says the figures come from real quotes returned to actual shoppers rather than list rates, which is why the numbers can differ from what a single insurer’s own online calculator might show for the same car and driver profile.
The Full Top Ten, Led By Performance And Electric Models
Behind the M4, the ranking’s next four spots go to the Nissan GT-R and Toyota GR86, tied at $3,816 a year, the Tesla Model 3 at $3,600, and the Mercedes-Benz GLE Coupe at $3,588. Three more Teslas and a GMC Hummer EV also appear further down the list, alongside the Toyota Supra and Porsche Panamera, all still above $3,200 a year. The pattern across the list is consistent: sports coupes prized for speed and electric vehicles with expensive battery packs and body panels dominate the top of Compare.com’s rankings, while ordinary sedans and crossovers, which make up most of the vehicles Americans actually drive, do not appear on it at all. None of the ten vehicles on the list is the kind of car a typical retiree drives day to day, but the size of the spread between them, more than $500 a year between the top and bottom entries, illustrates how much a single vehicle choice can move an insurance bill compared with almost anything a driver does behind the wheel.
Nationally, Auto Insurance Costs Just Eased Slightly
The Bureau of Labor Statistics’ August 2026 Consumer Price Index shows the motor vehicle insurance index falling 0.8% for the month, its second straight monthly decline after a 0.3% drop in July. That national trend runs in the opposite direction from what a BMW M4 or Nissan GT-R owner sees on a renewal bill, because the CPI sub-index tracks the average change in what existing policyholders pay across the whole vehicle fleet, while Compare.com’s ranking prices a single model against the field. A national average easing does not mean every vehicle’s premium is falling, and the widest gaps, the kind Compare.com’s list highlights, sit between specific models rather than between years. The same BLS report that showed insurance costs easing also showed gasoline prices up sharply over the past year, a reminder that the individual line items inside a household’s transportation budget rarely move together even when the broader index does.
Why Regulators Track A Different Number Than Ranking Sites
The National Association of Insurance Commissioners, the standard-setting body for state insurance regulators, compiles its own auto insurance data through an annual database report built from company filings by state and coverage type, not by vehicle model. That is one reason a per-model ranking like Compare.com’s exists alongside NAIC’s regulatory figures rather than replacing them: state regulators need to know what insurers are charging as a whole to police unfair pricing, while a shopper deciding between two cars needs the model-specific number NAIC’s own data was never designed to provide. NAIC’s own explanation of market-conduct regulation notes that rate approval happens state by state, which is also why the same BMW M4 can carry a different premium from one state to the next even before Compare.com’s national average is applied.
What Drives The Price Gap Between Models
Insurers set a vehicle’s premium largely around what it costs to fix or replace after a claim and how often that vehicle is involved in one, which is why the two forces line up on Compare.com’s list: high-performance coupes carry both higher repair bills and higher accident risk tied to their speed, while electric vehicles carry expensive battery packs and specialized parts that push up the cost of even routine repairs. Neither factor shows up on a CPI report or a NAIC filing broken out by model, which is exactly the gap a shopping tool like Compare.com’s ranking is built to fill for someone comparing two specific vehicles rather than tracking the market as a whole. State insurance departments, whose authority over rate approval NAIC’s own history of state insurance regulation traces back more than a century, still leave the choice of which vehicle to insure entirely up to the driver, which means the price gap Compare.com found is one no regulator is positioned to close.
Offsetting One Rising Bill With Relief On Another
A single vehicle’s annual insurance bill is a reminder of how unevenly household costs can land, and auto insurance is only one line on a budget that also includes property taxes, utility bills and home upkeep, none of which move in sync with each other or with a CPI average. Older homeowners and renters carrying several of those costs at once often qualify for relief on the property-tax and utility side without ever applying, simply because each program has its own separate form and deadline.
The Senior Property Tax & Home-Cost Relief Kit lays out the 5 kinds of property-tax relief and the circuit-breaker credit that also covers renters, so a household squeezed on one bill can find out what it is owed on another.
Read the relief programs in The Senior Property Tax & Home-Cost Relief Kit.
This article was produced with AI assistance and checked against the primary sources linked above.