Families with children born between 2025 and 2028 face a deadline-driven decision this summer: file a one-page federal form or leave $1,000 in government money on the table. The U.S. Department of the Treasury will begin depositing a one-time $1,000 pilot contribution into Trump Accounts for eligible children starting July 4, 2026, but the money does not arrive automatically. Parents and guardians must submit the new IRS Form 4547 to open an account and elect the contribution, and early enrollment data already shows a wide gap between sign-ups and actual claims.
Why the July 4 deposit window changes the calculus for millions of families
The core tension is simple: 4 million children have been signed up for Trump Accounts, yet only 1 million are claiming the $1,000 pilot program contribution. That three-to-one ratio between enrollment and actual election of the funds suggests that awareness of the program alone is not enough. Families must take a distinct second step, filing Form 4547, before Treasury will release any money into a child’s account.
This gap raises a practical question about what drives completion rates. Household income is not a barrier to eligibility for the pilot contribution itself; the proposed regulations tie qualification to birth year (2025 through 2028), U.S. citizenship or residency, and a valid Social Security number. Because income does not gate access, the variable most likely to predict whether families actually file Form 4547 is whether they hear about the requirement and receive help completing it. States and localities running targeted outreach campaigns could see sharply higher submission rates than areas that rely on families to discover the form on their own.
Form 4547, proposed regulations, and the election requirement
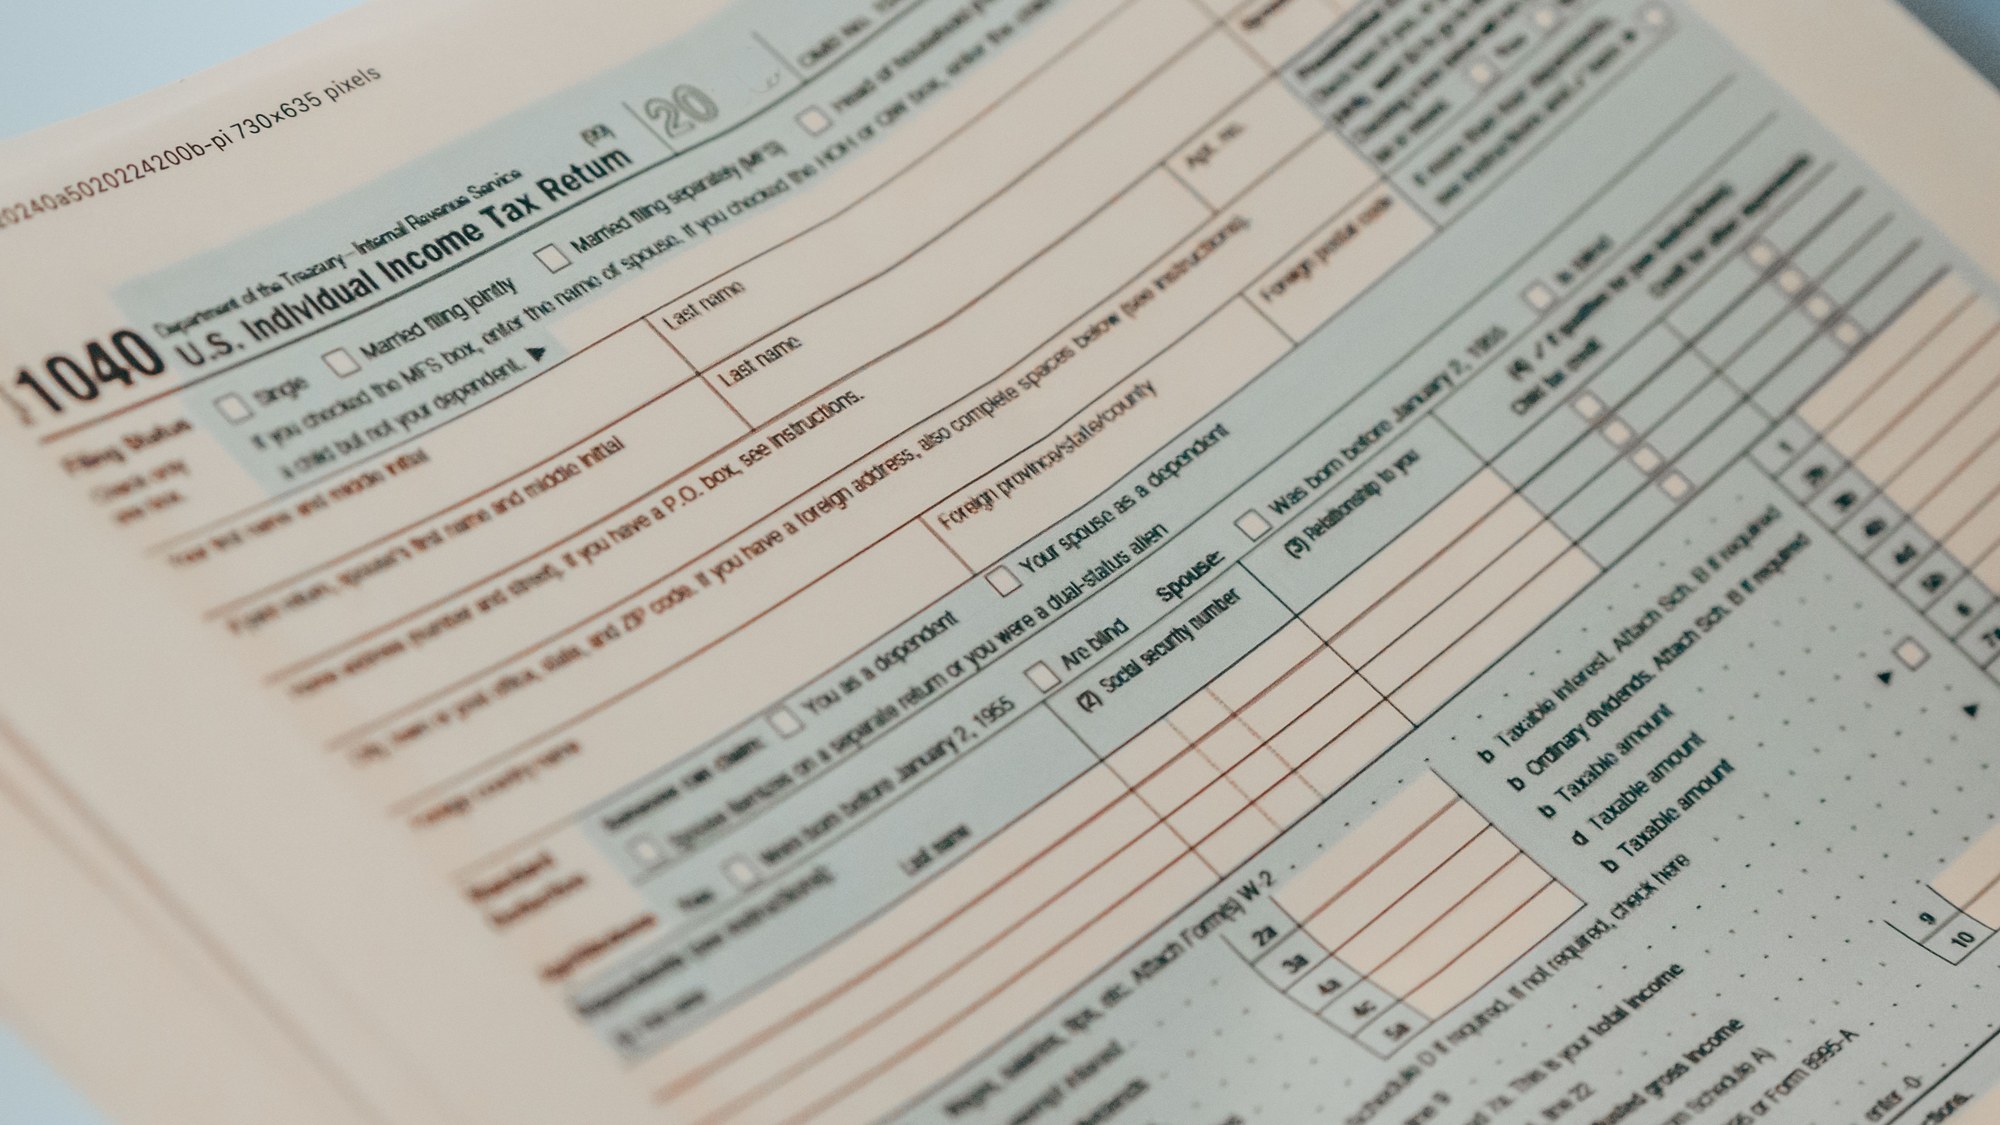
The mechanics are straightforward but carry a hard condition. Form 4547 serves two functions at once: it opens an initial Trump Account for the child and requests the one-time $1,000 pilot contribution from Treasury. A parent or guardian typically makes the election for the year it is filed, according to the IRS newsroom summary of the proposed regulations published in the Federal Register. The official IRS instructions clarify that submitting the form authorizes the IRS and Treasury, along with their agents, to create and maintain the account and handle related disclosures.
The legal foundation is strict on one point: no election means no deposit. The Internal Revenue Bulletin explains that the $1,000 pilot contribution cannot occur without a valid election under Section 6434. Treasury confirmed that beginning July 4, 2026, eligible children will begin receiving the deposit directly into their Trump Account, but only after the election is on file. Families who delay filing could miss the initial deposit cycle without a clear timeline for when subsequent processing batches will run.
How the pilot fits into Treasury’s broader savings agenda
The pilot contribution is part of a larger push by federal officials to seed long-term savings for children at birth. Treasury has framed Trump Accounts as a complement to existing tools like 529 college plans and custodial accounts, but with automatic infrastructure and federal backing. In a recent statement describing its child wealth initiatives, Treasury emphasized that early deposits can compound over decades and help narrow wealth gaps, particularly for households that have historically lacked access to investment products.
The July 4 launch date underscores that this is not a theoretical promise but a scheduled transfer of public funds. Treasury’s public communications describe the $1,000 contribution as a “starter stake” that will be invested in low-cost, diversified options unless a parent later selects a different allocation. The department has also signaled that pilot results-take-up rates, account balances, and demographic patterns-will shape decisions about whether to expand or modify the program in future years.
Administration officials have linked this effort to a broader agenda of building financial resilience. In press materials outlining its savings strategy, Treasury highlighted how even modest deposits can change families’ expectations about education, homeownership, and retirement. The Trump Account pilot is designed to test whether a universal, birth-year-based contribution can reach children across income levels without complex means testing.
What parents need to know about timing and process
For families, the immediate question is not the long-term policy arc but the practical steps required. The IRS has published detailed instructions for Form 4547 that walk parents through eligibility, documentation, and signature requirements. The form can typically be filed electronically through participating tax software or submitted by mail, and it asks for basic identifying information about the child and the parent or guardian making the election.
Officials stress that the filing deadline for the pilot contribution is tied to the child’s birth year and the schedule laid out in the proposed regulations, not to the tax-filing season. That means families who do not owe income tax or who are not required to file a return still need to submit Form 4547 separately if they want the $1,000 deposit. Community organizations, pediatric clinics, and schools are being encouraged to incorporate information about Trump Accounts into their outreach to new parents.
To support that effort, Treasury has outlined its broader children’s savings work in a recent press release on child-focused initiatives, emphasizing partnerships with states and nonprofits. Those collaborations are expected to play a central role in closing the gap between the 4 million children already enrolled and the far smaller share whose families have actually elected the pilot contribution.
The stakes for individual households are concrete. A family that files Form 4547 on time secures $1,000 that can grow alongside any additional deposits they choose to make, potentially turning into several thousand dollars by the time the child reaches adulthood. A family that overlooks the form forfeits that initial boost. As the July 4, 2026 deposit window approaches, the policy challenge is increasingly clear: converting passive awareness of Trump Accounts into active elections, one form at a time.