The federal government’s latest energy forecast projects that natural gas held in underground storage across the Lower 48 states should reach 3,969 billion cubic feet by October 31, 2026, a level the U.S. Energy Information Administration describes as about 5 percent above the five-year average for that date. The estimate comes from EIA’s September 2026 Short-Term Energy Outlook, an edition with a forecast completed September 3 and released September 9. Few households ever see the physical system behind that single number, even though it functions as the country’s buffer against a harsh winter and against sudden spikes in what utilities pay for the gas that heats roughly half of American homes.
Depleted Fields, Aquifers and Salt Caverns: Where the Gas Actually Sits
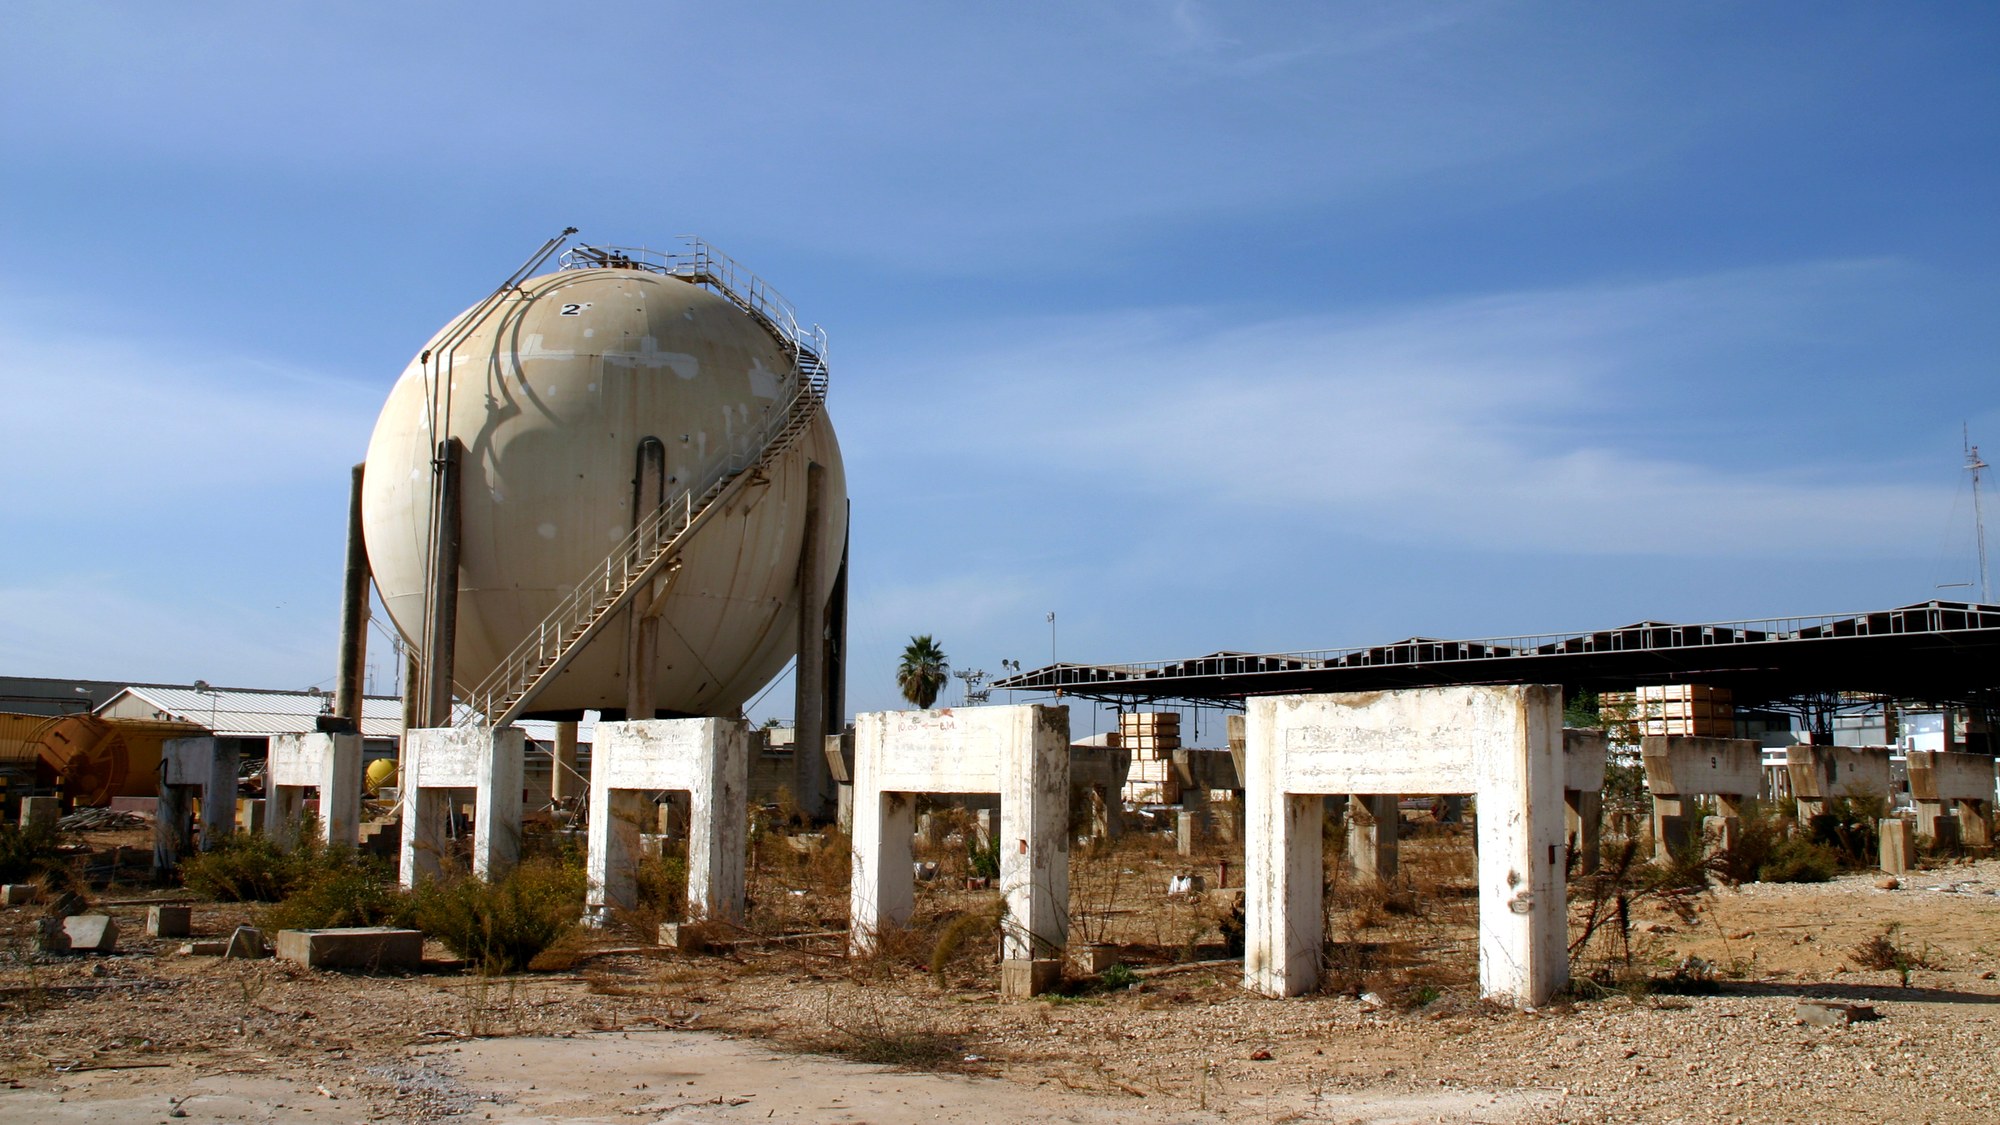
“Storage” does not mean a tank farm. According to EIA’s own explainer on underground storage, natural gas in the Lower 48 is held mainly in three kinds of geologic formations: depleted oil and natural gas reservoirs, water-bearing aquifers capped by impermeable rock, and salt caverns, most of them along the Gulf Coast. Nearly 400 active underground storage facilities, run by roughly 120 companies, hold that inventory today, according to EIA’s storage-basics reference. Each site carries a permanent volume called base gas, or cushion gas, that stays in the ground to maintain pressure; only the gas above that floor, called working gas, is what utilities and marketers can actually draw out and sell. Salt caverns can be filled and emptied several times a year and respond fastest to price swings, while depleted-field sites, the most common type nationally, tend to cycle once per season and rely on established wells and pipeline connections already in place. Aquifer storage sits in between: it typically needs more base gas to hold pressure and offers less flexibility for repeated cycling, but it has let regions of the Midwest without depleted fields or salt formations build storage close to where the gas is actually burned. None of these facilities are owned outright by the households whose furnaces eventually run on that gas. Interstate pipeline companies, local distribution utilities, and independent storage operators lease the bulk of that working-gas capacity to shippers and marketers, who move gas into the ground when demand is soft and pull it back out as winter tightens the market.
Free retirement updates: A quiet rule change can shrink your Social Security or Medicare check, and no one warns you. The free Retirement Shield newsletter catches these early and tells you what to do. Get it free.
Why the Refill Season Ends on October 31
The storage system runs on a fixed annual rhythm. Operators spend roughly April through October injecting gas into the ground, taking advantage of lower demand in the shoulder months to rebuild inventory. Once winter heating demand climbs, typically starting in November, that flow reverses into a withdrawal season that runs through March, drawing storage down to meet demand that pipelines and daily production alone cannot always cover on the coldest days. October 31 is treated as the benchmark date precisely because it falls at the hinge between the two seasons, the last snapshot of how much gas the country managed to bank before withdrawals begin in earnest. EIA’s Short-Term Energy Outlook publishes that projected end-of-October total every month specifically because it is the closest thing the market has to a starting balance for winter, according to the September 2026 Short-Term Energy Outlook, which pairs the 3,969 Bcf storage projection with a Henry Hub price forecast of $3.43 per million British thermal units for 2026 and $3.28 for 2027.
What a 5 Percent Cushion Above the Five-Year Average Actually Covers
The five-year average is not an arbitrary yardstick. Every week, EIA’s Weekly Natural Gas Storage Report measures that Friday’s inventory against the same week a year earlier and against the average level recorded for that same calendar week over the preceding five years, a method visible in the live report’s own historical-comparison tables, according to EIA’s Weekly Natural Gas Storage Report. A 5 percent surplus over that average means the country is entering winter with more gas banked than the recent norm, which tends to ease the pressure that a cold snap can put on prices. It does not mean prices are fixed or that a spike is impossible. A single stretch of unusually cold weather across a large region can push withdrawals well beyond a typical week’s pace, since heating demand does not wait for storage levels to catch up. Storage moderates the severity of a price spike during a cold snap; it does not eliminate the possibility of one, and traders price that risk into the futures curve regardless of how comfortable the October 31 number looks on paper. A surplus is also a national figure, averaged across the East, Midwest, Mountain, Pacific, and South Central regions the weekly report tracks separately; a region can run tight even in a year when the Lower 48 total looks comfortable, since storage capacity and pipeline access are not distributed evenly across the country.
A Comfortable Storage Number Does Not Set a Household’s Heating Bill
This is the honest limit of the storage story. A residential natural gas bill, or the gas-fired portion of an electric bill, is not simply the wholesale commodity price passed straight through. Distribution charges, pipeline and delivery infrastructure costs, and rates set through state utility commission proceedings typically make up a large share of what shows up on the monthly statement, and those charges move on their own schedule, largely independent of how full storage caverns are on any given October 31. A national storage surplus can exist in the same winter as a higher local delivery rate approved by a state regulator months earlier. EIA has not yet published its dedicated Winter Fuels Outlook for the 2026-2027 heating season, the report that typically estimates how average household heating expenditures are expected to move by fuel type and region, so no percentage change to winter heating costs can be attached to this storage projection. Until that outlook is released, the 3,969 Bcf figure is best read for what the September Short-Term Energy Outlook says it is: a projection of how much cushion the system is expected to carry into winter, not a forecast of what any household will pay to stay warm.
This article was produced with the assistance of AI and reviewed by The Financial Wire editorial team.
More Financial Reading
- What really happens to your joint savings account when you die?
- Bank statements: how long to keep them and when to toss them