An older homeowner who put a heat pump, a set of energy-efficient windows or a rooftop solar system into service in 2025, or who signed for a clean vehicle before autumn, is running out of federal tax return years to claim the credit behind that purchase. The four credits involved were accelerated to an early end under the 2025 tax law, cutting off years ahead of the schedules first written into the Inflation Reduction Act. For anyone who asked the IRS for extra time to file, the extended 2025 return — due October 15, 2026 — is the last return that can carry Form 5695 or Form 8936 with one of these credits attached.
The Vehicle Credit Window Shut on September 30
The New Clean Vehicle Credit under Internal Revenue Code Section 30D and the Used Clean Vehicle Credit under Section 25E both stopped applying to any vehicle acquired after September 30, 2025, under the accelerated termination written into this year’s tax law. Both credits had been scheduled to run for years longer; the new statute moved the cutoff forward sharply, and the IRS has confirmed there is no phase-down and no grace period built into either provision.
The New Clean Vehicle Credit itself was worth up to $7,500 for a qualifying plug-in EV or fuel-cell vehicle, available to buyers with modified adjusted gross income up to $150,000 for a single filer, $225,000 for a head of household or $300,000 for a married couple filing jointly, with the vehicle’s manufacturer suggested retail price capped at $80,000 for vans, SUVs and pickups or $55,000 for other models. None of those figures change the fact that the acquisition date is fixed at September 30, 2025 — a vehicle bought after that date does not qualify no matter what its price or the buyer’s income.
The agency’s guidance on the used-vehicle credit draws a narrow exception: a buyer still waiting on delivery can qualify if the vehicle was acquired under a binding written contract with a payment already made on or before September 30, 2025, even if it was not placed in service until later. Everyone else claims what they are owed on Form 8936, filed with the return for the year the vehicle was delivered. For a used electric or fuel-cell vehicle bought from a dealer for $25,000 or less, the credit runs 30% of the sale price up to $4,000, and it phases out entirely above $75,000 in modified adjusted gross income for a single filer or $150,000 for a married couple filing jointly — income levels that put the credit within reach of most retirees living on Social Security and a pension.
Free download: What each refund-status message means, the direct-deposit and paper-check paths, and when to follow up with the IRS. Get the free refund delay decision tree.
Heat Pumps, Windows and Solar Systems Had Until December 31
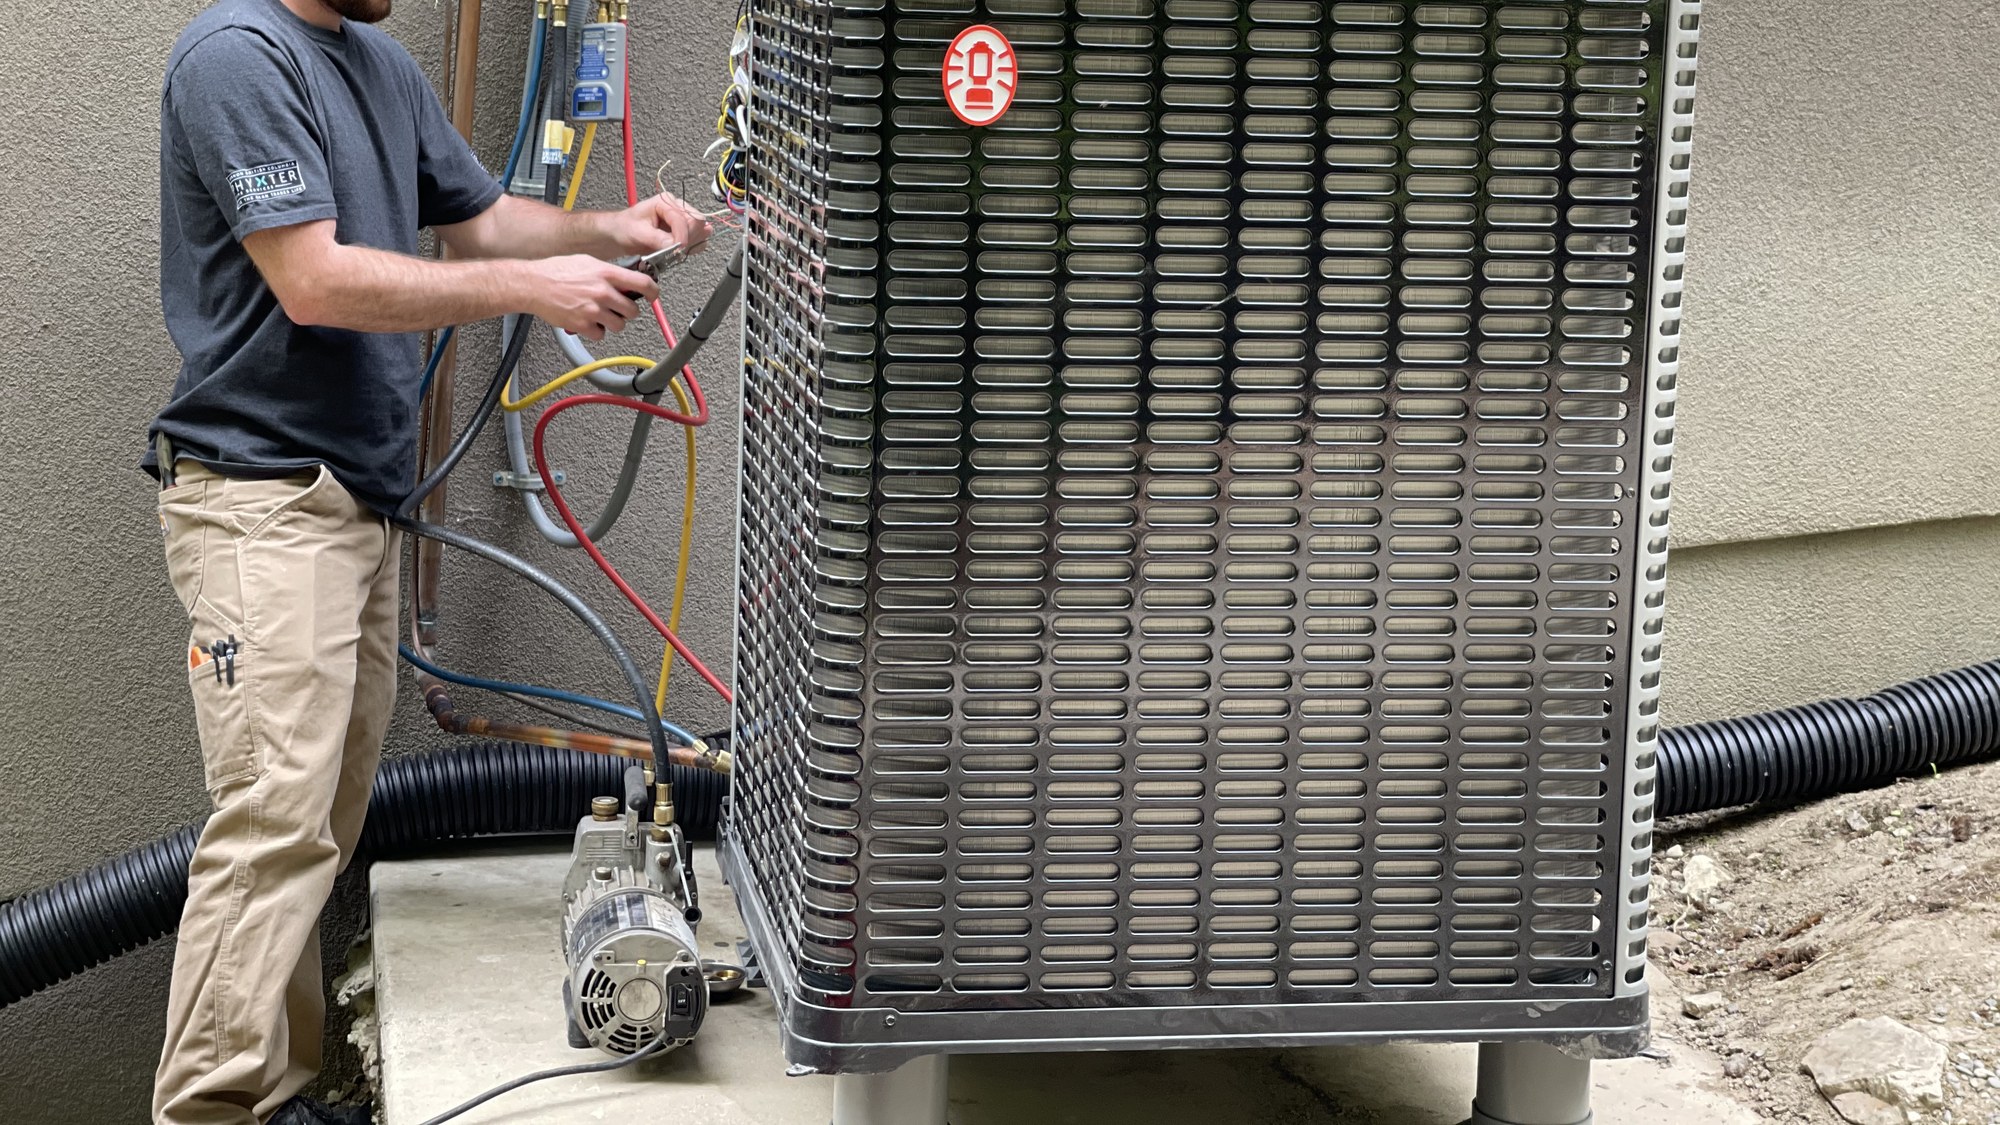
The Energy Efficient Home Improvement Credit under Section 25C covers exterior doors, windows, insulation, home energy audits and a short list of furnaces and water heaters, and it no longer applies to any property placed in service after December 31, 2025. The credit runs 30% of cost, with a $1,200 annual ceiling that itself splits into narrower limits — $500 total for exterior doors, $600 for windows and skylights, $150 for a home energy audit — plus a separate $2,000 annual allowance for a qualifying heat pump, heat pump water heater or biomass stove, for a combined maximum of $3,200 in a single year. Anyone who had a heat pump or new windows installed in 2025 claims against the year the equipment went into service, not the year it was ordered or paid for.
The Residential Clean Energy Credit under Section 25D, covering solar panels, solar water heaters, geothermal heat pumps, small wind turbines and battery storage, runs on the same December 31, 2025 cutoff but a different formula: 30% of cost with no annual or lifetime dollar ceiling, apart from a separate limit on fuel-cell property. A homeowner who placed a rooftop solar system in service anytime in 2025 can still claim the full 30% regardless of the system’s price, and unused credit carries forward to reduce tax owed in a future year — the one feature among these four credits that survives past the statutory cutoff.
Form 5695 and Form 8936 Are the Only Paperwork Left
Both home-energy credits are claimed on Form 5695, and both vehicle credits are claimed on Form 8936, filed with the Form 1040 for the year the property or vehicle went into service. For a 2025 purchase, that return was originally due April 15, 2026; anyone who filed Form 4868 to push the deadline back has until October 15, 2026 to file, and that extended return is now the final one that can carry either form — no version of either credit exists for tax year 2026 forward, so a taxpayer who misses the October date loses the credit outright rather than pushing it to next year.
The IRS’s own instructions add one more filter for 2025 installations: for many items claimed under the home-improvement credit, no credit is allowed unless the product was made by a qualified manufacturer and the taxpayer enters that manufacturer’s identification number on the return, a requirement the agency added specifically for property placed in service in 2025. A dealer’s time-of-sale report, kept alongside the vehicle purchase contract, plays the same role for Form 8936 — proof the IRS already has a matching record on file before the credit is claimed.
Tracking The Return After Form 5695 And Form 8936 Are Filed
Filing Form 5695 or Form 8936 on an extended return does not end the process; the return still has to clear IRS review, and a return claiming an expiring credit this size can trigger a status message or a follow-up notice asking for the paperwork behind it. Nothing in the credit rules explains what that status message means or how long a legitimate delay should run, and October filers are submitting during one of the processing system’s heaviest stretches of the year.
The IRS Refund Recovery Kit is a 13-page kit built around a notice decoder and a refund status tracker spreadsheet for that exact waiting period.
See the notice decoder and refund status tracker in The IRS Refund Recovery Kit.
This article was researched and drafted with the assistance of AI and reviewed by an editor.