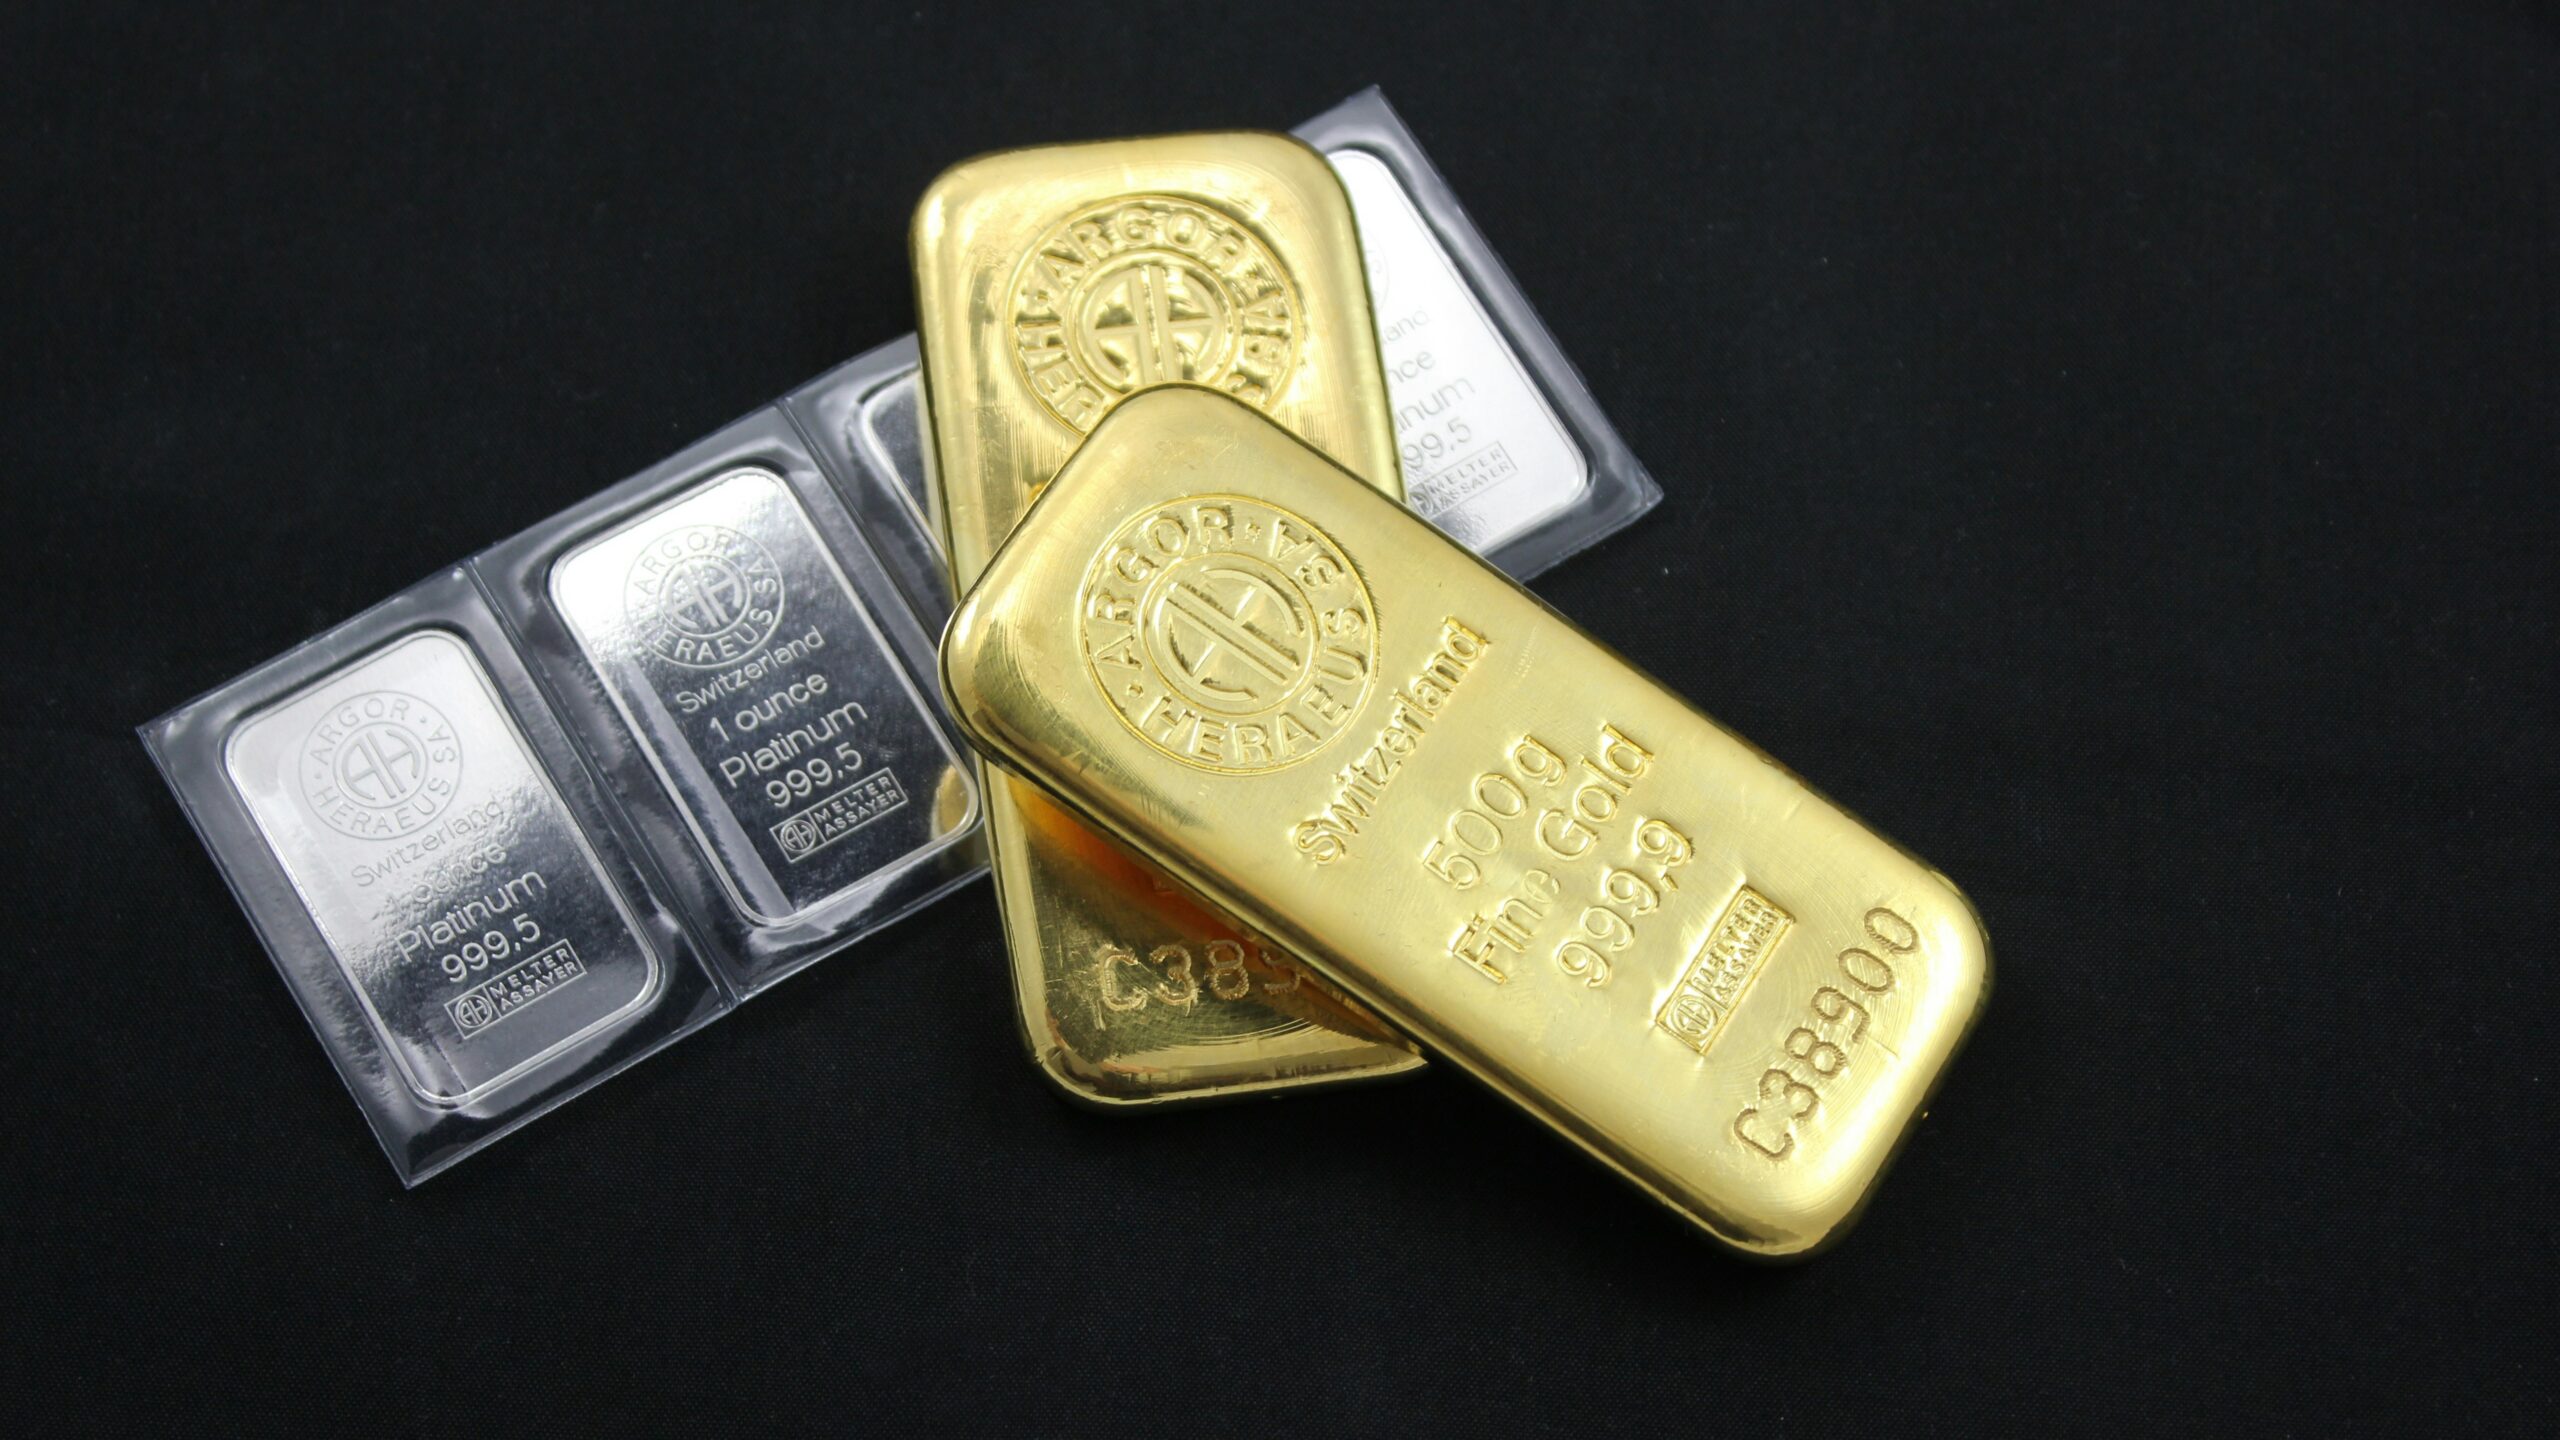
Gold can be real, delivered and still sold through an abusive transaction. The danger is not limited to counterfeit coins or a dealer that disappears with the money. Regulators have brought cases in which older customers received precious metals while losing a large share of retirement savings immediately to spreads, commissions and inflated claims about rarity.
The loss can be embedded in the purchase price
A precious-metals dealer normally sells above wholesale value and buys below it. That spread pays the dealer’s costs and profit. The problem begins when the customer is not told how wide the gap is, or when a salesperson presents a heavily marked-up collectible coin as a stable substitute for cash, bonds or a diversified retirement account.
The Commodity Futures Trading Commission warns in its precious-metals fraud advisory that aggressive sellers often target older people and use fear about banks, inflation or government policy to push immediate purchases. A buyer who pays 30%, 50% or more above the metal’s liquidation value needs an extraordinary price increase merely to break even.
That loss may remain invisible on the invoice. The document can show ounces, coin names and a total price without showing the dealer’s acquisition cost, the prevailing wholesale quote or what another dealer would pay that afternoon. A statement that an item is “worth” the retail price does not establish a market where it can be sold for that amount.
Free retirement updates: Scam calls targeting retirees change every week. Our free Retirement Shield newsletter flags the ones going around and the one tell that stops each. Sign up free.
Regulators documented retirement-account targeting
In a case brought with 30 state regulators, the CFTC alleged that Metals.com and related defendants took more than $185 million from at least 1,600 customers, most of them elderly. The agency’s resolution announcement said salespeople persuaded customers to liquidate retirement holdings and buy precious metals at grossly inflated prices. A federal court ordered restitution and civil penalties after the enforcement action.
The mechanism matters more than the company name. A caller learns that a household has an IRA or 401(k), describes a political or economic threat, and recommends moving quickly into coins. The dealer may help create a self-directed IRA and arrange a custodian, making the transaction appear independently approved. A custodian’s administrative role does not mean it assessed the price, quality or suitability of the metal.
Regulators also distinguish bullion from collectible or numismatic products. Common bullion has a price that can be compared with the metal’s spot price and quotes from several dealers. A supposedly rare coin requires specialized grading and an active collector market. The wider uncertainty gives a commissioned salesperson more room to claim a value that disappears when the customer tries to sell.
Three prices reveal the real transaction
A useful pre-purchase comparison includes the spot value of the metal, the dealer’s all-in selling price and the same dealer’s immediate repurchase price. The last figure answers the question that a glossy brochure avoids: how much of the account would remain if the position had to be liquidated right away.
Written disclosure should also identify every commission, storage fee, insurance charge, shipping cost and IRA-custodian fee. A dealer that will quote only percentages of future appreciation but not a cash buyback number is withholding the piece of information most relevant to a retiree’s liquidity.
The comparison must be for the exact product, not merely for “gold” or “silver.” Weight, purity, mint, year, condition and any third-party grade can affect the quote. A salesperson can therefore cite a rising spot price while selling a coin whose retail premium bears little relationship to the value of its metal. Written identifiers let another dealer quote the same item instead of a rough substitute.
Buyback terms deserve the same scrutiny as the opening price. A promise that the dealer “will buy it back” says nothing about the future bid, the spread that will apply or whether shipping and grading costs will be deducted. The immediate cash bid establishes the starting loss; a guaranteed formula would need to appear in the contract to change that calculation.
The SEC’s Investor.gov materials similarly caution that precious-metals pitches can combine leverage, high-pressure sales and unsupported safety claims. Borrowing to buy metal magnifies both price changes and transaction costs. Physical possession does not remove market risk, and storage outside the home introduces custody and insurance questions.
A hedge should not consume the portfolio it is meant to protect
Gold and silver can play a limited role in a diversified plan, but concentration changes the purpose of the purchase. Moving most retirement assets into one commodity ties income security to a single price and forces future expenses to depend on a dealer or market being available when cash is needed.
Sales pressure often arrives disguised as protection: a deadline, a warning that ordinary accounts are unsafe, or a claim that only a particular coin avoids confiscation. Independent quotes and a cooling-off period expose the economics. The underlying metal may be genuine; the retirement loss can still occur the instant an undisclosed markup turns liquid savings into inventory that cannot be resold near its purchase price.
This article was created with AI assistance and was reviewed, edited, and fact-checked by The Financial Wire editorial team.
More Financial Reading
- The ideal retirement withdrawal rate so your savings actually last
- How many CDs can you park at 1 bank? FDIC rules you must know


