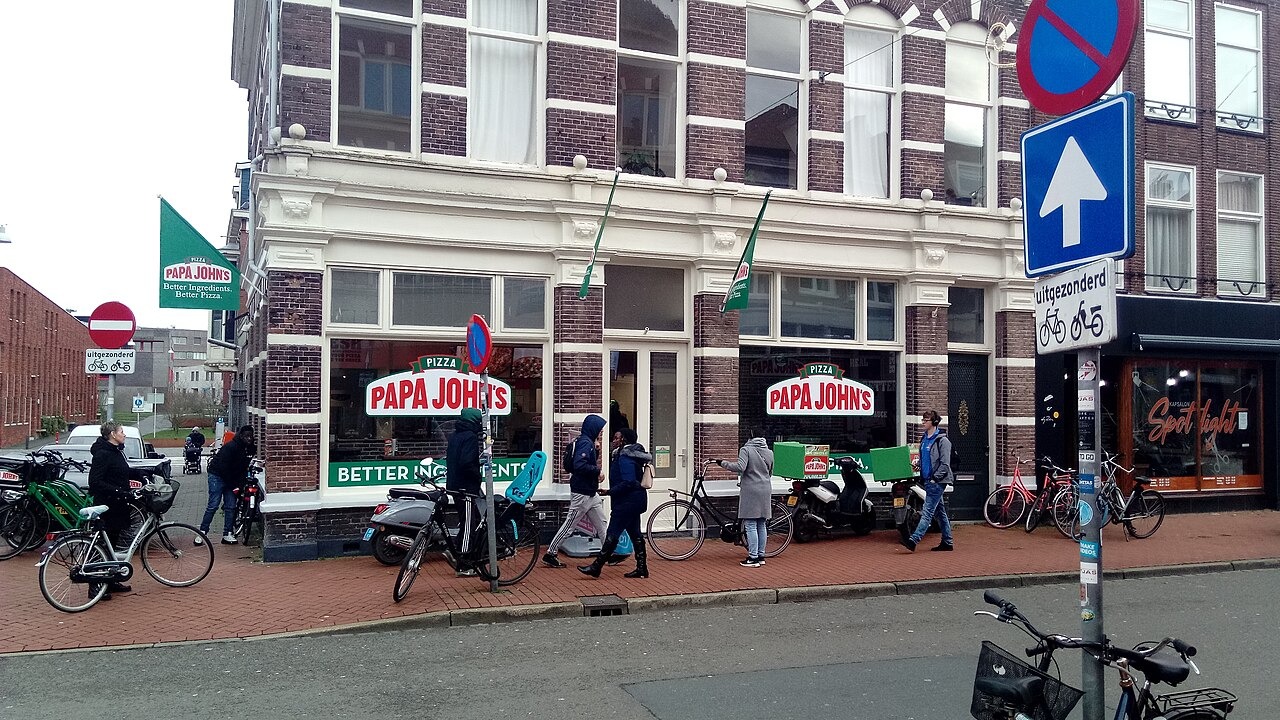
Papa John’s International closed nearly 50 restaurants and eliminated 7 percent of its corporate workforce this spring, moves disclosed in the company’s first-quarter 2026 earnings results filed with the U.S. Securities and Exchange Commission on May 7, 2026. The cuts land as the pizza chain works through a broader restructuring effort designed to tighten operations and improve per-store performance across its domestic footprint.
Why the spring closures and layoffs matter right now
The restaurant shutdowns and corporate staff reductions arrived during a single quarter, concentrating the pain in a narrow window. For franchise operators still open, the question is direct: will fewer locations translate into higher sales per store, or will the brand simply occupy less ground in an already competitive delivery market? The company’s own earnings materials frame the actions as part of ongoing transformation efforts aimed at long-term growth, but the speed and scale of the spring moves suggest urgency beyond routine portfolio management.
A reasonable expectation is that average unit volumes at surviving domestic locations will tick upward by the end of Q3 2026, as the chain redirects marketing spend and delivery coverage toward a smaller, theoretically stronger store base. That shift, if it materializes, would first show up in the company’s next quarterly operating metrics. Investors tracking the stock will look for exactly that signal in the next 8-K filing later this year.
The timing also matters for real estate and labor markets in the communities where stores went dark. Spring closures affect summer hiring pipelines and leave landlords searching for replacement tenants during a period when commercial vacancy rates in many suburban corridors remain elevated. Restaurant spaces built for high-volume delivery and carryout can be difficult to backfill quickly, especially if nearby competitors have already locked in the most resilient trade areas.
For affected workers, the 7 percent reduction in corporate headcount compounds the impact of front-line job losses tied to restaurant closures. Corporate roles often come with more predictable schedules and benefits than hourly store positions, so eliminating those jobs can ripple through local professional labor markets as displaced employees seek comparable work.
What the SEC filings show about Papa John’s Q1 2026
Papa John’s International filed a Form 8-K under Item 2.02 on May 7, 2026, formally furnishing its first-quarter earnings release to the SEC. The filing attaches the full results narrative and financial tables as Exhibit 99.1, giving the disclosure the weight of a regulated securities document rather than a simple press post.
The earnings release itself, labeled as a first-quarter financial update, provides the official corporate account of the quarter’s performance and references the company’s transformation initiatives. CEO commentary in the materials ties the restructuring actions to a plan for strengthening the chain’s foundation, emphasizing efforts to sharpen the restaurant portfolio and streamline support functions. However, the release does not break out which specific markets lost stores or which corporate departments absorbed the 7 percent headcount reduction, leaving readers to infer the operational focus areas from broader strategic language.
Because the earnings release is furnished as an SEC exhibit, analysts and journalists can treat its contents as the company’s formal, on-the-record account of the quarter. That distinction matters: promotional blog posts or social media announcements carry no regulatory accountability, while an 8-K filing does. If later disclosures materially contradict the narrative presented here, the company could face questions from investors and regulators about the consistency and completeness of its reporting.
The separate earnings narrative filed as an exhibit details revenue, comparable sales trends, and margin performance, and situates the closures and layoffs within a broader “transformation” framework. Management positions the first quarter as a foundational step, suggesting that pruning underperforming restaurants and resizing the corporate cost base are prerequisites for future menu innovation, digital improvements, and potential international expansion.
Open questions after the closures and staff cuts
Several gaps in the available record leave important details unresolved. The official earnings materials do not specify whether the closed restaurants were company-owned or franchise-operated, a distinction that changes who bears the financial and employment consequences. Company-owned closures hit the corporate balance sheet directly, while franchise shutdowns shift the burden to independent operators and their local employees. Without that breakdown, it is difficult to assess how much of the restructuring cost is centralized versus distributed across the franchise system.
The filings also do not disclose the geographic distribution of the nearly 50 closures. Concentrated exits from a few underperforming markets would signal a deliberate retreat from marginal trade areas, while scattered single-store closures could indicate a more surgical effort to remove chronic laggards. For customers, that difference shows up in whether an entire region suddenly loses access to the brand or only sees modest gaps in coverage.
Similarly, the 7 percent reduction in corporate staff is not mapped to specific functions. Investors and franchisees will want to know whether the cuts fell primarily on back-office roles, field support teams, technology, or marketing. Deep reductions in franchise support or technology resources, for example, could complicate execution of the very transformation initiatives management is promoting.
Another open question is how the company will measure success for this phase of restructuring. While the first-quarter materials reference long-term growth, they do not spell out near-term benchmarks such as targeted improvements in average unit volumes, domestic same-store sales, or restaurant-level margins attributable to the closures and layoffs. Clearer metrics would help outside observers determine whether the painful steps taken in early 2026 are delivering the intended operational benefits.
Until those details emerge in future filings or investor presentations, the spring cuts at Papa John’s will sit in a gray zone: large enough to signal a serious attempt at reshaping the business, but not yet transparent enough for stakeholders to fully judge whether the chain is simply shrinking to survive or actively rebuilding for a more profitable future.