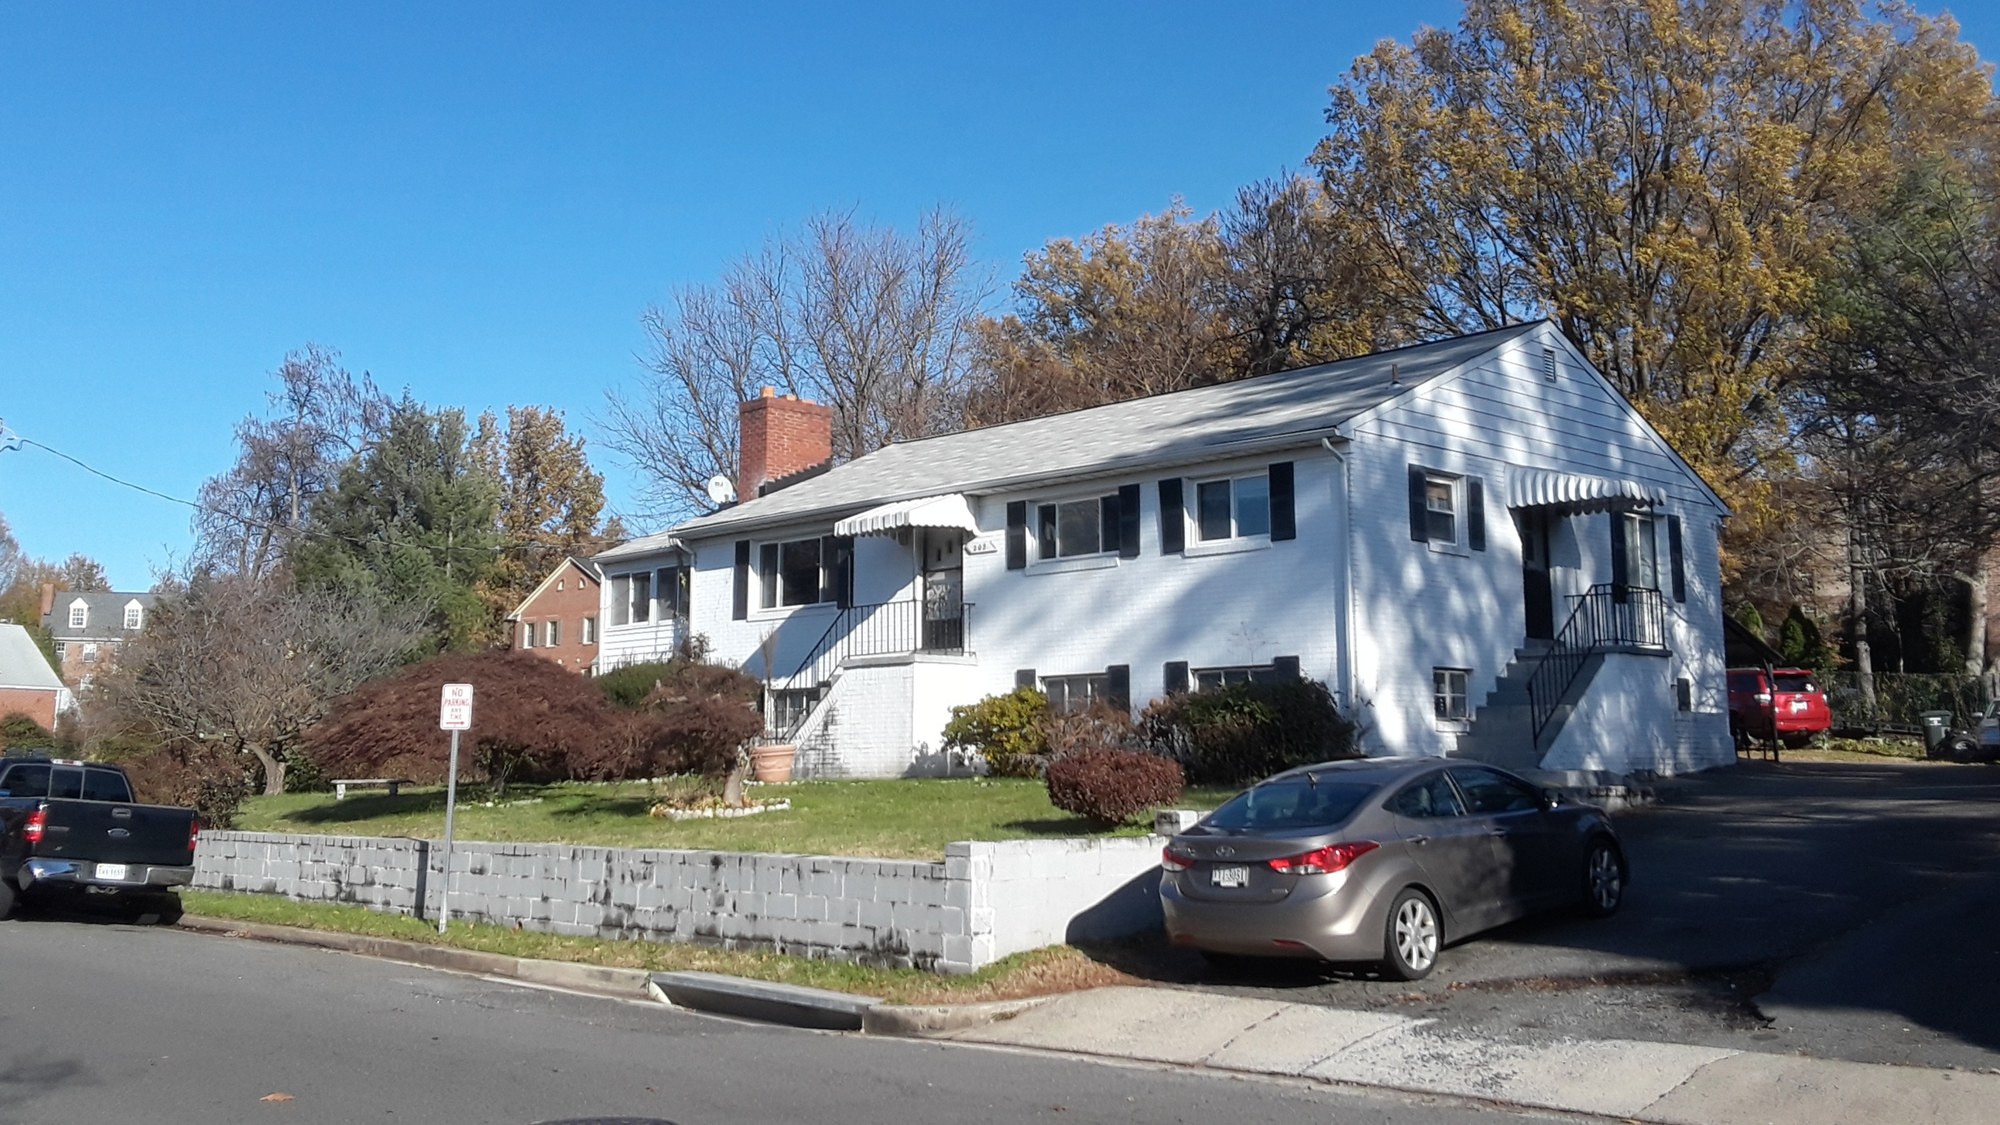
A homeowner can do everything right — pay every premium on time, never file a claim — and still open the mailbox to a notice that the policy will not be renewed, all because of a photograph taken from the sky. Insurers are increasingly inspecting houses from above using aerial, satellite, and drone imagery, and a stain on the roof or a limb hanging over the shingles can be enough to trigger a non-renewal. For retirees on fixed incomes, losing coverage and having to replace it in a tight market can mean a sharply higher premium on a home they have paid off for years.
How aerial imagery turns a roof into a red flag
The practice is straightforward. Rather than send an inspector to walk a property, an insurer pulls high-resolution images from satellites, planes, or drones and reviews them for anything it considers a risk. A worn or discolored roof, patches of moss, missing shingles, a tree branch touching the house, a trampoline in the yard, or a swimming pool without a fence can all get flagged from above. Some of what gets marked is genuine wear; some is cosmetic staining that has nothing to do with whether the roof actually leaks.
What makes this jarring for homeowners is the lack of warning. The first sign is often the non-renewal notice itself, arriving without a phone call or a chance to explain that the dark streaks on the roof are algae, not damage. By then the decision has usually already been made, and the homeowner is left scrambling to either satisfy the insurer’s demand for repairs or find a new policy before the current one lapses.
Free retirement updates: Want plain-English help keeping more of your money in retirement? The free Retirement Shield newsletter covers scams, benefits, and money many retirees may be owed, a couple times a week. Subscribe free.
Why a dropped policy costs a retiree more than the repair
The immediate expense may be a roof repair or cleaning the insurer demands, but the larger financial hit often comes from the coverage itself. A homeowner who loses a policy and has to shop for a new one enters the market as a higher-risk applicant, and in regions where insurers have pulled back, the replacement premium can be far above what the old policy cost. A mortgage lender also requires continuous coverage, so a lapse can create problems beyond price.
For older homeowners, this lands on a budget that has little give. Many retirees planned around a stable housing cost, and a jump in the insurance line — or a special roof assessment that has to be paid before coverage continues — can force hard choices. Understanding the rights that come with a non-renewal is what keeps a photograph from quietly costing thousands.
The rights a homeowner has when a policy is not renewed
A non-renewal is not the same as an insurer canceling a policy mid-term, and it is not the final word. Homeowners generally have specific protections, though the details are set by each state. As a rule, an insurer must give advance notice before dropping a policy at renewal — the required number of days is fixed by state law — and must provide the reason in writing when asked. That written reason is important, because it tells the homeowner exactly what the insurer saw and gives them something concrete to respond to.
A homeowner who believes the imagery was misread can push back: document the roof’s actual condition with a ground-level inspection or a licensed roofer’s assessment, provide photos or receipts showing recent maintenance, and ask the insurer to reconsider. A cosmetic algae stain, for instance, is not the same as structural damage, and evidence to that effect can matter. Where the insurer will not budge, appealing through the company’s process and then shopping other carriers are both on the table.
Where to turn: state insurance departments and the NAIC
Every state has an insurance department that regulates insurers and handles homeowner complaints, and it is the right place to take a non-renewal that seems unfair or a notice that did not follow the rules. These departments can explain the notice and appeal rights that apply in that state and can investigate a complaint against an insurer. The National Association of Insurance Commissioners, the body that coordinates state regulators, maintains consumer resources and a directory pointing homeowners to their own state’s department. Homeowners who cannot find coverage on the open market can also ask about their state’s FAIR plan, a last-resort program that offers basic property coverage where private insurers will not write a policy. For general ground rules on how homeowners policies work and what they cover, the Federal Trade Commission lays out the basics.
Getting ahead of the drone
Because these inspections happen without notice, the best defense is keeping a home camera-ready before an insurer looks. Clearing moss and algae off a roof, trimming branches away from the house, fencing a pool, and keeping records and dated photos of maintenance all reduce the chance of being flagged and give a homeowner ready evidence if a dispute arises. Reviewing a policy at renewal, rather than assuming it will simply continue, means a non-renewal is caught with time to act instead of days before coverage ends. A stained roof should not decide whether a retiree keeps the insurance on the home they own — and knowing the rules is what keeps that decision in the homeowner’s hands.
This article was produced with AI assistance and reviewed by The Financial Wire editorial team.
More Financial Reading
- What really happens to your joint savings account when you die?
- Bank statements: how long to keep them and when to toss them